
There IS an alternative
–Meltdown in rate futures suggests possibility of capitulation. Red, green and blue ED and SFR contracts plunged 18 to 21 bps on settle; new lows. Two year treasury at a yield of 4.12% (up 13) and tens jumped 18.6 bps to 3.702% in front of today’s October option expiration. New low in 5/30 treasury spread at -29 bps.
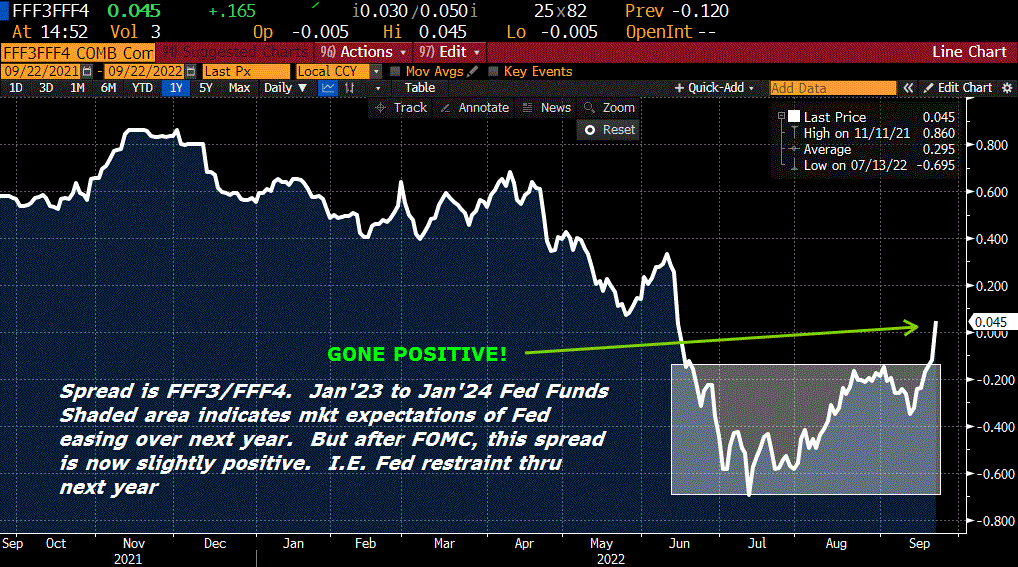
–If prelim open interest data is correct, net changes are indicative of a puke in the short end, though not in treasuries. Large OI changes: EDZ2 -35k, EDH3 -23k (all ED combined -28k). In SOFR: Z3 -36k. U3 -46k, Z3 -38k (all SFR combined -135k). The theme of the Fed holding rates relatively higher for longer appears to be gaining currency. For example, since the CPI release in June, FFF3/FFF4 calendar spread (a rough indicator of Fed action over next year) was negative, forecasting eases. The low in July was -69.5. Yesterday, this spread settled positive 4.5. There was buying of SFRZ2/Z3 (same idea) which closed -10.5, up 14.5 on the day. A couple of early 10k blocks: +SFRU3/SFRU5 at -106 and +SFRZ3/SFRZ5 -91.5 appear to have been closing trades (big declines in OI in U3 and Z3, so someone is taking profit on large shorts).
–Bloomberg has two headlines which capture the mood: ‘Investor Pessimism Hits-2008 Era High in Flight to Cash, BofA Says’ and ‘The Era of Inflation Has Ended – for Asset Prices on Wall St’. SPX is down just over 20% ytd, and the Fed appears to have become a put BUYER rather than seller. At down 20% in 2018, Treasury Sec’y Mnuchin was calling together the heads of the big banks to assure market liquidity. Now, the heads of big banks are in front of the House Financial Services Oversight Committee to be grilled on student loans and green initiatives. At first blush, one might think the BBG headlines are contrarian. However, at a 2yr yield above 4% and 5’s nearing 4%, and tips over 1%, large investors finally have an alternative safe port in which it pays to stay docked (with Mary Ann) OR Tina (Tina Louise as Ginger)

In: Eurodollar Options
If we weren’t in recession before, we are now
Sept 22, 2022
–As expected the Fed hiked 75 to 3.0-3.25%. New EFFR should be 308. FFV2 settled +4 at 9691.5. Projections were much different from my estimates. FF end of 2022 estimated at 4.4% which indicates another 125 bps in the next two meetings. FFF3 at 9575 is 4.25%, a spread of 116.5 to FFV2. That is, the Fed is slightly MORE aggressive than yesterday’s settles. By the end of 2023, the difference is even more dramatic. Fed fund projection is 4.6%, while FFF4 is 9587 (4.13%). Therefore, the Fed’s projections indicate another 20 bp rate increase in 2023, while the market perceives a tilt toward easing (FFF3/FFF4 settled -12). For the end of 2024, the Fed’s FF projection is 3.9%. So 2023 to 2024 indicates an ease of 70 bps (though the diffusion of dots for 2024 is fairly wide). The market is pretty much on the same page, though pricing indicates that rate cuts will come more rapidly than the Fed thinks. SFRH3/SFRH4 settled -65 (9550.5/9615.5) and SFRM3/M4 settled -78.5 (9556.5/9635), the latter spread being the most negative on the curve. The average of the two is right where the Fed is, an ease of 70 bps.
–GDP for 2022 was revised down to just 0.2 for 2022 and 1.2 for 2023. Both projections in June were 1.7. There have been a lot of badly missed estimates on inflation and growth, and my guess is that the unemployment rate will be wildly higher than the new peak estimate of 4.4% in 2023 & 2024. Let’s just follow the Fed’s trajectory of GDP for 2022. In December of last year, it was forecast at 4.0%. By March 2.8%. In June 1.7% and now 0.2%.
–New low in 2/10 at -48 bps. Stocks slumped to new lows as well. BOJ intervened in yen this morning, taking it from 145.5 to 142.5, as Japan’s continuing easy monetary policy undermines support for the ccy. SNB raised by 75. Short end of US curve is significantly lower this morning (higher rates) with the first two years of SFR contracts down 9.5 to 12.
In: Eurodollar Options
Fed day
September 21, 2022
–Yields pressed higher in front of today’s FOMC decision. Tens up 8.1 bps to 3.57%. Twos are nearing 4% ending at 3.96.
–The Riksbank surprised with a hike of 100 bps yesterday, but the Fed is nearly a lock for 75. However, FFV2 still settled 9687.5, which is 4.5 under the new EFFR of 308.
–Atlanta Fed GDP Q3 estimate was revised to its lowest level yet, at just 0.3%.
–SFRM3/SFRU3 is -15.5. SFRH3/SFRM3 is -7.5. If the press conference is convincing in terms of the Fed holding rates high until the job is done, these spreads should move toward zero.
–Projection for end of 2022 GDP was +1.7% in June. It will have to come down to below 1. Projection for year end (2022) FF was 3.4 in June. That will have to come up to 3.8 to 3.9. It will be interesting if the end 2022 FF projection exceeds end of 2023. In March, 2022 was 1.9 and 2023 was 2.8. In June, 2022 was 3.4 and 2023 was 3.8.
In: Eurodollar Options
Keep at it? Or pivot due to crumbling economy?
September 20, 2022
–Yields continue to press higher with the 2yr leading the way +9.2 bps to 3.946%. Tens rose 4.2 in yield to 3.489%.
–WSJ article by Nick Timiraos leaked the Fed’s displeasure over rising asset prices following last meeting. Inflation is still job number 1. The last dot plot was in June (which now feels like ancient history). In March, the FF projection for end of 2023 was 2.8% and for end of 2024 was also 2.8% (We’ll be through that rate tomorrow). In June, the end of 2023 projection was 3.8%, and end of 2024 was 3.4%. In other words, front-loading was expected to give way to eventual easing. Clearly the ED and SOFR curves represent the same idea, but magnified. EDZ3/EDZ4 settled -66.5, over 1/4% more inverted than indicated by the Fed’s 2023 to 2024 projections. The MOST inverted one-year calendar is EDM23/EDM24 at -77.5. One of the core messages of Powell’s brief Jackson Hole speech was to “keep at it until the job’s done”. Even SFRZ2/SFRZ3 is -26.5. Will it be safe to say that the job’s done by the early part of next year? I don’t know if the dot plot will push back against the market pricing of forward eases, but I think Powell is likely to do so in the press conference.
–The lowest that any forward one-year calendar has been this year was -84, it was the 2nd to 6th, in late July. The 3rd to 7th reached -82.5. Current lowest is June’23/June’24 at -77.5. New recent low made in Sept’23/Sept’24 at -75.0 yesterday. To see LOWER one-year spreads, one has to look back to 2007 when 2nd/6.th reached -95.
–The spreads are clearly indicating that the ‘front-load’ policy will succeed in crushing the economy, leading to a pivot sometime next year. The last Fed Fund projections reflected the same idea, though maybe with the idea of a ‘soft landing’. There is likely to be a mixed message regarding the dot plot and Powell’s comments, which could probably be smoothed by the idea of smaller forward rate increases that are likely to be longer in duration, with focus on balance sheet reduction.
In: Eurodollar Options
Signs the Fed’s strategy is ‘working’
September 19, 2022
–With December now the front contract in ED and SOFR, there is not a single positive one-year euro$ or sofr calendar spread until Sept’25/Sept’26, both settling +2. EDZ2/EDZ2 on Friday settled -37 (9547/9584) and SFRZ2/SFRZ3 at -31.5 (9578.5/9610). The most negative ED calendar is EDM3/EDM4 at -76.5 (9548.5/9625).
–I read a clip where a ‘strategist’ assured us that when the Fed stops hiking, stocks are going to take off. Um, every calendar being negative means that the market is forecasting easier Fed policy in the relatively near future. In fact, SFRH3/SFRM3 is -8.5 (9565.5/9574). So does that mean we should buy stocks NOW? Or mark our calendars for the start of Q2?
–CNY is above 7.0 this morning; the yuan has been consistently weakening since mid-April when it was 6.4. In front of Wednesday’s expected 75 bp hike from the Fed, USD continues to show strength, normally a sign of disinflation, but also representing an increasing degree of stress for non-domestic USD borrowers.
–Ten year note vs inflation-indexed ten-yr posted a new recent low of 239 bps, but in July the spread had bottomed at 230 (low for the year). Not sure if this is a valid proxy for long-term inflation expectations at this point, but certainly there are many signals that the Fed’s campaign is having its intended effect. Now we just have to see widespread job losses!
In: Eurodollar Options
FF > CPI by Q2?
September 18, 2022 – Weekly Comment
The event of the week is, of course, the FOMC result and press conference on Wednesday. Though there are a few outliers looking for a rate increase of 100 bps, FFV2 ended the week at 9688 or 312 bps, close to what will be the new EFFR of 308 on a 75 bp hike. What is perhaps of more interest is November Fed Funds which settled 9625, or 375 bps. This level roughly prices even odds of an additional 50 or 75 at the November 2 FOMC. Powell takes what the market allows.
The peak Fed Funds rate in 2006 at the end of that cycle was 5.25%. In that episode the Fed hiked 25 bps at every meeting, starting June 2004. What’s somewhat interesting is that the 30y yield peaked JUST PRIOR to the start of the cycle at 5.46% and at the very end, in mid-2006, was 5.25%. [Greenspan’s conundrum]. In looking at the 2015 to 2018 hike period, just before the onset, thirties peaked at 3.24% (mid-2015) and had a hard time getting though that level until the very end of the cycle, peaking only 20 bps higher at 3.45% in Nov 2018, (against the peak FF rate 2.25/2.50%).
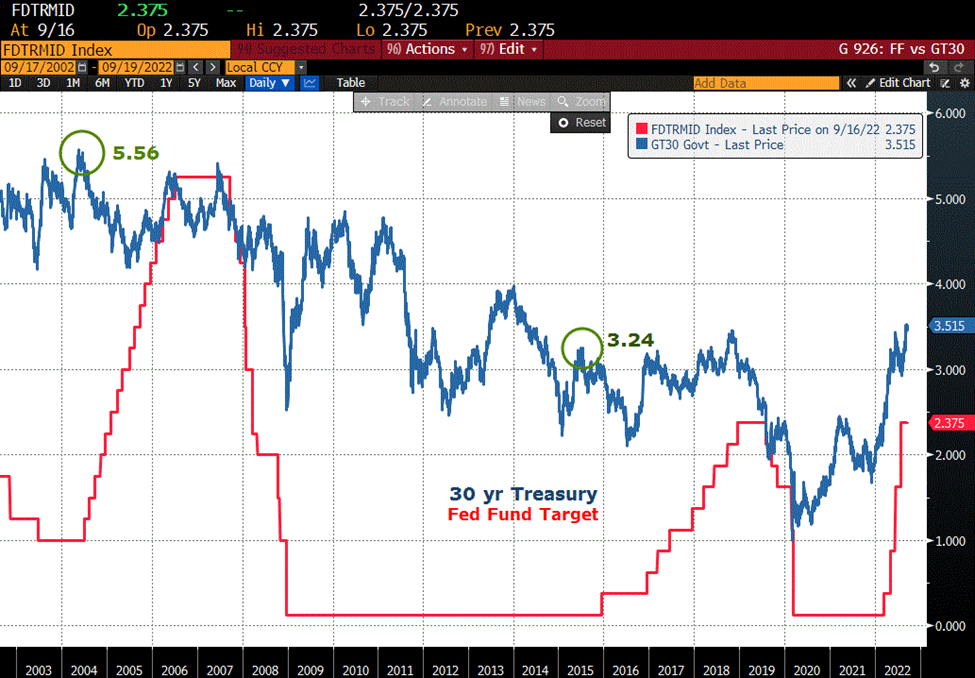
But that’s not the same case now. On Friday the thirty-year yield ended 3.51%, the highest since 2014. By the end of the 2004/06 hike cycle FF and 30yr were essentially equal. In the cycle ending 2018, the FF rate never approached the 30y yield until well after the Fed’s campaign stopped and long end yields were rapidly declining.
The difference now of course, is pernicious inflation. Let’s assume for a second that the Fed hikes 75 both next week and in November. EFFR will be 383, quite a bit higher than the current 30 yr yield of 3.51%. Even if the Nov hike is 50, EFFR will be 358.
Note that the lowest contract on the FF strip is April 2023 at a price of 9560.5 or 4.395%. The lowest ED and SOFR contracts are March’23 at 9541.5 (4.585%) and 9565.5 (4.345%). In my opinion, given the absence of Fed buying, 30yr yields should be adjusting higher. Certainly that IS the case with 30-yr mortgage rates, which this week set a new high of 6.02% according to the FRED data series, and 6.28% according to Bankrate.
Given that US curves forecast an end to rate hikes by Q2, it would be helpful to model CPI under various assumptions. There’s a helpful table on Mauldin’s ‘Thoughts from the Frontline’ citing Bespoke Investment Research of London. Given CPI prints that have already occurred through July, the table shows forward levels given 0.0% increases per month, 0.1%, 0.2%, 0.3% etc, If the monthly rate going forward were zero, by April 2023, CPI will be 2.48%. At 0.1%, 3.41%, at 0.2%, 4.34%, at 0.3%, 5.28% and at 0.4%, 6.4%. Note that FFJ2 is 4.395%, so if that contract were to be correct in its forecast of Fed hikes, then the rate it implies would be just higher than inflation (at that time) at increases in CPI of 0.2% per month. Both would likely be higher than the 30y yield. Note that in last week’s CPI release for August, CPI MoM was 0.1% and Core was 0.6%. PPI was -0.1% with Core +0.4%.
I can’t copy the Bespoke table, but here’s a link. Article title is ‘Inflation Sinks In’
https://www.mauldineconomics.com/frontlinethoughts
If inflation really does begin to moderate, it may be a much different picture by Q2 of next year. However, without the Fed buying, long yields should continue to adjust higher. Carry will be squeezed out and the decline in global trade perhaps means that fewer US dollars are recycled into treasuries.
Currently the highest point on the treasury curve is the 20-year at 3.78%. There is a 20y auction this week on Tuesday. The last round of auctions met with tepid demand. I don’t expect this one to be much better.
Going into the end of 2013’s ‘taper tantrum’ the 30-year yield peaked at 3.97%, about 50 bps higher than the current yield, though the Fed never even actually raised the FF target. In USZ 4% roughly corresponds to about 7.25 points lower in price, around 123-24 to 124-00.
************
NY Fed’s Global Supply Chain Index has declined for the past four months
https://www.newyorkfed.org/research/policy/gscpi#/interactive
Atlanta Fed GDP Now was about 1.3% for the first half of September, but on Sept 15 was marked down to 0.5%. Perhaps more worrisome, the Blue Chip Average forecast was marked down from 1.1% to negative 0.2%. More ominous than that, interest rates aren’t providing an offset to weakness in stocks and wealth destruction. Quite the opposite.
Selected changes in big caps and averages:
Percent Changes
Week ytd level pre-covid high
AAPL -4.2 -15.4 150.70 81.80
GOOGL -7.0 -29.7 102.80 76.23
MSFT -7.5 -27.9 244.74 188.70
META -13.5 -56.5 146.29 223.83
NVDA -8.2 -55.4 131.98 78.67
AMZN -7.3 -25.9 123.53 108.51
SPX -4.8 -18.7 3873 3386
COMP -5.5 -26.8 11448 9317
| 9/9/2022 | 9/16/2022 | chg | ||
| UST 2Y | 356.7 | 385.4 | 28.7 | |
| UST 5Y | 344.2 | 362.4 | 18.2 | |
| UST 10Y | 331.9 | 344.7 | 12.8 | |
| UST 30Y | 345.5 | 351.6 | 6.1 | |
| GERM 2Y | 132.7 | 153.3 | 20.6 | |
| GERM 10Y | 169.7 | 175.6 | 5.9 | |
| JPN 30Y | 131.0 | 128.7 | -2.3 | |
| CHINA 10Y | 264.2 | 268.0 | 3.8 | |
| SOFR Z2/Z3 | -32.5 | -31.5 | 1.0 | |
| SOFR Z3/Z4 | -49.5 | -65.0 | -15.5 | |
| SOFR Z4/Z5 | -10.5 | -18.0 | -7.5 | |
| EUR | 100.47 | 100.16 | -0.31 | |
| CRUDE (CLZ2) | 85.75 | 84.07 | -1.68 | |
| SPX | 4067.36 | 3873.33 | -194.03 | -4.8% |
| VIX | 22.79 | 26.30 | 3.51 | |
In: Eurodollar Options
Curves wailing
September 16, 2022
–Reds were crushed yesterday with EDU’23 thru M’24 down 12.875. Curve flattened to new recent lows. Two-year up 8.5 bps to 3.867, highest since 2007. 5’s up 7.5 to 3.671, highest since 2008. Bond yield barely changed, lashed to the mast of 3.5%, sailing past Scylla with sirens wailing all around. Oct FF (FFV2) settled +0.5 at 9686 moving just slightly away from the chance of 100 next week and closer to the sanity of 75 (a price of 9692). The ten-year inflation-indexed note closed 99.7 bps, a ‘real’ rate of 1%, high since 2018 (116 bps). New recent low in 2/10 at -41 bps, but 5/30 made a new low for the year at -19.3 with open field to the 2000 low of -57.
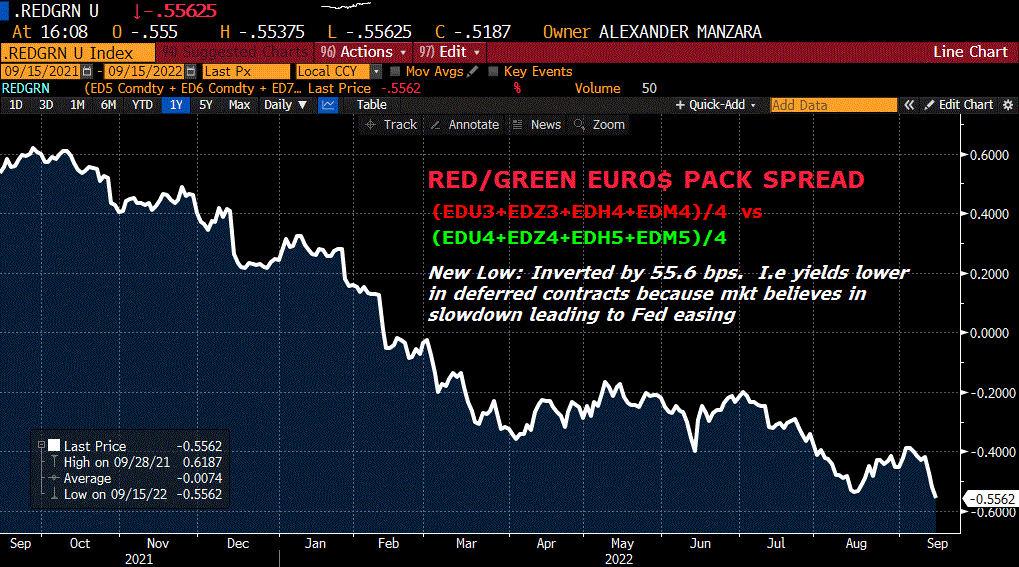
–The attached chart shows red/green ED pack spread, a new low at -56 bps. It has NEVER been this low and is unambiguously whispering to us that the economy is swirling the toilet.
–I had mentioned SFRZ4/Z6 spread which, at the end of August and a few days into Sept. had been bought on blocks of 10k each at -15.5 and then -5.5. It had almost poked its little nose above the surface of zero a few days ago, but was again clubbed like a baby seal and settled -18.5 (-4 on day; block of 5k at -18 yesterday). Again, I had thought it was a great expression for a Fed whose message was more gradual restraint…for a longer time. The market is telling us the Fed’s about to overdo it, hiking and QT’ing and forward guiding into a rapidly breaking economy, and stocks are starting to crumble.
–As Nasdaq faltered yesterday, notable buying occurred in TYX 117, 117.5, and 118 calls, settling 19, 15, 11 vs 114-16. About 32k of new open interest, mostly in the 118 strike.
–A couple of news clips below (Maybe Powell should just hike by 5% to make sure rates get above inflation…):
Sept 16 (Reuters) – U.S. stock index futures slipped on Friday, extending falls from overnight, after logistics industry bellwether FedEx withdrew its financial forecast and recession warnings from the World Bank and the International Monetary Fund.
Argentina to Hike Interest Rates to 75% as Inflation Nears 100%
In: Eurodollar Options
Runaway train
September 15, 2022
–In my opinion, a rail strike would be bad. In previous years, I had the sense that major issues would be solved, usually at the last minute, but that worst case scenarios would be gingerly side-stepped. I now have no confidence in that viewpoint. It’s all like watching, well, a slow-motion train wreck.
–A whole new round of supply chain issues? A rate hike of 100 basis points ought to help solve that, right? I don’t think so. On the other hand, outside of mortgages, perhaps the average household isn’t as negatively (directly) impacted by higher rates as I have thought. In the three years from 2018 to 2021, total household debt grew by about 15% in total. The consumer credit portion was less than 11% growth. On the St Louis Fed website, credit card rates on ‘accounts assessed interest’ were 15.5% in May 2018, reached a high of 17.1 in May 2019 and in May 2022 are 16.6. Onerous, but not WORSE. Total business debt growth from 2018 to 2021 was 20%, and that’s where the rate hikes bite more, causing unprofitable businesses to close. Federal gov’t debt over the same time period grew 41%. Of course, that was done to save us…
–My point is that rate hikes work through culling the business herd. A company that takes on debt to buy market share while losing money on every transaction with the ‘innovation’ being rapid food delivery will be forced to retract. Higher rates accomplish this over time. It doesn’t happen instantly, but the Fed’s goal of higher unemployment to weaken demand will occur. However, the real driver of growth has been gov’t. MMT proponents think that gov’t debt can always be sold… to someone. (I used to think the worst outcomes could be avoided).
–In terms of activity yesterday, flattening continues on perceptions of the Fed bringing down the hammer on inflation. The 2y yield rose 2.8 while the 30y fell 4. Ten year yield down less than 1 bp to 3.416%. 5/30 treasury spread made a new recent low of -12.4. The low of this year was in June at -17, and in April the low was -12.6. Before that, a low of -11.2 in 2006 and before that, in 2000, a low of -67.5. 100 next week would like send us hurtling back to 2000.
–Treasury vol fell across the curve yesterday. A mkt maker friend mentioned that the Oct TY straddle seems cheap in front of next week’s FOMC, given uncertainty about the size of the hike (thanks RK). Yesterday morning, at-the-money TYV 114.5^ opened 114/116, and near the end of the day the atm 115^ was trading 108. Here’s a snapshot comparison to levels from the July week-5 straddle prior to the July 27 FOMC. [week-5 expired the Friday after FOMC, just as TYV does]. On Friday, 7/22 with TYU 119-285, the 120^ settled 116 (same as yesterday morning). On Monday, 7/25 two days prior to the FOMC decision, the atm 119.75^ settled 102 (just 6/64s below yesterday’s close). The thought is that time decay has already been sucked out of the Oct straddle, leaving a cheap gamma play.
In: Eurodollar Options
Staircase up (trap door) elevator down
September 14, 2022
–CPI yoy expected 8.1% actual was 8.3%, Core was 6.3 vs 6.1 expected. Front end was annihilated. EDH3 down 29 bps. SFRH2 down 29.5…biggest move and the lowest contract on the strip at 9573.5 (prints even lower at 9569.5 this morning). On the FF strip the largest net change was FFJ3 -31 on the day at a price of 9567.5. That’s lowest price as well. April FF indicates EFFR of 432.5. Current EFFR is 233, so after next week’s 75 bp hike to 308 (target 3.0-3.25%), April FF is forecasting another 125 over the following four meetings. Peak FF rate in 2006 reached 5.25%.
–FFV2 settled 9684 or 316 bps, which is well through 75 (9692) and pushing for 100. Nomura raised its call to 100 for next week, and Summers also said the Fed should hike 100. January Fed Funds settled 9583.5, essentially 100 below October. FT has a headline indicating that QT is straining the bond market. Gundlach is counseling restraint and suggesting the purchase of long bonds as the Fed crushes the economy.
–The curve flattened hard. The five year yield soared 13.5 bps yesterday to 3.59%, while the thirty year was essentially unchanged at 3.51%. The high point is the 2yr just over 3.75% (up 18.5 on the day). Rosy forecasts about equities having bottomed were eviscerated with SPX -4.3% and Nasdaq -5.16%.
–Midcurve Sept straddles expire Friday. 0EU 9575^ settled 13.5 vs 9578.5 in EDU3. 2EU 9650^ settled 13.5 vs 9646.0 in EDU4 and 3EU 9662.5^ settled 14.0 vs 9667.0 in EDU5.
In: Eurodollar Options
Decelerating inflation supports bonds, but someone still has to BUY them
September 19, 2022
–CPI today expected 8.0 yoy vs 8.5 last, with Core 6.1 vs 5.9. USD continues its retreat this morning, with some looking for a 7 handle on the headline number.
–Yesterday the NY Fed released Consumer expectations:
“Median one- and three-year-ahead inflation expectations continued their steep declines in August: the one-year measure fell to 5.7% from 6.2% in July, while the three-year measure fell to 2.8% from 3.2%.”
Positive news for treasuries, yet auctions were poorly received, with the ten year tailing by 2.7. The yield was 3.33%, bid to cover 2.37, but at futures close the yield was 3.358. up 3.9 on the day. Thirty year auction today. Also today is NFIB small business optimism index, expected at 90.8 vs 89.9. The last two months were the lowest levels since 2013. Deteriorating economic data argues for higher bond prices, but somebody still has to actually BUY them, and it’s not the Fed
–At this point, expectations for 75 bps have solidified for next week, with FFV2 again settling 9694 or 306 bps, versus what would be the new Fed Effective of 308 on a hike of 75. The Oct/Nov FF spread settled up 0.5 to 50.5. Powell’s Jackson Hole speech was crystal clear about previous lessons: “keep at it until the job is done”. Pricing in the very short end has accepted the idea of moving to restrictive funding rates. However, SFRZ2/SFRZ3 remains inverted at -33.
–No 3-month libor setting on Monday Sept 19, due to the Queen’s funeral. EDU2 settles to libor; the CME will now use Friday’s setting as final settle.
In: Eurodollar Options

