
Bondra
May 23, 2025
****************
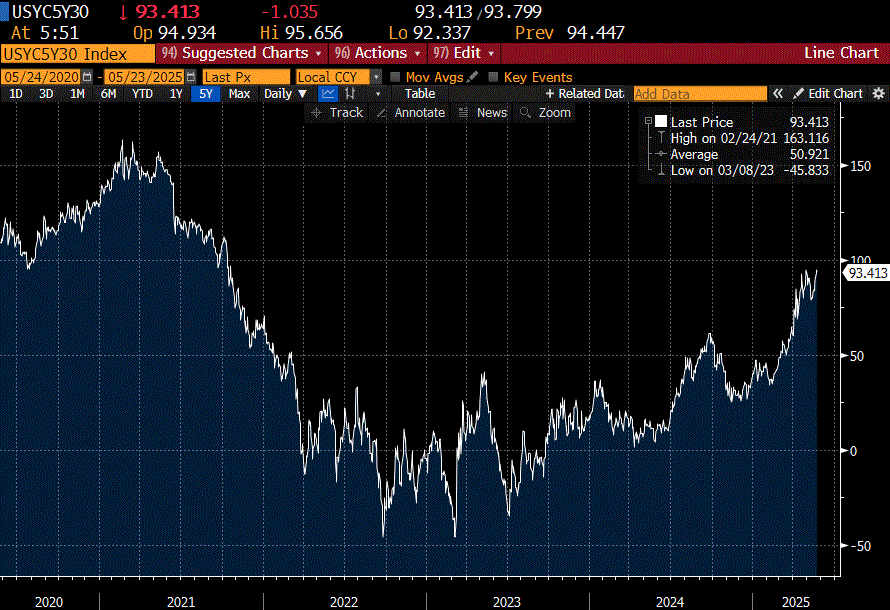
–Yields fell yesterday with 5s and 10s down 4.6 bps to 4.109% and 4.549%. However, 30s were only down 2.5, and 5/30 spread edged to a new high. I marked it just over 95 bps; BBG has the April 30 high at 94.9, I marked it 93.1 at the time of futures settle on Apr 30. Post GFC in 2010 this spread reached a high of 304 bps. Not shown on the five year timeframe chart below, but 100-105 should act as solid resistance. Whether its ‘term premium’, or concerns about the unsustainable negative spiral of US gov’t finances, or the price of rice in Japan (up 98.4% yoy with Core CPI +3.5%), or a monster butterfly (Mothra) flapping its wings somewhere, the US long end trades heavy.
they just don’t make them like that anymore
–For the past several sessions there has been buying of otm calls on SFRM5, notably 0.5 for 100k 9650c. Three weeks until option expiration. Yesterday a new buyer of >100k M5 future from 9568.5 to 9569.25. Settled 9568.25 with open interest in M5 up 103k, while aggreagate OI across all SOFR contracts was only up 104.5k. On May 21 the SOFR RATE setting was 4.26 or 9574, a new low. Surprising that SFRM5 remains anchored near the Fed Effective rate of 4.33% or 9567.
–SOFR option pit closes at noon Chicago time (1pm EST) and the treasury market closes at 2:00 pm EST, but of course CME electronic stays open until regular time.
5% breakout?
May 22, 2025
**************
–In October 2023 the 30y bond yield topped at 5.115% according to BBG. Since that time it’s been in a range of slightly below 4% to a cap of 5%. Yesterday at futures settle (USM5 110-25s) the yield was 5.087%. An upside breakout could easily target 5.5 or higher. Concerns about the tax bill and related high deficits are a factor, though yesterday’s 20y auction above 5% (5.047%) appears to have been the immediate spark. Analysts are also pointing to the jump in Japan’s 40y yield which is now > 3.6%. If the market is shunning long-dated ‘safe’ assets, then large US tech names are likely vulnerable.
–New buyer yesterday of 100k SFRM5 9650c for 0.5. Expiry in 22 days; SFRM5 settled 9568.25. Reach for wings can help cap risks in case things really start to spin out of control.
–Today’s news includes Chgo Fed National Activity, Jobless Claims expected 230k, S&P PMIs and Existing Home Sales.
A few option plays. Israel set to attack Iran?
May 21, 2025
**************
–The Philly Fed Services survey showed no bounce, coming in at -41.9 from -42.7 (Near covid lows). The last couple of days there’s been pressure on SFRZ5/Z6 1-yr calendar thru options, and yesterday it was similar, but thru calls. Z5/Z6 settled -47.0 (9619.5/9666.5), a new recent low. SFRU5/U6 is -73.0 so that’s a quarter percent roll over 3 months.
(On Monday, a synthetic Z5/Z6 roll-down trade: +Z5 9600/9562ps vs -0QZ 9626/9587ps paying 3.5 to 3.75 for Z5. Flattener (works with roll of curve) 23k traded. Yesterday a similar idea, but Dec’25/Dec’27: -8k SFRZ5 9650c (16,75s vs 9619.5) vs +8k 2QZ5 9675c (23.0s vs 9648) paid 5.0 to 5.25 for green. Works best if back end rallies due to stubbornly idle Fed in the face of deteriorating economy).
–New Buyer of 40k SFRM5 9725c for 0.25. News that Israel may attack Iran caused CLN5 to test April’s high. Last print +0.80 at 62.83.
–Buyer of 45k SFRZ5 9537.5/9487.5p 1×2 for zero. Current policy has EFFR 4.33% or 9567, right where SFRK5 and M5 have gravitated. This one looks for hikes going into year end. Crazy? Maybe not. No premium outlay…
–No real news. 20y auction. Curve a bit steeper yesterday with 2s down 1.1 bp to 3.968 while bonds rose 3.2 to 4.967%
–From Business of Fashion:
Chanel Pulls Back on Price Hikes as Sales Fall 4%
US long rates stabilize, Japan’s surge
May 20, 2025
**************
–US 30y bond yield popped over 5.03% in a reaction to Moody’s downgrade, but it didn’t stay there long, ending at 4.935% at futures settle (USM5 112-25s). This morning the financial press has jumped all over the surge in Japan’s long end. 10y JGB is up only 1.4 bps to 1.49%, but 20, 30, and 40y are all up about 12 bps to 2.52, 3.082 and 3.557. All have coupons of 2.4%, so the price of the 40y is 77.872. (Unrealized losses…not a problem unless they need to be realized, right SVB?)
–Net changes in US rate futures were small. 2y down a fraction to 3.979% with thirties up the most at 4.935% (+3.8 bps). First three years of the SOFR strip +2 to -0.5. One interesting SOFR option trade (adding), +20k SFRZ5 9600/9562.5ps vs -20k 0QZ 9625/9587.5ps paying 3.5 to 3.75. Settles: 13.0 and 9.25 vs futures Z5 9619.5 and Z6 9664.0. Nice structure to take advantage of the curve roll-down. Currently Z5/Z6 is -44.5, U5/U6 is -69.5 and M5/M6 is -84. Looking at June prices: M5 is 9569.5 (so the strikes on the Dec put spread would be well in the money) and M6 is 9653.5 so the 0QZ strikes would be out of the money. Could anything possibly go wrong? Well, back in March of 2023, calendars did surge (front months rose faster) in the wake of the regional bank crisis. However, all prices went higher, meaning neither put spread would likely end in the money.
–Home Depot missed this morning but the stock is up. Same store sales -0.3% vs expected -0.1%, however in the US same store sales rose 0.2%. Still, 0.2 isn’t anywhere close to matching inflation levels. Today’s news includes Philly Fed Services, which was -42.7 last, sinking to the lowest level since Covid.
Linda
May 18, 2025 – Weekly comment
***********************************
This is a slightly paraphrased excerpt from the Michael Lewis book, The Undoing Project:
The researchers, Amos Tversky and Daniel Kahneman posed this storyline:
Linda is 31 years old, single, outspoken and very bright. She majored in philosophy. As a student, she was deeply concerned with issues of discrimination and social justice, and also participated in anti-nuclear demonstrations.
Which of the following is more likely?
1) Linda is a teacher in elementary school
2) Linda works in a bookstore and takes yoga classes
3) Linda is active in the feminist movement
4) Linda is a psychiatric social worker
5) Linda is a member of the League of Women voters
6) Linda is a bank teller
7) Linda is an insurance salesperson
8) Linda is a bank teller and is active in the feminist movement. (page 324)
Danny passed out the Linda vignette to students at U of British Columbia. In this first experiment, two different groups of students were given 4 of the 8 descriptions and asked to judge the odds that they were true. One of the groups had ‘Linda is a bank teller’ …and the other got ‘Linda is a bank teller and is active in the feminist movement.’ Those were the only 2 descriptions that mattered, though of course the students didn’t know that. The group given ‘Linda is a bank teller and is active in the feminist movement’ judged it more likely than the group assigned ‘Linda is a bank teller’
…’Linda is a bank teller and is active in the feminist movement’ could never be more probable than ‘Linda is a bank teller’. The former is just a special case; one description was entirely contained by the other.
Ultimately, they gave the subjects the same description of Linda and asked simply, “Which of the two alternatives is more probable?”
Linda is a bank teller
Linda is a bank teller and is active in the feminist movement.
Eighty-five percent still insisted that Linda was more likely to be a bank teller in the feminist movement than she was to be a bank teller. The Linda problem resembled a Venn diagram of two circles, but with one of the circles wholly contained by the other. But people didn’t see the circles.
***********************
On Friday the University of Michigan survey of expectations was released. The survey respondents judged that inflation one-year ahead is likely to be 7.3%, up from 6.5% a month ago, and that 5-10 year inflation will be 4.6% up from 4.4%. General Economic Expectations plunged to 46.5 from a projected 48.6, at the lowest level ever. Or at least since 2000.
The U of M survey highlights the hard-data, soft-data divide. There’s a more detailed analysis of results on ZeroHedge, which describes wide differences in the Michigan Survey based on political affiliations.
https://www.zerohedge.com/personal-finance/umich-sentiment-collapses-near-45-year-record-lows-democrats-inflation-dissonance
The Linda problem underscores a facet of human nature, which is a tendency to grasp a narrative and (sometimes irrationally) extend its effects. “I’m running with it!” The current news cycle is all tariffs, all the time. It’s little wonder that forward scenarios might be wildly imaginative and off the mark, leading to surprising survey results. (Does AI necessarily capture logic, or might large-language models perpetuate a fallacy?)
On the other hand, there are some undeniable reports of negative hard data:
SFGate:
CNBC and Reuters reported that Microsoft is laying off around 6,000 employees, or a bit under 3% of its humongous staff. The company’s WARN filing in Washington, where Microsoft is headquartered, included 1,985 workers. (Companies are generally required by the Worker Adjustment and Retraining Notification Act to file these documents in the event of mass layoffs.)
Moody’s overtly recognized the unsustainable path of US fiscal policy and took its credit rating down a notch Friday post-close.
The NY Fed’s Household Credit report notes:
Missed federal student loan payments that were not previously reported to credit bureaus between 2020Q2 and 2024Q4 are now appearing in credit reports. Consequently, 7.7% of aggregate student debt was reported 90+ days delinquent in 2025Q1 compared to less than 1% reported in 2024Q4.
Aggregate delinquency rates rose from the previous quarter, with 4.3 percent of outstanding debt in some stage of delinquency. [4.3% is above all levels since covid, but below everything from the GFC to 2019. 2016 to 2019 relatively stable around 4.5%]
There are many reports on Reddit of people with un-serviced student loan debt seeing their credit scores chopped by 100 to 200 points.
Regarding forward inflation, I used to think that estimates were highly correlated to the price of oil. But CLM5 closed at 62.49, pretty much the lowest level for front-month since 2022. As Luke Gromen notes, one ounce of gold buys 51 barrels of oil, up from just 15 bbls in summer of 2022.
Retail Sales last week were softer than expected. Walmart issued downbeat forward guidance given “uncertain times”. Target reports earnings before the open on Wednesday. Home Depot on Tuesday. Lowes on Wednesday.
**********************************
On the week the two-year yield rose 10.2 bps to 3.983% as Fed easing prospects are torched. Fives up 7.8 bps to 4.063%, tens up 6.8 bps to 4.439% and thirties up 6.6 bps to 4.897%. MOVE eased further to just 96.70, having surged post-Liberation day to 140.
On the SOFR strip, SFRH6 and M6 were hammered, with H6 down 16 to 9637.5 and M6 down 15.5 to 9651.5. May SOFR options settled Friday and the front SFRK5 (May 3m SOFR) settled 9567.5. So, even with the recent rise in yields following early April turbulence, SFRH6 is fully 70 bps lower in yield than SFRK5, which is essentially at the Fed Effective rate of 4.33%. Easing is still priced into forward rates, though much less dramatically so.
There was a somewhat odd trade on Friday: a new buyer of SFRM5 9725c for 0.25 (10k), and when those were no longer available at 0.25, he bought 15k M5 9725/9750c stupid for 0.5 (paid 0.25 for each). Obviously someone could have known about the upcoming Moody’s downgrade and wanted to cap upside risk. Surprising that calls over 150 bps otm with one month left would still be worth 0.25, especially when 9625c settled 0.5.
Economic news is light this week, but geopolitical events are fluid. 20y auction on Wednesday.
| 5/9/2025 | 5/16/2025 | chg | ||
| UST 2Y | 388.1 | 398.3 | 10.2 | |
| UST 5Y | 398.5 | 406.3 | 7.8 | |
| UST 10Y | 437.1 | 443.9 | 6.8 | |
| UST 30Y | 483.1 | 489.7 | 6.6 | |
| GERM 2Y | 178.5 | 185.5 | 7.0 | |
| GERM 10Y | 256.2 | 259.0 | 2.8 | |
| JPN 20Y | 234.4 | 237.3 | 2.9 | |
| CHINA 10Y | 163.5 | 168.2 | 4.7 | |
| SOFR M5/M6 | -92.5 | -82.0 | 10.5 | |
| SOFR M6/M7 | 2.5 | -4.5 | -7.0 | |
| SOFR M7/M8 | 21.0 | 19.0 | -2.0 | |
| EUR | 112.56 | 111.65 | -0.91 | |
| CRUDE (CLN5) | 60.58 | 61.97 | 1.39 | |
| SPX | 5659.91 | 5958.38 | 298.47 | 5.3% |
| VIX | 21.90 | 17.24 | -4.66 | |
| MOVE | 100.40 | 96.70 | -3.70 | |
30y yield tests 5%, but falls from there
May 16, 2025
**************
–Nice bounce in rate futures as Retail Sales were soft and PPI lower than expected. Sales at sporting goods and hobby shops fell 2.5% (headline retail sales +0.1%). Ten year yield fell 7.3 bps to 4.453% while the 5y led, falling 8.8 to 4.071%. On the SOFR strip, the peak contract is still SFRZ6, up 11 on the day to 9662.5 (3.375%).
–Tone was set early by some massive new buys in ERIS swap contracts, June’25 five and ten year contracts, (YIWM25 and YIYM25). Open interest in both contracts doubled, with fives +47k to just under 91k open and tens +59k to 122k. According to erisfutures.com 5y DV01 is 44.50 and 10y is 59.45. So 10y buys are ~ $3.5m DV01. Just for the sake of comparison, TYM5 DV01 is $63.70 and open interest is near 5 million contracts. In any case, both TYM5 and USM5 had outside days and closed near the highs; reversal days. Thirty year yield yesterday tested a new high at 5% but ended at 4.919% (USM5 113-02s)
–Housing Starts today expected 1364k from 1324k last. From Melody Wright:
21 of the 85 cities I track had both YOY and MOM price declines in April, including Los Angeles. Up from 19 last month. In the high season
–Also today: U of Mich Inflation Expectations 6.5% last (1y) and 4.4% (5-10y)
Summary of ERIS futures BLOCK (BT) buys (Ed Bolingbroke, BBG)
5Y—–>
10:54:47 250 97.8300 BT NT
09:24:17 5k 97.9100 BT NT
09:21:18 5k 97.9200 BT NT
09:11:07 5k 97.8700 BT NT
08:55:40 7.5k 97.7200 BT NT
08:57:54 7.5k 97.7300 BT NT
09:06:51 5k 97.8000 BT NT
08:52:43 7.5k 97.6600 BT NT
08:49:12 7.5k 97.6300 BT NT
08:17:45 500 97.6200 BT NT
10Y—–>
09:22:50 5k 94.3400 BT NT
09:29:37 2.5k 94.4200 BT NT
09:18:05 10k 94.3800 BT NT
09:14:25 5k 94.2800 BT NT
09:04:12 10k 94.1200 BT NT
09:05:55 5k 94.1000 BT NT
08:57:03 5k 93.9400 BT NT
08:51:11 5k 93.8200 BT NT
09:00:37 5k 94.0200 BT NT
08:53:42 5k 93.8400 BT NT
08:48:23 5k 93.9000 BT NT
Plenty to talk about…
May 15, 2025
**************
–CLM5 (wti crude) down 2.49 at 60.66 this morning as Trump says close to deal with Iran. Stocks also pulling back.
–News today includes Retail Sales expected 0.0 m/m and +0.3 ex-auto and gas. WMT earnings. PPI expected +0.2. Yoy 2.5% from 2.7 and Core 3.1% vs 3.3 last. Powell at 8:40 on Framework Review. The last review in 2020 featured the ill-fated FAIT (average inflation targeting) which was supposed to allow inflation to average a bit over target in order to compensate for previous shortfalls below the 2% target. If really working on an average we should be targeting ZERO for the next few years.
–30y bond yield at futures close was 4.964% (USM5 112-12s). However, as USM traded post-settle at 112-09 the yield moved to 4.973, essentially matching the high of the year set in January at 4.977. This is mostly a long duration issue. For example, the Jan high in 10y treasury yield was 4.794% and yesterday late it was 4.536%. As mentioned earlier in the week, Kevin Muir noted that higher yields would cause a shift in cheapest-to-deliver bonds to much longer duration issues into US and WN. I think that’s a big part of the price action, along with general distrust of gov’t finances, etc. The tv gurus are going to chalk it up to “term premium”. Note also a slight new recent high in 10y treasury to tip breakeven to 239 bps. It was more like 240 to 250 in Jan and Feb but the recent low was below 220.
–If long end yields keep rising and CTD shifts to higher duration, that would also imply higher bond vol on a relative basis, which is another current feature. Might also tend to put a bid into gold SOFR midcurves. 4QM 9612.5^ settled 25.5 ref 9609 in SFRM9. 0QM 9637.5^ settled 27 ref 9643.5. Worth looking at otm 4QM or 4QN puts?
–I didn’t see the actual recommendation so I won’t mention the bank, but the trade was to sell SFRZ5/Z6 at -34 with a stop at -10 and target -70. Risk 24 to make 36. Not spectacular, but of course curve roll is at your back. M5/M6 is -73.5 and U5/U6 is -59.5. Z5/Z6 settled -37.5 (9614/9551.5). In mid-March the spread was -20 and in the beginning of Feb it was 0. The risk is an outlier event or something like a negative payroll number that causes nearer contracts to explode higher (think back to SVB collapse). In any case, after I saw this rec, there was an option trade expression of ‘sell z5/Z6’. A buyer of 40k SFRZ5 9600/9562.5ps vs 0QZ 9625/9587.5ps, paying 2 for Z5. Settled 14 and 11.75 so 2.25. Just comparing this Dec structure to same strikes in Sept, one can see how the roll works in this trade’s favor: SFRU5 9600/9562ps settled 20.0 (ref 9593) and 0QU5 9625/9587ps settled 9.75 (9650) so spread to spread settled +10.25. Just bear in mind a friend’s warning: “The road to hell is paved with positive carry [roll]”
Rates push higher
May 14, 2025
***************
–Rates continued to push higher, even as CPI data was better than expected at 0.2% on the month and 2.3% yoy. If using CPI, then FF can be considered restrictive, as the spread is now 200 bps (EFFR 4.33%). Front end SOFR contracts weakest with SFRU5 down 3.5 to 9593.0. On May 1 the JUNE contract traded as high as 9594.5 (yest settle 9570) so the adjustment in front end has been harsh, as possible Fed easing has been priced out.
–Waller spoke this morning about Fed economic research; nothing about current policy. Jefferson at 9:10 on the economy.
–Stocks continued to rise with SPX +0.7% and around flat on the year. The curve steepened, with 2’s up 1.5 bps to 4.015%, 10s +4 bps to 4.497% and 30s up 5.3 to 4.942%.. According to BBG the high yield in 30s this year is 4.977%. Bonds ignored better than expected inflation data (bearish sign).
–One stock worth noting is UNH, which was down 18% yesterday at 313 and is down nearly 50% from the April 11 high of 599.47. Current mkt cap $282 billion; a lot of wealth evaporated.
–Interesting SOFR opt trade: 35k SFRU5 9575p bot vs sold 0QU5 9612.5p for credit 4.0 to 4.25. U5 9575 puts settled 5.5 vs 9593 (18 bps out) while 0QU 9612p settled 10.25 vs 9655 (42.5 otm). Consider June contracts now: M5 settled 9570 so 9575p in-the-money, while SFRM6 settled 9649. I.e. the roll-down in near contracts is large relative to backs (reds).
–A couple of notes from the Fed’s Household Debt report. It turns out that delinquency rates rise without forbearance (unless it’s commercial RE).
Household Debt Hits $18.20 Trillion; Student Loan Delinquencies Jump
Total household debt increased by $167 billion to reach $18.20 trillion in the first quarter, according to the latest Quarterly Report on Household Debt and Credit. Credit card balances fell by $29 billion from the previous quarter to stand at $1.18 trillion; auto loan balances declined by $13 billion to $1.64 trillion, marking only the second time balances have fallen from a prior quarter since 2011. Student loan balances grew by $16 billion to reach $1.63 trillion, and the data show a large uptick in the rate at which balances went from current to delinquent, due to the resumption of reporting student loans on credit reports after a nearly five-year pause. Mortgage balances increased by $199 billion to reach $12.80 trillion and HELOC balances rose by $6 billion to $402 billion. Aggregate delinquency rates rose from the previous quarter, with 4.3 percent of outstanding debt in some stage of delinquency. Transition into serious delinquency remained stable for auto loans, credit cards, and other debt.
Missed federal student loan payments that were not previously reported to credit bureaus between 2020Q2 and 2024Q4 are now appearing in credit reports. Consequently, 7.7% of aggregate student debt was reported 90+ days delinquent in 2025Q1 compared to less than 1% reported in 2024Q4.
https://www.newyorkfed.org/medialibrary/interactives/householdcredit/data/pdf/HHDC_2025Q1
Fed slipping into the background
May 13, 2025
**************
–Weekend US/China tariff progress sent rate futures hurtling lower. Red SOFR pack (SFRM6, U6, Z6, H7) down nearly 17 bps to an avg price of 96.54625, around 3.5%. Green pack -14.375, blue pack -11.125. The two year treasury yield at futures settlement was exactly 4.00%, up 11.9 bps. Ten year yield rose as well, but the curve flattened hard as long liquidation primarily occurred in shorter maturities. Tens rose 8.6 bps to 4.457%. 2/10 posted a new recent low of 45.7 bps, while 5/30 ended at 78.8, down 5.8 bps. The last session of April saw SFRM5/SFRU5 calendar settle at -45 bps (9591.5/9636.5). Yesterday that 3-month calendar settled -26 (9570.5/9696.5). So in less than two weeks U5 is now approaching where M5 was, as forward easing prospects are crushed. On April 30, the peak SOFR contract was SFRU6 at 9706. Now the peak is SFRZ6 at 9657, 50 bps lower. Stocks soared with SPX +3.26% and Nasdaq 100 +4.3%.
–However, in a veiled warning to stocks, the long bond yield continues to press higher. At settlement the 30y yield was 4.889%, up 5.8 bps, ref USM5 settle of 113-16. Post-settle USM5 traded as low as 113-07 and 30y yield at 4.907%, just a short distance from the year’s January high of 4.977%. Kevin Muir, (MacroTourist) notes that on a large yield increase >50 bps, much longer duration bonds will become cheapest-to-deliver into the futures bond contract. That is, the bond future will trade with a higher duration, something to keep in mind if 30s take out 5%.
–CPI today expected +0.3 both headline and Core. On yoy basis, 2.4% with Core 2.8%.
US/China tariff progess leads to possible trend reversals
May 12, 2025
**************
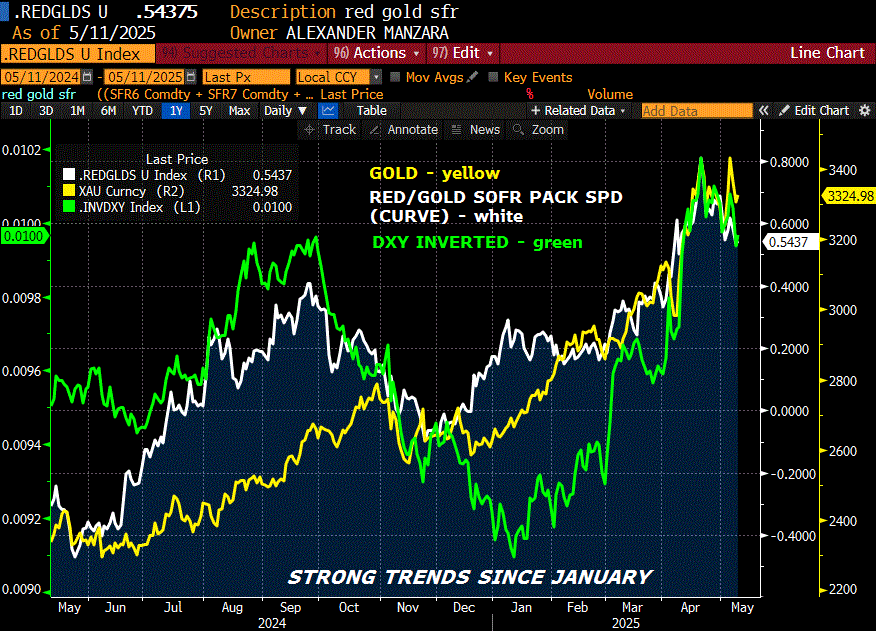
–Agreement between US and China to slash tariffs for 90 days has stocks jumping, dollar firming, gold getting pounded. The attached chart (doesn’t include today) shows strong related trends since January: curve (red/gold sofr spread) steepening, gold running higher, dollar weakening (DXY inverted on chart). Do those trends now have a chance to reverse, or will this just be a pullback?
–SFRU5 settled 9605.5 (3.945%) and Z5 at 9633.0 (3.67%). This morning U5 is 9598 or just above 4% and Z5 is 9622.5. So September has approx one ease priced and December two. The 30y yield is just over 4.85%, up a couple of bps. April’s high was 4.904% and the January high was just under 5% at 4.977%. Trendline off those two levels is 4.88 to 4.89.
–NFBI Small Business Confidence tomorrow morning, followed by CPI.

