
Payroll Friday (when no one is actually working given the 4th holiday)
July 5, 2024
************
–Yields fell Wednesday in the wake of a weak ISM Services number. On Monday ISM Mfg was 48.5 and Wednesday the Service side was 48.8 (expected 52.5). Both are now in contraction territory, with the Service Employment number at just 46.1. Goods inflation has already been moderating, it looks like services might follow suit. Today is the Payroll data, with NFP expected 190k. Get ready for the Unemp Rate to tick over 4%; the last time it was 4.1% was in November of 2021.
–On Wednesday 10’s fell nearly 9 bps to 4.345%. On the SOFR strip greens, blues and golds (3rd, 4th and 5th years forward) were +10 to +10.5 with prices clustered around 9630 or 3.7%. Forward expectations of rates appear quite comfortable around 3.5 to 3.75% for the time being. Of course, the large recent 100 bp wide call spread being accumulated for around 4.5 bps is SFRH5 9675/9775cs which settled Friday at 4.75 ref H5 9545.5 (Lower strike is just 3.25%). This trade would perform best in an environment of rapid easing (seen in 2001 and 2008). Interestingly, there is now also buying of 100 bp wide PUT spreads. On Wednesday, a new buyer of 30k SFRZ5 9562.5/9462.5 ps for 26.75 to 27; settled 24.75 vs Z5 9605. In the Fed’s latest dot-plot the 2025 FF projection was 4.1 or a price of 9590. If the Fed’s right, then this put spd expires worthless. Of course, the put spread works best if the Fed NEVER eases. Just as a point of comparison, the contract in front, SFRU5 settled 9590, and the same strikes ps settled 26.5. So curve roll-down is pretty much like paddling in place over the near term.
–October FF, which provides a decent guidepost for easing expectations at the September FOMC, settled 9487 or 5.13%, up 1.5 on the day. Current EFFR is 5.33% or 9467 so an ease would take it to 5.08% or 9492. Therefore current ease expectations are around 80%.
Happy 4th!
July 3, 2024
************
–Rates eased yesterday as Powell cited progress on inflation but dangled the carrot of confidence just a bit further forward. Almost a parallel shift…tens down 4.3 bps to 4.434%; on the sofr strip reds, greens, blues and golds +4 to +5.5. Slight new high in 5/30 just above +21 bps.
–Buyer of over 30k FV week2 108/109/110 c fly for 1. Open interest up in all strikes, so completely new position. Expires 12-July. The 108c alone were offered at 2 (settled 1.5) and are about 40 bps out-of-the-money. If someone is concerned about a 40 bp move in a week then there’s not a lot of point in having additional legs. In SOFR, a late add of +8k SFRH5 9675/9775cs which settled 4.5 ref 9541.5 and now has about 190k open in both strikes.
–ADP today expected 165k from 152 last. Jobless Claims 235k. S&P Composite PMI. ISM Services 52.6 exp from 53.8. FOMC minutes after futures close/settlements. Settles in rate futures are at 1pm today, though the screen stays open until 5 for anyone who wants to push the market around in thin conditions. We’ll be leaving shortly after settles today. NFP on Friday expected 190k.
–$/yen holding near 162. Precious metals attempting another stab at the upside out of a basing formation. GCQ4 currently 2355, up 21.6 and SIU4 30.385 +72.7.
Then suddenly
July 2, 2024
*************
“How did you go bankrupt?”
Two ways. Gradually, then suddenly.”
–From Hemingway’s The Sun Also Rises
The Hemingway quote is probably overused, but it naturally came to mind when reading Bill Dudley’s piece from last week (6/26):
It’s impossible to know when investors will decide that such risks are too much to bear, as the bond vigilantes famously did in the 1990s. When it happens, it tends to be sudden and brutal. This is the concern that should be paramount.
–The bond market seems to be suddenly reacting to a confluence of negative factors, including crushing supply, higher oil prices, lack of confidence. Since Thursday’s mark at settlement, the 30y yield has surged from 4.426% to 4.641% or 21.5 bps. Selling continued even as yesterday’s ISM Mfg was weak, with the employment sub-index falling to a contractionary 49.3 from 51.1 last. JOLTs today expected 7.955m vs last at 8.059.
–It’s a bear steepener. In contrast with the bond sell-off, SFRZ4 rose only 1.5 bps in yield since Thursday, falling from 9514 to 9512.5. Yesterday the 2y note was up 5.4 bps to 4.77%, while 10s jumped 13.8 to 4.477% and 30’s +14.1 to 4.641%.
–2/10 at new recent high -29.3, up 8.4 on the day. 5/30 new recent high 20.4 up 3.1 on the day. All back SOFR one-year calendars made new recent highs as futures prices were successively weaker down the curve. Net changes: SFRZ4 -2.0 to 9512.5, Z5 -10.5 to 9592.5. Z6 -14.5 to 9614.5 and Z7 -16.5 to 9617.0. SFRU4/U5 is still the most inverted 1-yr calendar, but yesterday it popped 8 bps to -95 (U4 down only 0.5 while U5 fell 8.5).
–The numbers are horrendous but generally glazed over. I was struck though, by an article in BBG highlighting Chicago’s never-ending, and worsening, pension problems, even as portfolios should be soaring:
The net pension liability across the city’s four retirement
funds rose about 5% to $37.2 billion as of Dec. 31, up from
$35.4 billion a year earlier, according to Chicago’s latest
annual financial report.
–Back to the quote at the top of the page. Sudden realizations:
Bond yield too low given profligate gov’t spending? Adjusts all at once.
Biden cognitively impaired? There were *ahem* clues. But the press response…all at once.
European youth sick of the left’s rules? Rapid shift away
One might ask the question whether a quick shift might occur regarding the rosy prospects of AI and big tech. The large cap tech stocks have almost acted like ‘flight-to-quality’ long dated assets, similar (but better) than bonds. Sudden change in growth scenarios?
***************************************************************************
Interesting trade yesterday; synthetic steepener:
+5k 3QU 9612/9562ps vs sell 0QU 9562/9525ps… pay 3.25 to 3.5. The 3QU put spread settled 13.5 and 0QU 11.25.
Spread is synth long U5/U7, futures settles 9579.5 and 9617.5. That spread has jumped from -50 to -38 in two days.
THIS IS NOT A RECOMMENDATION… but it is a reasonable way to express the steepener on the SOFR curve. All options expire 13-Sept, 2024.
Demanding a larger rate premium for long-term bonds
July 1, 2024
************
–Friday’s late bond meltdown is seeing follow-through this morning with a print of 117-06 in USU4 (settled 118-10, late Friday low was 117-14). This, even as PCE prices showed no inflation month/month, with headline and core both 2.6% yoy. The 10 year breakeven (treasury/tip) has been steady at around 2.25% for the past two months (4.34%/2.06%). This morning’s news includes ISM Mfg expected 49.1 from 48.7 last. Powell speaks at the central bank economic forum in Sintra tomorrow.
–5/30 spread ended at the highest level since early April at +17.3 bps, up 4.6 on the day. On the SOFR strip, the red/gold pack spread (2nd to 5th year) rose 5.25 bps to -18.125. (Red pack 9606.25 and golds 9624.375). Every contract from March’26 to March’29 is between 9613.5 and 9633.5…not deviating much from 3.75%. Obviously things can change, but in comparing the long-term inflation expectation embedded in the 10y breakeven to forward rates on the SOFR curve, a real rate of around 1.5% is being projected.
–The most inverted one-year calendar remains the front SFRU4/U5 at -103 (9485/9588). In Fed Funds the front FFQ4/Q5 is -108 (9469.5/9577.5) so the market is currently comfortable with the idea of four eases over that time frame.
–Macron’s early election gambit failed. Political uncertainty growing globally.
It’s not panic if you’re first
June 30, 2024 – Weekly Comment
***********************************
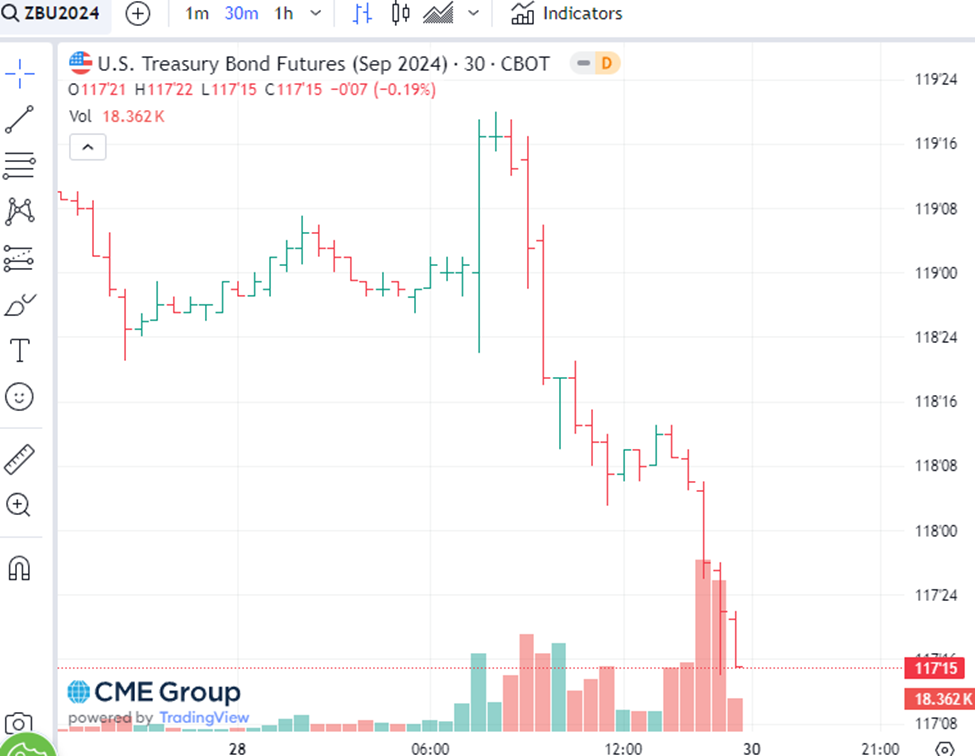
On Friday afternoon, bonds had a “Um… look. We finally beat Medicare” moment. Which is to say, crystallization that out-of-control government spending is not compatible with sub-4.5% bond yields. On Friday’s settlement the 30y was 4.50%; an hour later it was 4.56% as USU fell from 118-10s to 117-14.
Well, maybe that wasn’t it. There were, perhaps, a confluence of factors that sparked selling:
1) The Supreme Court overturned the Chevron decision; will lead to a rollback of regulatory shackles imposed by overly zealous agencies.
2) Odds shifting in favor of another Trump term; “I am the king of debt. I love debt.” Of course, at the end of this 2016 clip he adds, “…but now you’re talking about something that’s very, very fragile and something that has to be handled very, very carefully.” [Something that hasn’t been done recently]
https://www.facebook.com/watch/?v=10153748022289087
Related to increased odds of a Trump win is the chance of a Powell replacement. His official term as Fed Chair ends May 15, 2026.
3) Having sailed through stress tests, banks are upping their dividend payouts. I don’t know if this follows logically, but if a bank is paying out capital, then maybe there’s less with which to buy treasuries? It’s not a great look with respect to income inequality. I think I saw these two snippets on the same BBG website page: Banks pass Fed stress tests and increase dividends…while a nearby headline was ‘Credit Cards Get Stress Test Spotlight With Losses Hitting 40%’. Too-big-to-fail banks are doling out cash to shareholders while consumers struggle to pay the bills.
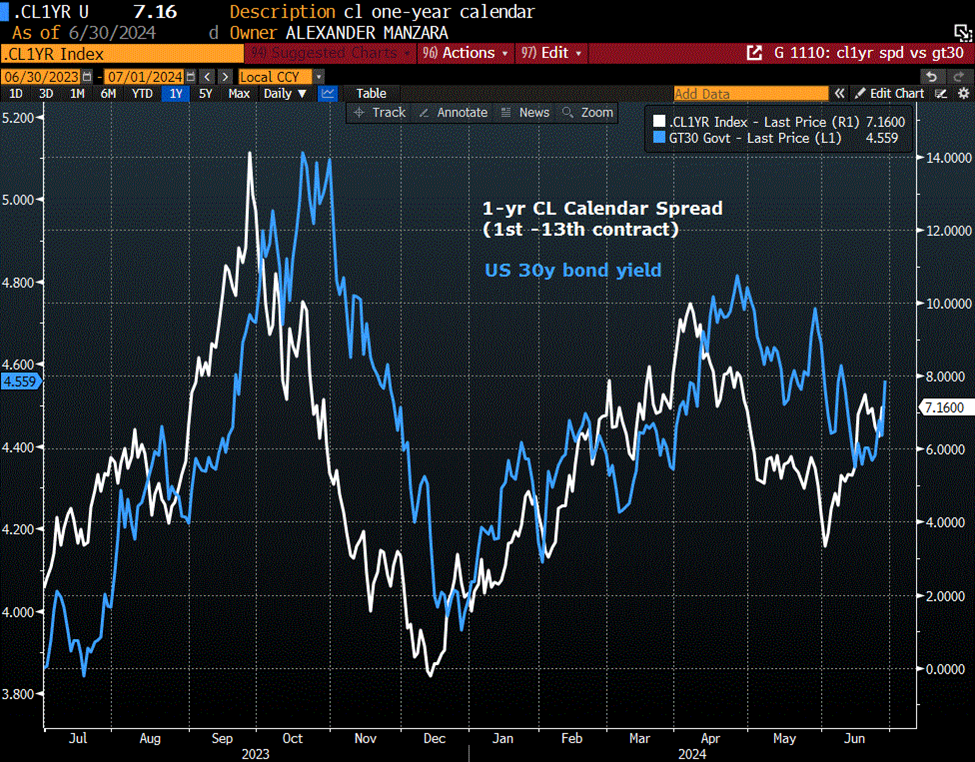
4) August crude oil settled at its highest level in two months at 81.54, and the near one-year calendar, CLQ4/CLQ5 has rallied aggressively, settling Friday at 7.16. Perhaps this move is partially due to increased hostilities and threats between Israel and Lebanon (Hezbollah/Iran). X post example from Saturday: “Multiple sonic booms from Israeli aircraft heard over areas of Southern Lebanon as well as the capital of Beirut.” Chart below overlays CL 1-yr calendar and GT30 yield (oil cal appears to lead).
5) Possible Japanese selling of UST to support the yen.
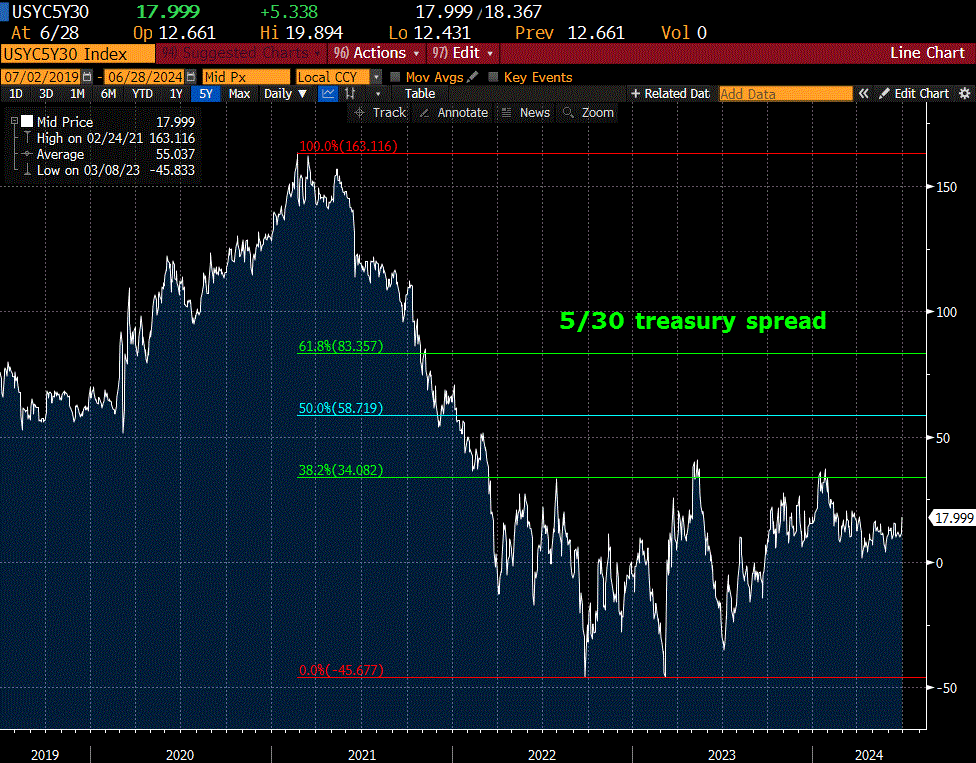
Adjusting for new 2 and 5yr notes, I marked 2/10 up 5.1 bps on the week to -37.7 and 5/30 up 4.2 bps to 17.3. If this latter spread closes above 20 a couple of times, the next test will be upper 30’s. Target should be 60 to 70. 58.5 is the 50% retrace from the 2021 high of 163 to the March 2023 low of -46. The double bottom target from 9/2022 and 3/2023 (both lows around -46) is +68 bps.
Interesting comments from Market Huddle this week featuring Vincent Deluard of StoneX. He suggests selling French OATS and buying Italy BTPs. The compelling aspects: He noted that France and Italy government deficits are nearly equal at 5.5% of GDP. But then he compared PRIMARY debt, saying that Italy could pay its bills if it didn’t have to pay interest…so Italy has a primary surplus, while France does not. The reason is that ten years ago, when spreads had blown up, Italy was issuing long term debt at 7-8% while long-term rates in France were negative. As time rolls forward and Italy is replacing high yield debt with lower rates, its fiscal position improves; it’s the exact opposite for France. Just the passage of time means that Italy becomes a better credit relative to France. Additionally, the trade carries positively. I think that this type of analysis tangentially underlines deterioration in US debt dynamics.
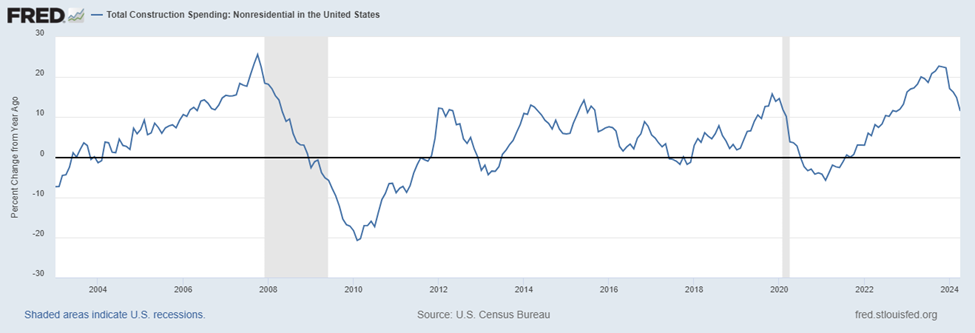
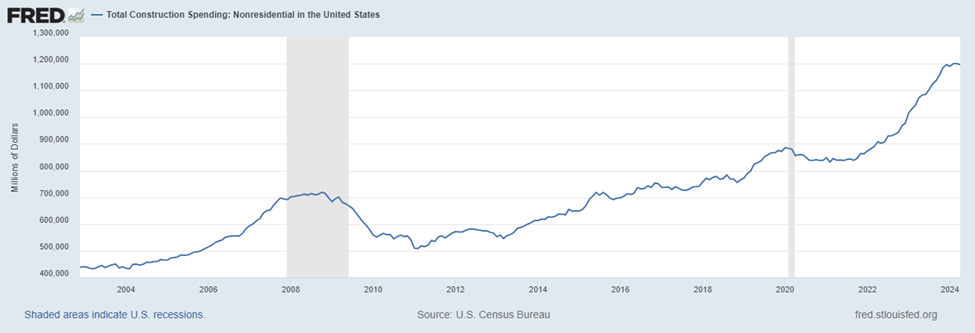
Below are just a couple of charts of non-residential Construction Spending. The CHIPS Act was likely one factor which was instrumental in the steady increase in spending since 2022. However, the growth rate has decidedly turned down (top chart is % yoy change while bottom chart is in dollars).
*************************************************************************
News this week includes ISM Mfg and Services (Monday and Wednesday). Construction Spending Monday. Powell speaks on Tuesday at the Forum on Central Banking in Sintra at 9:30. JOLTs also on Tuesday. ADP and FOMC Minutes on Wednesday.
For some reason, Employment data is released on Friday, after the Thursday 4th of July Holiday. It’s pretty clear that bonds are vulnerable to more downside. If yields can explode higher on a normal Friday afternoon, imagine what can happen on a Payroll Friday when no one is around. Long-end vol ended Friday on a strong note, but I suspect a bid for insurance will be evident on Monday morning.
Powell scheduled for semi-annual testimony on July 9. NOTE: The Semi-annual REPORT is released before the actual testimony.
Remember, it’s not ‘PANIC’ if you’re the first one to sell.
There’s almost no open interest in December Treasury futures and options. Dec treasury options expire on November 22, after the election — but who knows if the outcome will have been decided.
However, midcurve SOFR options are liquid with expirations on 13-Dec 2024 and 14-March 2025. Blue midcurves are correlated to longer dated treasuries. As an example, 3QZ4 9550p settled 6.0 with 14d vs SFRZ7 9633.5. The 9525 strike has a 10 delta and settled 3.75. In comparing nominal levels of atm straddles, 0QZ4 9600^ settled 66.0, 2QZ4 9625^ settled 64 and 3QZ4 9637.5^ settled 59.5. Of course, it makes some sense that nominal straddle levels are somewhat lower at higher strikes (representing lower yields). However, IF the curve really starts to steepen, blue puts will get a double kick from higher vols and higher yields.
| 6/21/2024 | 6/28/2024 | chg | ||
| UST 2Y | 468.3 | 471.6 | 3.3 | |
| UST 5Y | 426.6 | 432.7 | 6.1 | |
| UST 10Y | 425.5 | 433.9 | 8.4 | |
| UST 30Y | 439.7 | 450.0 | 10.3 | |
| GERM 2Y | 278.9 | 283.3 | 4.4 | |
| GERM 10Y | 241.2 | 250.0 | 8.8 | |
| JPN 20Y | 179.7 | 188.5 | 8.8 | |
| CHINA 10Y | 226.0 | 221.0 | -5.0 | |
| SOFR U4/U5 | -108.5 | -103.0 | 5.5 | |
| SOFR U5/U6 | -39.5 | -37.5 | 2.0 | |
| SOFR U6/U7 | -8.0 | -8.0 | 0.0 | |
| EUR | 106.97 | 107.23 | 0.26 | |
| CRUDE (CLQ4) | 80.73 | 81.54 | 0.81 | |
| SPX | 5464.62 | 5460.48 | -4.14 | -0.1% |
| VIX | 13.22 | 12.44 | -0.78 | |
You’re Fired!
June 28, 2024
***************
–You’re Fired… I’m talking, of course, about Masato Kanda, Japan’s currency diplomat, who has presided over yen depreciation, with $/yen breaching 161 today. I only watched a couple of minutes of the US presidential debate, but got a sense of it from this morning’s headlines:
Reuters: Biden’s Wobbly Debate
BBG: Biden’s Disastrous Debate
FT: Democrat’s Panic as Biden Stumbles
WSJ: Dem’s Discuss Replacing Biden
NYT: Biden Struggles
Chgo Trib: …a raspy and sometimes halting Biden tries to confront Trump… [charitable]
So we’ll see who the new guy/person is at the convention, I suppose.
The market tentatively is pricing a Trump win; stocks up, bonds a bit weaker. But oil is at a new recent high this morning with CLQ4 82.43.
–Yesterday was quiet. Ten year yield slipped back a few bps to 4.286%. Early buys of 15k SFRZ4 9525/9550/9600/9700c condor 2.5 and 9525/9575/9600/9700cc for 5.75…looks like they’re rolling long 9600/9700 c sprds into tighter, closer to the money call spreads. Indeed, open interest confirms that, with a drop of 37k on 9600c and 44k in 9700c, and of course, a jump of 29k in the 9525c. SFRZ4 settled 9514, so the new lower strike is just 11 otm, but with the Fed Fund Effective at 5.33% or 9467, the 9525 strike needs two to three eases to be in play. Of course, Powell could be out, replaced with a financial wizard like Sam Bankman Fried who can get us back to 1% funding rates…
–Capital Goods Orders non Def, ex-Air was -0.6%; weak.
Today brings PCE prices expected 0.0 with Core 0.1% on month/month.
Y/y expected 2.6 and 2.6%.
We need an intervention. On many levels
June 27, 2024
***************
–Solid 5y auction but yields rose on the day, with tens +7.8 bps to 4.316%. New Home Sales were weak at just 619k, vs expected 640k. Today brings final Q1 GDP, expected 1.4, Durables -0.1, Jobless Claims 236k and the 7y auction. All capped by the spectacle of the only presidential ‘debate’.
–Yen continues to probe new lows, ignoring repeated calls for an intervention. Micron’s (MU) earnings call disappointed, with the stock dropping 5.8% after hours.
–Everyone gets a trophy, which is to say that all the banks passed the Fed’s stress test. From the Fed:
This year’s hypothetical scenario is broadly comparable to last year’s scenario. It includes a severe global recession with a 40 percent decline in commercial real estate prices, a substantial increase in office vacancies, and a 36 percent decline in house prices. The unemployment rate rises nearly 6-1/2 percentage points to a peak of 10 percent, and economic output declines commensurately.
…the annual bank stress test showed that while large banks would endure greater losses than last year’s test, they are well positioned to weather a severe recession and stay above minimum capital requirements.
–And what if equities drop 50%? Game over for some banks without extraordinary gymnastics by the Fed (Simone Biles type stuff) except that the extraordinary has now become ordinary. It’s called moral hazard.
–Another 15k SFRH5 9675/9775cs bought for 4.5, total now about 140k. Settled 4.25 vs 9540. New seller of 7k SFRZ4 9512.5 straddle from 37.5 to 37. Settled 37 vs 9512. SFRM4 is still trading, and settled 9464.5 yesterday. Therefore, SFRZ4 is about 47 bps higher, roughly two eases. Z4 9537.5c settled 11.25, so straddle sale versus long call fully caps upside in the unlikely event that the gods decide to put the Fed’s stress parameters to the fire test.
SOFR strip was -8.5 to -9 from SFRU’25 to SFRU’28.
Not stressing about banks….stressing about direct US war
June 26, 2024
**************
–Early Tuesday Fed’s Bowman said inflation risks means she doesn’t see an ease in 2024; shifted forward to 2025. 2/10 squeaked out a new ytd low at -49.6, but not much change in SOFR calendars. SFRU4/U5 remains the most inverted at -107, actually up 0.5 on the day (9485.5/9592.5). Net changes on both the SOFR strip and treasuries were miniscule. SOFR from -0.5 in fronts to +1.0 in blues. Ten-yr yield down less than 1 bp at 4.238%.
–Today’s news includes New Home Sales, expected 633k from 634k last. Peak in 2005 was 1.389m. Low in 2011 270k, then a steady rise until the covid spike of a little over a million. Currently back to 2019 levels (but population is larger). 5y auction. Fed releases bank stress test results. KRE, the regional bank etf, ended at 46.93, down 1.4% on the day. This year, the low has been defined by three lows at or just under 46; a close below would be significant.
–Another 30k bought in SFRH5 9675/9775cs for 4.75, bring total to about 125k. Another interesting, though much smaller trade, is a new buyer of 5k SFRH5 9600c vs 0QH5 9700c for 0.5 (buying H5). Settles: 15.75 vs 9546.5 in H5 and 15.25 vs 9619.5 in H6. Similar goal as the plain call spread…works best with rapid, front-loaded easing. SFRH5/H6 currently -73 while strikes are -100, obviously a parallel upward shift in the two contracts would put H5 calls in the money faster. Unexpected, rapid ease would cause the futures spread to move more positive.
–Q1 GDP released tomorrow, final estimate, expected 1.4%. With a price deflator of 3% it’s nominal growth of 4.4%, about 100 bps lower than Fed Funds. Restrictive…except that Q2 GDP as estimated by the Atlanta Fed is 3.0%, so nominal above FFs. If Fed funds represent the first hurdle of capitalism, then a nominal growth rate above financing costs still pushes the cart forward.
–The Biden admin said the US “…may lift restrictions on the deployment of US military contractors in Ukraine so that they can maintain and repair weapons systems provided by Washington.” Another incremental step in removing ‘proxy’ from US war. This, after Russia blamed the US directly for Crimea attacks over the weekend which used US controlled missiles. Dangerous escalation.
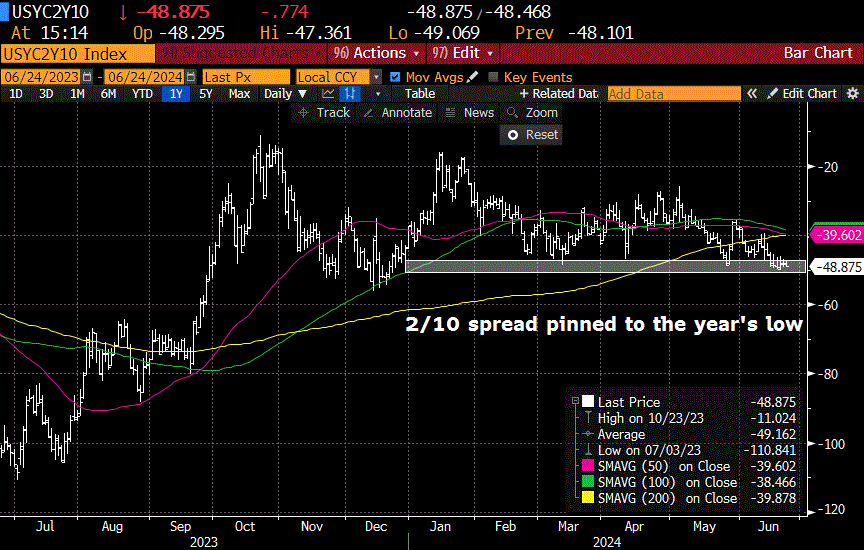
2/10 spread at low of this calendar year
June 25, 2024
**************
–Relatively quiet day in rate futures. Ten year yield fell 1 bp to 4.246%. In front of today’s 2-yr auction, 2/10 treasury spread edged to a new low of -48.6. It was not a particularly large move, it’s simply that 2/10 is slowly grinding to new lows for this calendar year, though the entire ytd range is only -16.5 to -49.
–Huge drop in bitcoin Monday. Late futures price (july) of 59950, down 4860. USD vs Asian currencies remains strong (chart attached with Yen, Indonesian Rupiah, Indian Rupee; USD making highs against all).

–Continued buying of SFRH5 9675/9775cs for 4.75 with another 17k bought yesterday, bringing the total to 100k. Settled unch’d at 4.5 ref 9547.
–Today’s news includes Philly Fed Services which was -0.6 last. Also Consumer Confidence expected 100 from 102…remains near the lowest levels since Covid. Two year auction.
–Yesterday I checked July expiry on SFRZ4 9500/9487.5 put spd ref 9515.5; pit market was 1.0/2.0. BBG symbol is UZON4 Comdty OMON, symbol on CME-direct 1YZ. These options expire 12-July into SFRZ4. Shortly after I checked this market, there was a buyer of 5k 9700c for 0.25.
Notable events occurring pre-expiration:
Biden/Trump debate
PCE prices on Friday
NFP July 5
Powell semi-ann testimony 7/9
CPI 7/11
After the weekend attack in Crimea at Sevastopol which for which Russia blames the US (US weapons used in the strike), odds of unexpected military escalation are growing.
More debt
June 24, 2024
****************
–Relatively quiet session Friday with yields little changed. Tens ended up half a bp at 4.255%; the TYU4 contract pinned the strike with a settle exactly at 110-16. There were a couple of large trades targeting lower yields: New buyer 80k SFRH5 9675/9775cs for 4.75, settled 4.5 ref 9546.5 (unch’d). New (adding) buyer of 50k TYQ4 111.5c, settled 27 vs 110-16.
–PCE prices released on Friday, with yoy expected 2.6% from 2.7 last and Core expected 2.6% from 2.8 last. Today’s news includes Dallas Fed Mfg expected -15 from -19.4. Daly speaks on the economy at 2:00pm. 2/5/7 yr auctions beginning tomorrow. Biden/Trump debate on Thursday evening. First round of French vote on June 30.
–Apart from the voracious borrowing appetite of the Federal Gov’t, Credit Bubble Bulletin excerpted this clip from BBG:
June 20 – Bloomberg (Joe Mysak): “The municipal bond market this week soaked up a record 27th deal of $1 billion or more, with overall borrowing accelerating at a torrid pace. Debt sales are being driven in part by a decline in borrowing costs over the past few weeks… Top-rated borrowers can borrow money for 10 years at about 2.80%… That’s down from 3.09% at the end of May. The previous annual record for so-called mega-deals was in 2020, when 26 were sold, totaling $46.49 billion… Through Wednesday, 27 muni megadeals totaling $42.96 billion have been sold. So far this year, states and localities have sold $221.4 billion in long-term debt, 42.8% ahead of last year’s pace.”
–Clearly, $221 billion doesn’t seem like much any more, but corporate borrowing is also accelerating. Debt time bomb.

