
Higher for longer; new high SFRZ4/Z5
April 17, 2024
***************
–Powell… “The recent data have clearly not given us greater confidence and instead indicate that it is likely to take longer than expected to achieve that confidence” that inflation will return to 2%.
–The higher for longer stance was clearly reflected by the SFRZ4/SFRZ5 calendar spread which traded huge volume and settled at a new recent high of -57.5, up 6 bps on the day. SFRZ4 was unchanged at 9509 and Z5 fell 6 to 9566.5. This morning’s prelims show that open interest rose 20k in Z4 but a whopping 133k in Z5, to 809k. There was also an article dated Monday on Politico (linked below) titled, ‘Trump trade advisors plot dollar devaluation’. (thanks BP). ($ deval probably would result in higher US long rates). Note: $/yen 154.60. And the Korean Won has also depreciated quickly from 1330 in the beginning of March to 1400 yesterday. Stronger USD should be deflationary for the US, but Core Services have been the problem, not goods. The Asian currency crisis was in 1997/98…
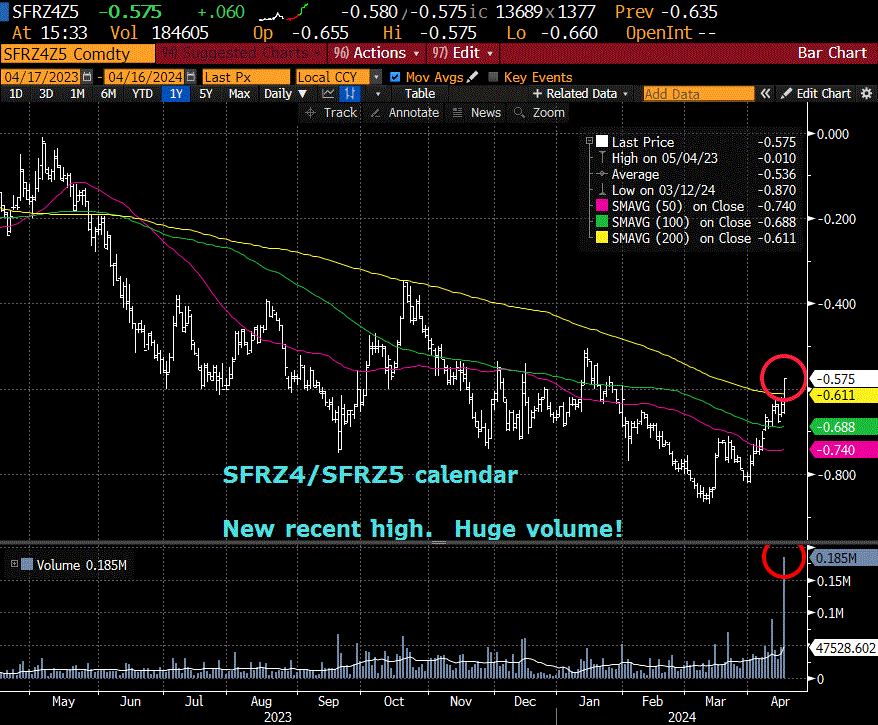
–Yields yesterday rose, except for SFRZ4! Two year +3 bps to 4.964%. Tens +2.7 to 4.657%. 20-yr auction today. On the SOFR curve, unsurprisingly SFRZ5 was the weakest contract, -6.0. SFRM5 to SFRM8 down 3 to 5.5 apart from Z5 (-6).
–Flows to hedge against a plunge in risk assets aren’t particularly prevalent, though VIX perked up over 19. Yesterday there was more (new) SOFR call spread buying, adding 30k to Z4 9600/9700cs for 6.75 (settled 6.5) and 15k SFRZ5 9750/9850cs for 8.25 (settled 8.0 ref 9566.5). Yesterday I mentioned a buy of 40k Z4 9700/9800cs; that was incorrect and was probably an intercompany transfer, OI didn’t change. Note that even with a move to new high yields, treasury vol eased; there were some chunky TY put sales. Indication that yield surge has abated for now. Fear of higher rates subsiding.
SUMMARY
–Huge Z4/Z5 buys. Settle +6 at -57.5
Z5 75/85cs 8.25 for 15k
Z4 60/70cs 6.75 for 30k
TODAY: 20y auction, Beige Book, TIC data
https://www.politico.com/news/2024/04/15/devaluing-dollar-trump-trade-war-00152009
Below is chart of Korean Won and Indonesian Rupiah

Easing pace will be slow, unless FORCED
April 16, 2024
***************
–Stronger than expected Retail Sales helped push yields to new recent highs. On a monthly basis +0.7 vs +0.4 expected, with ex-auto and gas +1.0%.
Two year yield was only up 5.5 bps to 4.935 but tens jumped 13.3 to 4.63% and thirties rose 13.9 to 4.74%. Bear steepener. On the SOFR curve reds were -8.5, while greens, blues and golds were -11.5 to -14.5. The 2-yr note that was issued in January was just over 5% late yesterday; probably a great place to park funds for safety. If not already in gold.
–Buyer of 60k SFRZ4 9850/9900cs for 0.625 synthetic. Settled 1.25 and 0.75 ref 9509.0. Also a buyer of 40k SFRZ4 9700/9800vs which settled 4.75/2.0. Israel/Iran conflict risks significant acceleration.
–Stocks closed at new recent lows. SPX -1.2% and Nasdaq Comp -1.8%. ESM4 late 5099, having erased all of March gains (ESM4 high settle on 3/28 was 5308.5). NQM4 settled 17876.25, down 303, and is also below the entire March range. Sell in May and go away has started a little early this year. Because of climate change, of course.
–Treasuries aren’t really benefiting from a safety bid as of yet. China Q1 GDP was +5.3% but the yuan remains under pressure, and $/yen prints 154.50 this morning (new low for yen). If the BOJ supports the yen it sells US assets. Therefore, the risk trades are in the front end, exemplified by SFRZ4 call spread buys. Once again, I think the Fed’s last SEP, which raised the forward estimates for the FF target in 2025 and 2026, was an important signal which has helped tighten financial conditions internationally.
–Housing Starts and Industrial Production today. Powell speaks at 1:15.
1:15 p.m.
Discussion — Chair Jerome H. Powell
Moderated Discussion with Tiff Macklem, Governor of the Bank of Canada
At the Washington Forum on the Canadian Economy, Washington, D.C.
Kon-Tiki
April 14, 2024 -Weekly comment
***************
When I was a kid I read Kon-Tiki by Thor Heyerdahl. It’s an epic tale documenting his 1947 voyage to the Polynesian Islands from South America on a raft. The adventure took 101 days covering 4300 miles.
From Wikipedia:
Heyerdahl believed that people from South America could have reached Polynesia during pre-Columbian times. His aim in mounting the Kon-Tiki expedition was to show, by using only the materials and technologies available to those people at the time, that there were no technical reasons to prevent them from having done so. Although the expedition carried some modern equipment, such as a radio, watches, charts, sextant, and metal knives, Heyerdahl argued they were incidental to the purpose of proving that the raft itself could make the journey.
Fabulous book for a kid. I recall one of the problems was that when they were building the prototype, they found that the grass ropes that lashed the raft together would immediately begin to fray from the friction of the logs and motion of the seas. However, they discovered that by using native balsa wood, the ropes would actually cut into the logs, creating channels which prevented the fraying. People solve problems.

The reason I brought this book up is I recall another particular passage. The expedition was approaching the end of the voyage. The seas were wild and the raft was nearing an island with rocky outcroppings. The crew of six were exhausted. They had a meal, and my specific recollection is that Thor decided not to clean his dish and utensils that day, as they probably were destined to crash on the rocks which would tear the 45-foot raft into pieces.
I searched for the specific passage from Kon-Tiki. But internet inquiries now are all about the colonization of indigenous peoples, rather than the spectacular theory and resulting adventure. It’s tedious. I quit.
The weather is beautiful this weekend in the Chicago area. Trees and flowers are beginning to blossom. ‘Nature’s first green is gold’. People are out walking their dogs, kids are playing. I was about to recap the week and organize some thoughts for next week, but instead, I’m having friends over and going to enjoy the backyard as the world hurtles into thoughtless conflagration. Not going to worry about washing the dishes today.
Just one other quick thought. Kevin Muir had a guest on last week’s Market Huddle named Paulo Macro. Though he was mostly raised in the US, his family is from Brazil, and he related an amusing story about when he was a kid in Brazil during hyperinflation. He said that prices were going up something like 2% EVERY day. So, when people went to the store, there was an employee with a price tag gun who would start at the front and just raise prices of everything, every day, working his way down the aisles. The shoppers would, of course, race in front of the guy to buy the items where the prices hadn’t yet been increased. To me, it’s the extreme degree of the ‘inflation expectations’ spectrum. Some people might be thinking about input supplies, etc. but the end consumer just has a mindset that these prices are going to be higher tomorrow, and they act accordingly. The latest US inflation data highlighted a 22% increase in the price of auto insurance since last year. Are expectations here truly anchored?
Untethered expectations can create an almost automatic and unthinking strategy. And that’s where the world seems to be in the geopolitical race toward conflict.
‘Then leaf subsides to leaf/ So Eden sank to grief’
********************************************
Below chart is attributed to BofA

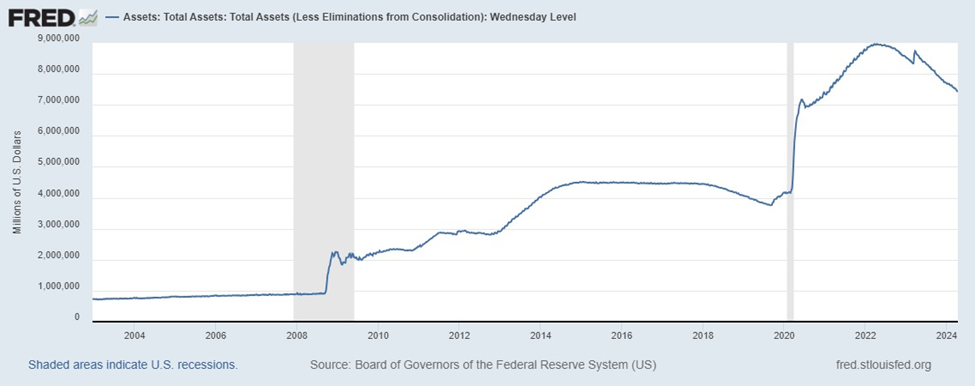
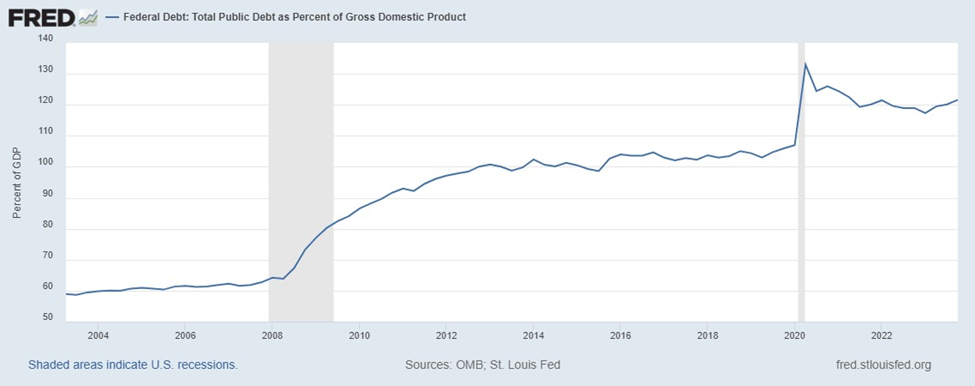
The next two charts are from St Louis Fed’s FRED website. The top is the Fed’s balance sheet, and the bottom is the US Debt as a percent of GDP. In the period after the GFC, both went up and then leveled off. The authorities were, more-or-less, buying prosperity. Then covid hit. The Fed’s trying to dial its initial response down, but the Federal Gov’t isn’t. War is not likely to help.
| 4/5/2024 | 4/12/2024 | chg | ||
| UST 2Y | 473.0 | 488.0 | 15.0 | |
| UST 5Y | 436.5 | 453.1 | 16.6 | |
| UST 10Y | 437.3 | 449.7 | 12.4 | |
| UST 30Y | 452.8 | 460.1 | 7.3 | |
| GERM 2Y | 287.5 | 285.6 | -1.9 | |
| GERM 10Y | 239.9 | 235.9 | -4.0 | |
| JPN 20Y | 153.1 | 162.6 | 9.5 | |
| CHINA 10Y | 229.1 | 228.4 | -0.7 | |
| SOFR M4/M5 | -93.5 | -76.0 | 17.5 | |
| SOFR M5/M6 | -40.5 | -42.5 | -2.0 | |
| SOFR M6/M7 | -7.0 | -14.0 | -7.0 | |
| EUR | 108.40 | 106.44 | -1.96 | |
| CRUDE (CLM4) | 86.10 | 85.08 | -1.02 | |
| SPX | 5204.34 | 5123.41 | -80.93 | -1.6% |
| VIX | 16.03 | 17.31 | 1.28 | |
Real yields are high
April 12, 2024
***************
–Relief rally in stocks but treasuries continued to trade soft late Thursday on auction distribution. USM4 settled 115-08 at 3:00pm but traded 114-31 just before the electronic close. PPI was slightly lower than expected, though anyone that cares to look can see that CLM4 has moved from 71 to 85 since the start of the year. BBG cited the Fed in a story noting that credit card delinquencies are at a record high, with 3.5% being at least 30 days late as of Q4. Can’t pay the juice.
–At the time of settlement rates were little changed though the curve steepened. Red SOFR contracts essentially unch’d but golds -2.625. Two-year down 1 bp to 4.95% while thirties were up 3 bps at 4.657%. Ten year inflation indexed note at 2.165%, a new high for the year. The high last October was 2.53%
–A headline from FT this morning: ‘Value of China’s exports falls sharply on sliding prices’. USDCNY 7.2373 and $/yen remains over 153 as both currencies continue to weaken, portending deflationary exports.
–JPM, Citi, WFC and Blackrock report today. Retail Sales and Tax Payment day on Monday.
A second inflation wave?
April 11, 2024
***************
–CPI lived up to the hype, sparking huge market moves on a ‘hot’ print. CPI m/m 0.4 versus expected 0.3, yoy 3.5 vs 3.4 expected. Core 3.8 vs 3.7 expected. The largest net change across rate futures was SFRM5 which plunged 30 to 9544.5. Two year yield surged 21.5 to 4.96%, while the ten year rose 18.4 to 4.548% after a poorly received auction. SPX ended down 1%. CLM4 was +0.95 late at 85.41.
–New highs in near SOFR calendars as prospects for near-term easing were squashed. The most inverted one-year calendars are still the fronts but June’4/June’5 and U4/U5 are now almost equal. M4/M5 settled -72.5, up 18 on the day (9472/9544.5) and U4/U5 settled -73 up 9 (9487/9560). SFRJ4 (April) reflects no ease, settling at 9466.75. SFRZ4 ended at 9507, just 40 bps above April, about 1.5 eases priced into year end. Last Thursday this spread was -69. FFQ4 was 9492 on Tuesday, now 9479 so about 50/50 being priced for an ease by the July 31 FOMC.
–$/yen was near 153 at the end of the day and is now just above that level, which adds pressure on the Chinese yuan. Summers helpfully repeated that the next Fed move could be a hike.
–The administration’s impulse to hand out gifts to counter bad news is now being confronted by bond vigilantes, with the thirty year auction today (yield was 4.63% at futures settle). They will blame Powell, but perhaps now the Fed can just sit back and let tighter financial conditions tamp down on forward inflation.
–The block buyer of 75k SFRZ4 at 9532 on Tuesday was clearly caught wrong-footed. However, the buyer of 40k SFRU4 9462.5p for 2.25 gained 4.5 at settle (6.75s). The Monday buys of otm treasury puts also did nicely, for example, a buyer of 50k FVM4 102.5p for 1.5 to 2; late quote was 5 mid-mkt ref 105-08. Vol jumped with TYM4 vol marked at 6.8 from 6.0
–News today includes PPI, expected 0.3 m/m with yoy 2.2 from 1.6 last and Core 2.3 from 2.0 last. Jobless Claims expected 215k
We all see the prices
April 10, 2024
***************
–CPI expected +0.3% on the month, with yoy 3.4 from 3.2 last and Core 3.7 from 3.8. ZeroHedge this morning leads with an article about scandal within the BLS regarding technical discussions with ‘super-user’ economists about specific calculations relating to CPI. The intimation is that some market participants have ‘non-public’ info. My working assumption is that someone always has better information and probably has the final number. His name is Clarence Beeks.
–There was a block buyer of 75k SFRZ4 yesterday at 9532.0 (settled 9533.0). New position, as open interest rose 55k. That guy have it? Maybe, But maybe the fact that Yellen is warning about another wave of cheap Chinese deflation has something to do with the SOFR bid, as the yuan is slowly depreciating. Maybe the Fitch downgrade of China’s outlook has something to do with it. $/yen also pinned near 152.
–There was also a buyer of 24k FFN4 at 9481 or 5.19%, Settled 9482.0. Current Fed Effective is 5.33% or 9467. There’s an FOMC May 1, and FFK4 settled 9468, so the market is assigning very little chance of a cut at that meeting. Then there is a meeting June 12. That’s the one FFN is pricing. Assuming May is a no-go, then FFN at 9482 indicates 60% chance of an ease. There’s another FOMC on July 31. FFQ4 settled 9492.0 or 5.08%, exactly 25 bps lower than the current EFFR.
–Yesterday also featured the softest Small Business Confidence (NFIB ) number since 2012 at 88.5. Inflation was cited as a top concern. In many ways, inflation has helped the largest US companies and their stocks. Smaller businesses, not so much. It seems as if today’s CPI is expected to come in soft, but I’m not sure that’s a sustainable positive for SPX from here.
–Ten year auction today, yesterday’s 3-yr was poorly received with a 2 bp tail, 4.548% actual vs 4.528 at cut-off. Tens ended at 4.364%, down 6 bps on the day. FOMC minutes this afternoon.
OTM treasury puts popular
April 9, 2024
*************
–Once again new highs in near SOFR spreads. On March 27, SFRM4/M5 settled -111. Yesterday -88 (9481.5/9569.5), so that’s 23 bps in 7 sessions, mostly due to the drop of 30 bps in SFRM5 from 9599.5 to 69.5. The front M4/M5 spread is still the most inverted, but there’s less variation, for example, SFRM5/M6 is -38.5 or just 49.5 higher than the front; on March 27 it was -40. The adjustment in price has been in reds forward. My personal view is that the upward shift in Fed dots in 2025 and 2026 at the last FOMC was more important than the market gives credit for; higher rates a couple of years into the future affect cash flows on everything. (Perhaps clues in tomorrow’s FOMC minutes)
–The other theme yesterday was new buying in treasury puts:
FVM4 106p covered bought 40k; settled 41 vs 106-01, OI +32k, straddle settled 1’20
Others were otm buys:
FVM4 102.5p 1.5 to 2 paid 50k, 2 settle, OI +46k
FVM4 102.75p 2.5 paid 10k, 2.5 settle, OI +9.6k
FVM4 103.0p 3.0 paid 10k, 3 settle OI +8k
TYM4 104p, 3.0 paid 10k, 3 settle, OI +9.7k
TYM4 103p 2.0 paid 20k, 2 settled OI +20k
CPI tomorrow along with the 10yr auction. Three-year auction today, 30s on Thursday. These put buys are longer dated and wingier, they’re not just short term protection. They’re for Jamie Dimon big risks type stuff.
It’s a hardball world, son. We’ve gotta try to keep our heads until this peace craze blows over.
–Full Metal Jacket
Auction concession or something more?
April 8, 2024
*************
–Friday’s higher than expected payrolls at 303k with an unemployment rate of only 3.8% contributed to a jump in US rates. Tens rose 5.8 bps to 4.373%. The SOFR curve flattened with reds leading the way lower. Red pack (M5, U5, Z5, H6 avg) ended -11 bps at 9597.0. close to 4%. Greens were -7.875 at 9621 (rounded) and blues -6 at 9622.5.
–Near one-year calendars made new highs with SFRM4/M5 at -93.5 (9483.5/9577.0) +6.5 on the day, and U4/U5 at -86.0 (9507.5/9593.5) +4.5 on the day. This was a spread Bill Gross had highlighted as a long a couple of months ago when it was sub -100.
–Treasuries have continued lower this morning with TYM down half a point at 109-05 and USM down a full point at 116-17. Ten year yield now 4.45%, well through the 50% level from last October’s high of 4.99% to December’s low of 3.795%. Next yield resistance should be the 61.8 level of 4.53% which should equate to price support around 108-18 to 108-20 in TYM4. Note to self, total eclipse is bearish.
–Dollar/yen near 152 (151.90 last) pinned at recent highs and near the high print in 2022 of 151.95. It’s the highest level since the early 1990’s.
–3, 10 and 30 year auctions this week. CPI is on Wednesday, expected 3.4% yoy from 3.2% last with Core 3.7% from 3.8% last. FOMC minutes also on Wednesday.
A flight into ‘Quality’ assets
April 7, 2024 -Weekly Comment
*************
The wave of crystallization rolled ahead. He was seeing two worlds, simultaneously. On the intellectual side, the square side, he saw now that Quality was a cleavage term. What every intellectual analyst looks for. You take your analytic knife, put the point directly on the term Quality and just tap, not hard, gently, and the whole world splits, cleaves, right in two…hip and square, classic and romantic, technological and humanistic…and the split is clean. There’s no mess. No slop. No little items that could be one way or the other. Not just a skilled break but a very lucky break. Sometimes the best analysts, working with the most obvious lines of cleavage, can tap and get nothing but a pile of trash. And yet here was Quality; a tiny, almost unnoticeable fault line; a line of illogic in our concept of the universe; and you tapped it, and the whole universe came apart, so neatly it was almost unbelievable. He wished Kant were alive. Kant would have appreciated it. That master diamond cutter. He would see. Hold Quality undefined. That was the secret.
Phædrus wrote, with some beginning awareness that he was involved in a strange kind of intellectual suicide, “Squareness may be succinctly and yet thoroughly defined as an inability to see quality before it’s been intellectually defined, that is, before it gets all chopped up into words — .We have proved that quality, though undefined, exists. Its existence can be seen empirically in the classroom, and can be demonstrated logically by showing that a world without it cannot exist as we know it. What remains to be seen, the thing to be analyzed, is not quality, but those peculiar habits of thought called `squareness’ that sometimes prevent us from seeing it.”
Thus did he seek to turn the attack. The subject for analysis, the patient on the table, was no longer Quality, but analysis itself. Quality was healthy and in good shape. Analysis, however, seemed to have something wrong with it that prevented it from seeing the obvious.
–Zen and the Art of Motorcycle Maintenance
*************************************************
It’s not that US bonds are of unsound quality. The coupons will be distributed and principal (if not the principles) honored. It’s the future purchasing power of the US dollar that seems to have something wrong with it.
SPX fell 1% last week. The thirty-year bond yield rose 18.5 bps to 4.528%.
Gold was up 4.4% to a new record high of $2329.75. Quality asset.
Gold is not the patient. The sickness lies within the entirety of the government’s debt addiction.
The chart below shows SPX/XAU and SPX/BCOM. With all the AI hype, SPX priced in gold is not taking out the high from the end of 2021. Even against the commodity index there has been a slight turn down.

The chart on the next page is the 10-yr yield. The current yield is about 4.38%, essentially at the halfway point of the October 2023 high of 4.99% to the Dec 2023 low of 3.79%. It’s the same with the 30-yr bond, the halfway point is 4.53% and we’re right there. The large drop in yields in the last two months of last year is partially attributed to the Treasury’s Quarterly Refund Announcement on Nov 1, which increased t-bill issuance and slowed the pace of longer dated treasuries. The low yield of that move was in late December, shortly after Powell indicated a “dovish pivot” at the Dec 14 FOMC. Since then, yields have stair-stepped higher. This week features inflation data, treasury auctions and FOMC minutes:
Tuesday – 3-yr auction ($58b)
Wednesday – CPI expected 3.4% yoy from 3.2 last, but Core 3.7% from 3.8. FOMC minutes. 10-yr ($30b)
Thursday – PPI expected 2.2% yoy with Core 2.3%, both higher than last. 30-yr auction ($22b)
The next Quarterly Refunding Announcement is May 1.
Recall that in October, several Fed officials suggested that the rise in long-term yields was tightening financial conditions, obviating the need for the Fed to overtly raise the FF target. For example, here’s an excerpt from Lorie Logan on October 9, 2023:
Financial conditions have tightened notably in recent months. But the reasons for the tightening matter. If long-term interest rates remain elevated because of higher term premiums, there may be less need to raise the fed funds rate. However, to the extent that strength in the economy is behind the increase in long-term interest rates, the FOMC may need to do more.
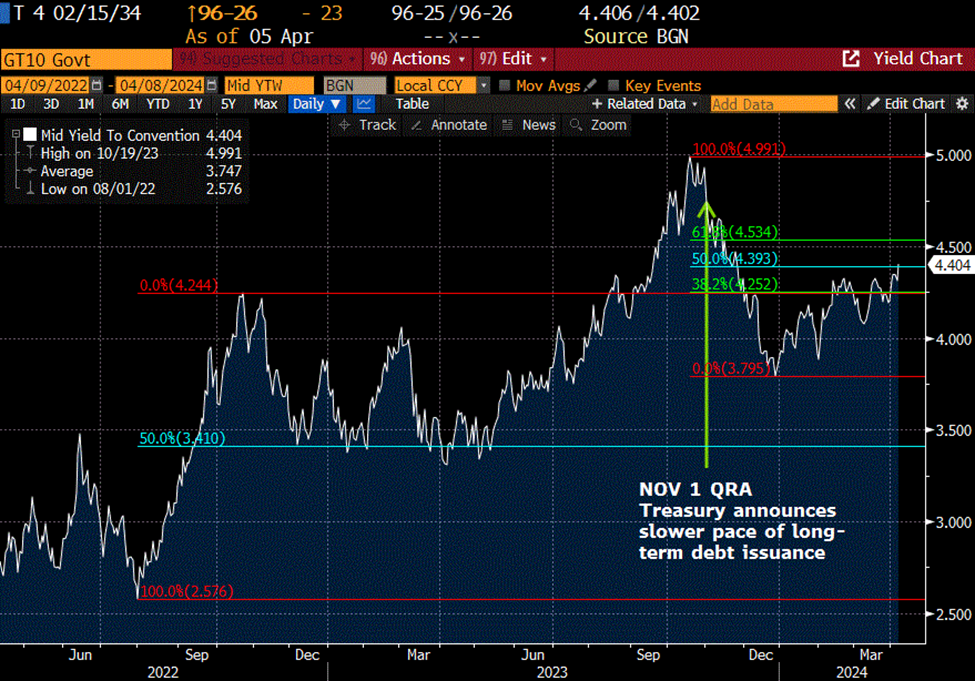
Expect to hear a lot about an increase in ‘term premium’ in the coming days. Perhaps this year’s rise in longer maturity yields can be partially explained by the Dec Fed pivot; a shift away from the single-minded goal of slaying inflation. Of course, the Federal Gov’t is completely focused on re-election. Might the QRA factor into that? The cancellation of SPR purchases to replace previous sales is a case in point, as is the administration’s displeasure in Ukrainian attacks on Russian oil infrastructure. As a final note, WTI closed at a new high for the year (CLM4 up 3.68 on the week to 86.10). Also, I track the rolling one-year calendar 2nd to 14th CL spread. The high was made last year at the end of September, with the front contract at $12.20/bbl premium to deferred. That period, incidentally corresponded with rising bond yields and an increase in ‘term premium’. Currently, this spread is represented by CLM4/CLM5 which has rallied to a new high this year, settling 9.69 on Friday, up from around 4.00 at the start of February.
I’ll admit, it’s not exactly a sharp analytical knife. But I’ll take a lucky break whenever I can! As an old friend used to say: Sell bonds. Wear diamonds.
| 3/28/2024 | 4/5/2024 | chg | ||
| UST 2Y | 462.2 | 473.0 | 10.8 | |
| UST 5Y | 421.1 | 436.5 | 15.4 | |
| UST 10Y | 419.8 | 437.3 | 17.5 | |
| UST 30Y | 434.3 | 452.8 | 18.5 | |
| GERM 2Y | 284.8 | 287.5 | 2.7 | |
| GERM 10Y | 229.8 | 239.9 | 10.1 | |
| JPN 20Y | 145.2 | 153.1 | 7.9 | |
| CHINA 10Y | 230.6 | 229.1 | -1.5 | |
| SOFR M4/M5 | -107.0 | -93.5 | 13.5 | |
| SOFR M5/M6 | -44.0 | -40.5 | 3.5 | |
| SOFR M6/M7 | -5.5 | -7.0 | -1.5 | |
| EUR | 107.89 | 108.40 | 0.51 | |
| CRUDE (CLM4) | 82.42 | 86.10 | 3.68 | |
| SPX | 5254.35 | 5204.34 | -50.01 | -1.0% |
| VIX | 13.01 | 16.03 | 3.02 | |
I love this story below. Now here’s INNOVATION!
Payrolls – all prices will be met
April 5, 2024
*************
–Payrolls today expected 200k with the unemployment rate at 3.9% (vs 275 and 3.9 last). The last time the UE rate was 4.0 was in January 2022, it has been in the 3’s since then with a low of 3.4. Consumer Credit at end of day, was +$19.49 billion for Jan.
–Yesterday afternoon stocks tumbled, with SPX ending -1.2% and NasComp -1.4%. Kashkari warned the Fed may not ease at all this year; Israel put forces on high-alert in expectation of Iranian response, Blinken said Ukraine will become a member of NATO. Oh, and bird-flu is making the rounds. Markets have become a lot more uncertain, with VIX jumping to 16.6.
–Rate futures experienced some flight-to-quality buying, though tens ended down only 3.8 bps to 4.315%. Every SOFR contract from Sept’24 to Sept’27 was up 3.5 to 4.5. Treasury auctions 3s, 10s and 30s next week. You need ‘quality’? The treasury is here to help. In size. By the way, these auctions settle on 15-April which is also tax day, a temporary withdrawal of private liquidity bestowed upon the Solons of the federal gov’t for benevolent distribution to weapons manufacturers.

