
Risk Management
October 19, 2025 – Weekly Comment
***************************************
I have to start this one with a disclaimer: What follows are ONLY my personal views. Nothing below should be attributed to RJ O’Brien or StoneX in any way.
“When a manager with a reputation for brilliance tackles a business with a reputation for bad economics, it’s the reputation of the business that remains intact.” -Warren Buffet

In 1983, when they filmed Trading Places, the CME floor was supposed to be the venue. However, the exchange was concerned the movie would besmirch its reputation and denied access. Ultimately it was filmed in NY.
On the trading floor, members wore badges with identifying acronyms (like VAL for Billy Ray Valentine). In the old bond room was a tom-boyish girl, who had an Ivy League education but was a bit ditzy, sandy blond hair, plain clothes, Converse gym shoes. Her badge was AFS. Her nickname: Awfully F-cking Stupid.
In 1993, I had been at a CME members meeting, before the exchange went public, and the Chairman at the time, Jack Sandner, a trim, fiery former amateur boxer was making a speech, “The CME is not in the TRADING business” he shouted. “It’s in the RISK MANAGEMENT business.” That line always stuck with me. We’re not a bunch of gamblers. We’re a critical block in the financial architecture that allows prudent risk transfer from hedgers to speculators.
It’s now obvious to everyone that lines have blurred. But I hadn’t even realized this: The CME partnered with FanDuel to provide a platform for betting markets. For the last couple of days, I have struggled with whether I should say this or not. That’s AFS.
Here’s the CME press release from August:
https://www.cmegroup.com/media-room/press-releases/2025/8/20/cme_group_and_fanduelpartnertodevelopinnovativeeventcontractspla.html
CME Group, the world’s leading derivatives marketplace, and FanDuel, America’s premier online gaming company, part of Flutter Entertainment, today announced a groundbreaking alliance that will launch new products and expand access to financial markets for millions of FanDuel customers in the United States.
This innovative partnership will build on CME Group’s long track record of developing regulated, transparent markets, and FanDuel’s vast customer reach. Together, the companies will develop new fully funded, event-based contracts with defined risk. Customers will be able to express their views multiple times a day on a wide range of markets with simple “yes” or “no” positions for as little as $1. [CME will create a new non-clearing FCM]
Things change. Quickly. Few will likely recall “socks and stocks”. That’s when Sears Roebuck (oh, you don’t remember that?) bought Dean Witter and put kiosks in department stores to sell financial services. From a 1984 article in ‘The Oklahoman’ “Some in the financial industry joke about customers buying stocks and socks and real estate from the same store where they buy underwear and tools.” But the results of a recent survey reveal what may be their true feelings. According to a survey from March in the American Banker, CEOs of big banks said they think Sears will be their major competitor in 1990.”
https://www.oklahoman.com/story/news/1984/05/26/socks-and-stocks-sears-financial-services-catch-on/62802189007/
This is from a BBG story about Robinhood
https://blinks.bloomberg.com/news/stories/T4A708GPQQLX
Like a lot of things Robinhood has done, this latest move [into gambling markets] has been widely derided for what seems like pretty obvious reasons. “The key is to help people understand the difference between gambling, trading and investing—some companies try to blur the lines,” says Andy Reed, head of investing behavior research at Vanguard. “We’re not trying to present investing as something that’s fun or gives you instant gratification. It’s not about dopamine, it’s about serotonin.”
Tenev sees it differently: There’s no reason for the brokerage app—like a grocery store that sells both carrots and Ding Dongs, ground beef and Impossible burgers—not to offer memecoins alongside individual retirement accounts, or to promote both sports bets and financial planning services.
Speaking of risk management, Zion’s and Western Alliance Bank apparently made loans where they thought they would be paid off first from borrower MOM CA Investco, LLC (a CA real estate firm). They weren’t. They discovered they were much lower down in the jenga credit tower (made famous in The Big Short). Is the whole thing about to collapse? I have no idea, but probably not, after all these institutions are overseen by the Fed, with its sophisticated risk management tools. Which, after running the numbers through the model, always ends up with “Hey Jamie, you’re going to have to buy another bank.” The worry isn’t banks. From the IMF, “…nonbanks now hold around half of the world’s financial assets. In the United States and the euro area, many banks now have nonbank exposures that exceed their Tier 1 capital—a crucial cushion that allows a bank to absorb losses and remain stable in times of crisis.”
Staff at the Fed and Treasury are obviously well aware of risks. They are already working on what to do if there IS a collapse. Me? I’m trying to figure out if I should bet a couple of dollars on the Bears game. Not that it’s going to make me rich. It’s not as if I’m the Governor of IL JB Pritzker, who reported $10 million in income of which $1.4m was gambling winnings. Hey JB, ever see that Twilight Zone episode where the low level mobster dies and finds himself in a beautifully appointed casino surrounded by beautiful women, where he can gamble all day? He NEVER loses. Finally he is getting so bored that he says to his jovial and attentive guide, this is awful, I never lose, no matter what. This isn’t heaven!
“Heaven? Whatever gave you the idea you were in Heaven, Mr. Valentine? This is the other place!“
It’s almost like Hillary’s ‘no-lose’ cattle trading in 1978/79. Um, did it ever occur to you that they were letting you win? No, of course not, you studied cattle statistics.
By the time she closed her trading account ten months later, she had racked up $99,541 in profits, a spectacular 10,000 per cent return on her initial investment of $1,000. [She actually opened the account with $25k]
https://www.nationalreview.com/2016/06/hillary-clinton-cattle-futures-windfall/
Look, I might be all wrong about this whole thing. Maybe AFS really was smart.
OTHER THOUGHTS/ TRADES
Powell had previously said the Fed should move from a regime of ‘abundant’ reserves to ‘ample’. Last week he suggested the Fed would stop balance sheet run-off in a couple of months. The spread between one-month Fed Fund contracts and one-month SOFR is an indication of liquidity tightening at the margin, the risk is that reserves fall below ‘ample’. FFV5 settled 9591.25, SERV5 9583.25, spread of -8. FFX5 9615.0, SERX5 9607.5, spread of -7.5. (spread in lower panel)

On Thursday, the ten year yield fell below 4% to end at 3.975 vs TYZ5 113-24. However, rates popped back up slightly on Friday to 4.007 vs TYZ5 113-15. 4% has been the lower yield bound this year, but I think we’re going to see 3.79 to 3.80 this week. In 2024 the low was 3.62. Current DV01 on TY contract is $67.90, so a move to 3.79 would imply ~114-30 to 115-00 given a parallel shift.
In ten year options, long call strikes TYZ5 113, 113.5 and 114 have been rolled to higher strikes, TYZ5 115 and 115.5 and on Friday, partially into Feb (TYG) 116c. From Friday, +30k TYG6 116c 28, vs -17250 TYZ5 115c at 16 and -1300 TYZ 113-17. TYH6 settled 113-12 and TYG 116c 27 (22d). TYG options expire on 23-Jan. The FOMC is 28-Jan; I would note that TY pushed to a new high just prior to the Sept FOMC.
CPI is released on Friday, expected 0.4% with Core 0.3. YOY 3.1 from 2.9 with Core 3.1 from 3.1. Crude oil is near the low of the year with CLZ5 57.15 settle. The 10y breakeven, treasury minus tip, is at a new recent low 227.6, having been as high as 244 in August. Excluding Liberation Day turmoil, where the low was 205 bps, the range since 2023 has been 215 to 248. The market is not concerned about inflation even though the consumer is. Perhaps Friday’s data will change that.
| 10/10/2025 | 10/17/2025 | chg | ||
| UST 2Y | 351.8 | 346.2 | -5.6 | |
| UST 5Y | 364.2 | 359.2 | -5.0 | |
| UST 10Y | 404.8 | 400.7 | -4.1 | |
| UST 30Y | 463.0 | 460.2 | -2.8 | |
| GERM 2Y | 195.7 | 190.6 | -5.1 | |
| GERM 10Y | 264.3 | 258.0 | -6.3 | |
| JPN 20Y | 270.8 | 262.9 | -7.9 | |
| CHINA 10Y | 184.7 | 182.3 | -2.4 | |
| SOFR Z5/Z6 | -64.0 | -68.0 | -4.0 | |
| SOFR Z6/Z7 | 11.0 | 12.0 | 1.0 | |
| SOFR Z7/Z8 | 18.5 | 20.0 | 1.5 | |
| EUR | 116.06 | 116.63 | 0.57 | |
| CRUDE (CLZ5) | 58.48 | 57.15 | -1.33 | |
| SPX | 6552.51 | 6664.01 | 111.50 | 1.7% |
| VIX | 21.66 | 20.78 | -0.88 | |
| MOVE | 81.65 | 78.62 | -3.03 |
Leverage works BOTH ways
October 17, 2025
******************
–I had mentioned the other day that the first red SOFR contract rallied over 200 bps during the regional banking crisis of March 2023 (which ultimately culminated with the SVB bankruptcy). It was an extremely volatile period, (chart attached) but the key point was that the high was over 9700. Same type of price action for Liberation Day, first red went from 9650 to 9725. Currently first red is 9715 (SFRZ5), but FF are 25 lower than they were in April. Suddenly the buys of otm red calls (0QZ 9800c for 1.0) look pretty good.

–Headlines seem to be focused on regional bank stress again, (Zions, Western Alliance) because apparently, charlatan borrowers have pledged the same collateral for more than one loan. And… it’s gone. It’s worth mention that crypto is also under a cloud. I don’t watch much in this space but bitcoin (as of this early Friday note) is through last Saturday’s low, which is 17% off the month’s (all-time) high. Last price <105k. MSTR also at a new low, down 38% from the July high. Diamond hands, meet Dimon warning.
–Yields fell yesterday, with 10s down 7 bps to 3.975. This morning 3.955. I’m looking for 3.79. The late September covered call buyer, 113, 113.5, 114c in total size about 375k appears to be rolling longs into the 115 and 115.5 strikes. Yesterday -42k TYZ 114/115.5cs at 24 covered 113-21, 26d. TYZ 115.5c rose 39k in open interest to 82k, settled 17. I roughly calculate 115.5 strike to be 3.80% or slightly lower.
–Yesterday Optiver made a note of TY skew / demand for calls. Currently, with TYZ 113-29+, the 112.5p is 14/15 (-21d) while the 115.5c is 19/20 (+24d)
–It’s not all driven by financial markets (though a meltdown will surely trickle through to consumer spending… like a tsunami). The clip below was on Dave Lutz’ note from Jones Trading:
Shut out of full-time work, many jobseekers appear to be doing the next best thing and hunting for a holiday season gig, according to research from the job search platform Indeed. Searches for seasonal jobs were up 27% at the end of September compared to a year ago, and surged 50% from 2023, according to Indeed. The outsize demand from jobseekers compares with only a modest 2.7% pickup in seasonal job postings from employers, suggesting even temporary holiday roles will be hard to come by.
What’s in YOUR private credit book?
October 16, 2025
******************
–It’s sort of like a Samuel L Jackson Capital One credit card ad: “What’s in YOUR wallet?” Except that it’s Jamie Dimon asking “What’s in YOUR private credit portfolio?” And his answer is, when you see one cockroach, there’s usually more. From Dimon: “These are very smart players: they know what they’re doing, they’ve been around a long time. But they’re not all very smart. And we don’t even know the standards of other banks [that] are underwriting to some of these entities. And I would suspect that some of those won’t be as good as you think.”
–US yields pushed a bit higher yesterday with tens +2.5 bps to 4.044%. Implied vol smothered. The big covered call buyer’s last synthetic straddle buys at the end of September were 113 strike for 1’54 (bought 113c for 46 vs 112-19). Yesterday TYZ5 113^ settled 1’27 vs 113-075. On Friday TYZ 113^ was 1’41. Almost certainly there have been some adjustments, for example a seller yesterday (roll) of TYZ 113.5/115c 1×2, settled 12. The theme, in my opinion, is to bring markets back to a more normal and stable state (lower vol, ten year yield hugging the Fed Effective rate, stocks shaking off weakness and trying to press VIX down) but the underlying foundation is riddled with fault lines. Bitcoin is the latest tremblor.
–Ten year treasury vs TIP breakeven continues to slip, notching a new recent low 230 bps. CLZ5 settled 57.84 its lowest close since May. (Time to fill up the SPR). Focus now shifting to Venezuela and Maduro. Bessent comments yesterday indicate serious issues continue with China. A Doomberg piece this morning warns that China’s rare earth clampdown is likely to reverberate through supply chains; a bigger deal than is being generally acknowledged.
–Several Fed spreakers today. Miran continues to argue for lower rates, and certainly the market is signaling acceptance. I believe Philly Fed Mfg will be released, expected 10 from 23.2.
Pre-set path… with a kicker
October 15, 2025
******************
–Yields continue to grind lower. TYZ5 settled 113-13, +8/32, with cash 10s 4.019%. USZ5 settled 118-09, +11/32 with 30s marked at 4.621%. SOFR contracts +0.5 to +1.5, with SFRZ6 and SFRH7 tied for peak contract at 9705 or 2.95%. Trade of the day was a new buyer of >100k 0QZ5 9800c (initial +80k on block for 1, then some slightly higher). These expire 12-Dec 2025, SFRZ6 underlying.
–November FF settled 9614.5 or 3.855%. Current Fed Eff is 4.10, so FFX is 24.5 lower in yield, fully pricing a 1/4% cut at the October FOMC. FFF6 settled 9640 or 3.60%, exactly 50 bps below current Fed Effective (good size buyer yesterday at 9640.5). Central banks like to say they’re not on a “pre-set path”, but the short-rate futures markets have clearly set the next two meetings for 25 bp cuts.
–However, the FF target isn’t the only Fed tool, as Powell said yesterday. From the speech:
Our long-stated plan is to stop balance sheet runoff when reserves are somewhat above the level we judge consistent with ample reserve conditions. We may approach that point in coming months, and we are closely monitoring a wide range of indicators to inform this decision.
The end of balance sheet run-off reflects slightly easier stance; perhaps the gold market is taking that factor into account as it soars to new record highs. Currently 4223/oz, up 59.60 as of early morning Wednesday.
Also from the speech:
Research and experience tell us that asset purchases affect the economy through expectations regarding the future size and duration of our balance sheet.
–Stopping asset sales will have a similar effect, of course. The market is priced for FF cuts already; the end of balance sheet run-off will be an additonal ease.
–I had mentioned 0QZ 9800c in my weekend note. Currently 0QZ5 9750c are 3.75 (ref 9705), so an immediate 50 bps surge in SFRZ6 would see the 9800c go from 1 to at least 3.5 and likely ~ 5.5 given a vol kick. I had also mentioned 0QX5 9737.5c for 3.0, those settled 2.5 yesterday. Both the SVB bankruptcy in March/Apr 2023 and the yen-carry turmoil of Aug 2024 saw rallies > 50 bps in the first red in short order. Something comes out of left field almost EVERY day now. A little insurance isn’t a bad idea.
and….Bears win
October 14, 2025
******************
–Yesterday’s highlight was the Monday Night Football fabulous rendition of the National Anthem by Generald Wilson!
The National Anthem will be performed by retired Navy Petty Officer First Class Generald Wilson, a premier National anthem soloist known for his powerful renditions at major sporting events across the country—including previous Commanders games.
–Market action was confined to a quiet back and fill, with implied vol in rates marked significantly lower after Friday’s pop. TYZ5 113^ settled 1’41 Friday vs 113-04+, but down at 1’34 yesterday vs 113-050. Precious metals remain on fire with GCZ5 4133.0 and SIZ5 50.43 (yesterday settles; higher this morning).
–Today Powell speaks on the Economic Outlook at 12:20, though renewed tensions in China/US trade relations may overshadow Powell’s summary. Bowman (morning) and Waller (afternoon) also speaking on discussion panels. Stock futures starting off on the back foot with ESZ 6638.0, down around 56
–NFIB small business optimism just released at 98.8 from 100.8. (Still above long term average). This survey was from September, prior to the shutdown. “Supply chain and inflation issues stood out as a key problem in the report.”
Gold and Silver indicate stress is still present
October 13, 2025
*******************
–I guess it was inevitable that Trump would backtrack from initial China threats with SPX -2.7% on Friday. While stock futures have had a nice bounce this morning, with ESZ5 up around 90 (6682 last), red SOFR contracts are only down 1 bp from Friday’s gain of 9.5 to 10. Peak contract is SFRH7, now printing 9700 from 9701s Friday. Bitcoin has recovered Saturday’s plunge, but is only back around Friday’s low ~115k. The star is Silver, with SIZ5 49.90 up 2.63 and cash over $51/oz. Gold is also at new highs, with GCZ5 4099, +98.60 on the day.
–Risk controls and margins likely to tighten up. Powell speaks tomorrow at 12:20 on the economic outlook (a bit cloudy?) with Waller on a discussion panel in the afternoon at 3:25 re: Payments (just tack it on to the back-end using PIK). CPI has now been scheduled for October 24, one week from Friday. While stocks are open today, the cash bond market is closed.
–Perhaps worth noting is that the 10y breakeven, (treasury – tip) ended at a slight new recent low of 232 bps Friday. The inflation outlook appears more dependent on the direction of stocks rather than tariffs. The high of the year was in February at 247 bps, and the Liberation month of April saw the low print of 217. Friday’s level is right in the middle.
Rare Leverage
October 12, 2025
******************
The camera pans over a crowded investment conference cocktail party. A sonorous voice asks in near disbelief, “How could all of these sophisticated investors not have seen the warning signs of over-leverage and fraud?”
The broad answer of course, is that some DO see it and actively participate. Really sophisticated ‘investors’ get the info just a little bit before everyone else. It helps. For example, there are reports of heavy short sales of both bitcoin and ether right before Trump’s ‘100% tariffs on China’ announcement on Friday with covers right after the tweet (reported $190m profit). Thanks for link NS.
https://www.youtube.com/watch?v=5fTv9ThJg6U
Thunder clouds are now rolling in threatening forced exits and diminished liquidity. Obviously apparent in crypto, where Bitcoin traded to a record high 126k on Monday, but plunged to around 103k on Saturday, a move of nearly 20% in a week (15% on Friday alone). Ethereum tanked over 25% in the same time period but is still above its 200 dma. (As of this note on Sunday Bitcoin is just above its 200 dma of around 107k). The other related aspect is one of due diligence concerning private credit/equity deals. First Brands bankruptcy highlights lax standards, which will now likely tighten up like a barbed cilice.
Two weeks ago (Ghost of Burns) I mentioned the weak price performance of private equity companies KKR, APO, BX, OWL. All had miserable action on Friday with OWL at the lowest close of the year (below the lowest Liberation Day close) and APO nearing that low (closed 118.22, 4/4 low was 108.68, intervening high in July was 156). I also noted that XBT/XAU (bitcoin gold cross, then at 29) looked vulnerable to a lower break, which of course occurred on Friday. Now at 27.8, it looks like it might test the April low just above 25. (when XBT was 79880 and XAU was 3176).
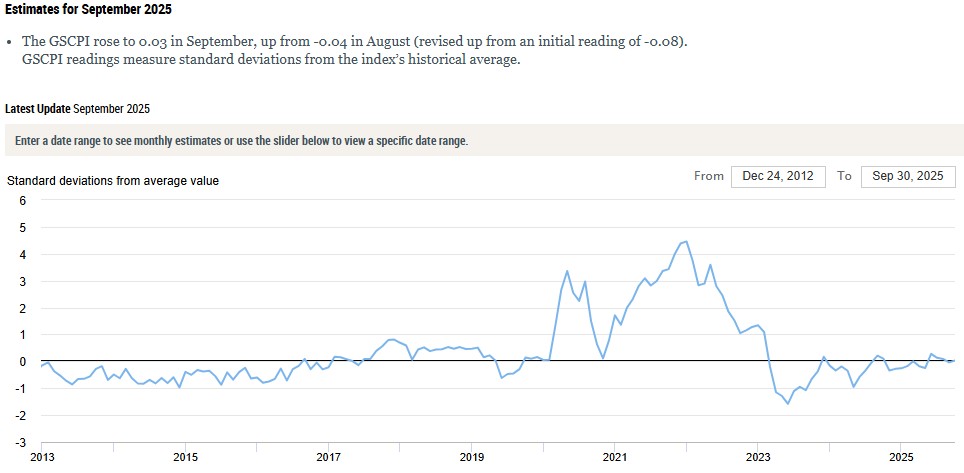
The government shutdown is causing angst over the release of timely economic data, but what is currently reflected in market prices is probably all we need to know. For example, China’s new restrictions on rare earths should have an immediate effect on supply chain pressures, but it probably won’t show up in the NY Fed’s Global Supply Chain Pressure Index for some time. Anduril founder Palmer Luckey is forcefully arguing for the US to move away from China supply chains (which is likely inflationary at the margin). https://www.youtube.com/watch?v=Z369Ug6b83w
Interesting quote: “Most of our best talent…contrast this to the Cold War, is no longer working on nat’l security problems, but is working on things like advertising optimization, on new apps, on tools of entertainment rather than tools of deterrence. And I’ve seen that reversing.”
Here’s NY Fed Supply Chain Pressure. It surged during Covid. How will a suspension of rare earths impact supply chains in general?
https://www.newyorkfed.org/research/policy/gscpi#/interactive
In my opinion it won’t be easy to reverse Friday’s damage in stocks due to continuing erosion of the administration’s credibility. Even with softened rhetoric, consumer and business confidence is likely to fray further. So, I think the Liberation Day sell-off (sans the subsequent rally) is the proper template. SPX low print in April was 4835 (start of the year was around 4745). Friday was 6552.
The Liberation low print in SPX was ~21% below February’s high, and about 16% below the late March high (immediately prior to the April 2 Liberation Day tariff announcement). From Thursday’s close of 6735, 16% lower is 5657 and 21% is 5321. The 100 dma is 6327 and the 200 day is 6050. At the very least I would say the 200dma should be tested, which is about 7.5% lower than Friday’s close.
The peak SOFR futures contract is SFRH7 at 9701. High tick in that contract just prior to the September 17 ease was 9719.5. SFRH7 is now the second red. In the Liberation turmoil, the second red traded as high as 9728, though the high settle was 9693.5. The highest settle for the second red on April 30 (SFRU6 at that time) was 9706. The high in the red pack in April was 9702. Given the 25 bp ease in September and expected 25 bp cut in October, 9750 should be an easy target for reds if stocks continue to break.
The 10y yield ended Friday at 4.048%, about 4 bps below EFFR and 10 below the SOFR rate. On April 4, low in 2y was 3.655, now 3.518. Low in 5y was 3.71 now 3.642. Low in 10s 3.997, now 4.048. 30s 4.411, now 4.63. So shorter maturities are below April’s lows, but longer maturities are not…yet. If 10s move below 4% then 3.79 should be a target. That was the initial low related to the yen-carry trade in August 2024. At the time, the front TY contract traded over 115 (TYZ5 settled 113-045 on Friday).
Themes are 1) tighter credit 2) national insularity that can feed into higher inflation, and 3) a shift to guns rather than butter. The question now is whether the Fed will choose to focus on incipient price pressures (Logan) or on liquidity and wealth effect concerns (Miran)
Powell speaks on Tuesday on the Economic Outlook. Miran on Wednesday. Beige Book Wednesday afternoon. Fed’s communication blackout on October 18.
OTHER THOUGHTS/ TRADES
Both VIX and MOVE perked up last week. MOVE put in low of 69.5 on October 3 but ended Friday 81.65. It’s been in a downtrend since the April spike up to 140. Excluding any adjustments which may have occurred, the large covered call buyer in TYZ5 is getting close to flat after suffering the vol grind lower.
I have included a summary of Dec TY covered calls that had been accumulated in the latter half of September. Again, this is not necessarily inclusive, and doesn’t assume any adjustments. However, the changes from last Friday, October 3, to October 10 settles are somewhat enlightening. Shown at bottom
Summary of TYZ covered call buys (not sure this is a complete list, added the 113c 9/30):
Monday 9/22:
+50k TYZ5 114.0c covered 112-275, 31d price 33
+50k TYZ5 114.0c covered 112-255, 29d price 32
+25k TYZ5 114.0c covered 112-240, 28d price 31
Tuesday 9/23:
+50k TYZ5 114.0c covered 112-250, 29d price 31
Thursday 9/25:
+50k TYZ5 113.5c covered 112-215, 35d price 38
+50k TYZ5 113.5c covered 112-210, 35d price 38
+20k TYZ5 113.5c covered 112-090, 18d (only) price 32
Tuesday 9/30
+50k TYZ5 113.0c covered 112-190, 42d price 46
+25k TYZ5 113.0c covered 112-220, 45d, price 49
Friday’s settles, Oct 10, 2025: (Dec options expire 21-Nov)
TYZ5 113-045
TYZ5 113.0c 57
TYZ5 113.5c 43
TYZ5 114.0c 32
| 10/3/2025 | 10/10/2025 | chg | ||
| UST 2Y | 357.0 | 351.8 | -5.2 | |
| UST 5Y | 370.6 | 364.2 | -6.4 | |
| UST 10Y | 411.7 | 404.8 | -6.9 | |
| UST 30Y | 471.2 | 463.0 | -8.2 | |
| GERM 2Y | 201.5 | 195.7 | -5.8 | |
| GERM 10Y | 269.7 | 264.3 | -5.4 | |
| JPN 20Y | 261.1 | 270.8 | 9.7 | |
| CHINA 10Y | 185.9 | 184.7 | -1.2 | |
| SOFR Z5/Z6 | -62.0 | -64.0 | -2.0 | |
| SOFR Z6/Z7 | 11.0 | 11.0 | 0.0 | |
| SOFR Z7/Z8 | 19.0 | 18.5 | -0.5 | |
| EUR | 117.42 | 116.06 | -1.36 | |
| CRUDE (CLZ5) | 60.53 | 58.48 | -2.05 | |
| SPX | 6715.79 | 6552.51 | -163.28 | -2.4% |
| VIX | 16.65 | 21.66 | 5.01 | |
| MOVE | 69.53 | 81.65 | 12.12 | |
Cui Bono
October 10, 2025
******************
“To the extent we have been successful, it is because we concentrated on identifying one-foot hurdles that we could step over rather than because we acquired any ability to clear seven-footers.” -Warren Buffet
I don’t really think Argentina is a one-foot hurdle, but that didn’t stop the US Treasury from directly buying pesos to save Milei, or rather to save the Dead Cow, (Vaca Muerta LNG/shale development). More on that in another note…
–SOFR and treasury futures trading remains fairly quiet, though the Fed Effective setting moving up another 1 bp to 4.10% set off a flurry of FF vs one-month SOFR spreads. For example, FFX5 settle 9613.5, -0.5 while 1m SOFR SERX5 settled unch at 9607.5, spread of 6 (FF volume 100k and SERX 70k). Not much change following the 30y auction. Tens up 1.7 bps to 4.144%. SOFR contracts unch’d to -2.0 out to blues.
–Below doesn’t really have a direct impact on markets, but is still interesting:
First, an X-post by @AllVentured
‘We are quite literally taxing poor Americans via their power bill to subsidize AI cat videos’
Not so fast, Friskers. There’s a great story on ZH about community opposition to data centers bringing people of different views together. The below concerns a proposed Google project near Indianapolis:
But in the weeks leading up to that vote, Franklin Township neighbors began to organize. Neighbors of all backgrounds—farmers, homeowners, parents, retirees—organized across political lines. They put up yard signs, and launched a Facebook group that quickly drew hundreds of members and launched a resident petition that gathered 7,600+ signatures. They wrote and called their council representatives, and word spread through churches, schools, and community meetings. By the time of the final hearing, the chamber was packed wall to wall with residents, standing shoulder to shoulder in opposition. They had packed City Hall so tightly that the chamber was standing-room only.
District Councilor, Michael-Paul Hart told reporters for More Perfect Union who were present on the night of the vote, “In my six years on the council, I’ve never seen all the rooms filled to the max with people waiting in the lobby. I’m overjoyed by the amount of community support that came out for this.” One local resident said: “This was do or die. We came prepared to fight with everything we have against this data center.” “I’ve been hoping that something would bring us together,” said a community organizer. “And it looks like data centers are.”
https://www.zerohedge.com/energy/americas-growing-pushback-against-data-centers
From a local news outlet:
People against the project cite not enough jobs, power and water strain and no tax benefit.
Could the Fed Cut 50 in October?
October 9, 2025
*****************
–Not much worth noting in rate futures trading, aside from continued accumulation of call spreads based on SFRZ5 trading above 9650 (or higher). For example, more buying of SFRZ5 9650/9662.5cs for 1.25. SFRZ5 9650c have whopping 878k in open interest relative to 1.5m in Z5 futures, and settled 2.25 with 0.19d, ref Z5 9632s. In the September cycle, the (initial) call spread which was bought in huge size was SFRU5 9612.5/9625; ultimately went out worthless.
–Ten year yield nearly unch’d at 4.127%. Twos rose 1.4 to 3.582%. Thirty year auction today, closed at 4.722% yesterday.
–What could put the Z5 9650 calls in play? There are three weeks until the next FOMC on Oct 29. Nov Fed Funds at 9614 currently price high odds of a 25 bp cut at that meeting. (FFX5 rate is 3.86 vs current EFFR of 4.09, a difference of 23 bps). Anything on the three-week horizon that could shift expectations to 50? Nothing in yesterday’s release of the minutes is suggestive of a large risk. If anything, concerns about inflation have picked up.
Perhaps a stretched gov’t shutdown could be the spark. Is the First Brands bankruptcy a possible catalyst? Probably not, but it seems to be getting larger by the day. ZH reports “…an investigation into the car parts group’s off-balance sheet financing is examining whether collateral underpinning its financing was pledged “more than once” and “commingled” between lenders.” DOH!
This sort of circular financing and vendor finance is currently a hot topic as it relates to the AI boom. But nothing can stop that, right? Except maybe China shutting down rare earth exports, which they seem to be in the process of doing right now. From CNBC: “China has tightened export controls on rare earths and related technologies while barring its citizens from participating in unauthorized mining overseas, adding fresh strains to a sector central to its geopolitical leverage.”
Dude, rather than a $50 billion investment can you get your hands on some dysprosium and terbium?
On a more mundane topic, Redfin reports that “Roughly 56,000 U.S. home-purchase agreements were canceled in August, equal to 15.1% of homes that went under contract that month. That’s up from 14.3% a year earlier and marks the highest August rate in records dating back to 2017.”
https://www.redfin.com/news/home-purchase-cancellations-august-2025
–It’s all dependent on stocks holding up. Vincent Deluard, Director of Macro Strategy at StoneX mentioned in a presentation yesterday that capital gains are about 10% of individual tax receipts for the gov’t, a significant source of income. A loss of capital gains income can set the entire process in reverse.
Gold on the Ceiling
October 8, 2025
*****************
–Yields eased yesterday with 10s down 3.5 bps to 4.125% in front of today’s auction. Fed Effective has been 4.09% so 10s are hugging that level. SOFRRATE 4.15% on Monday. 30 year auction tomorrow. 30y yield fell 3.3 bps to 4.724%. Treasury vol probing new lows. Peak SOFR contract SFRH7 was +3.0 at 9595.
–Even though SOFR futures were drifting a bit lower early yesterday, there were additional call spread buyers on SFRZ5. From Art Main at TJM:
+25k SFRZ5 96.50/96.625 call spread (10k 1.25’s covered 96.35/.355 delta .05) from 1 to 1.25 (position add ~140k)
+12k SFRZ5 96.625/96.6875 call spread covered 96.30 delta .05 at 0.25 (position add ~70k)
+10k SFRZ5 96.625/96.75 call spread at 0.5 (position add ~20k)
+15k SFRZ5 96.4375/96.50/96.5625 call fly at 0.25
–All of these require MORE than 2 more 25 bp cuts. Current EFFR 4.09. Cut 50 leaves it 3.59 or 96.41. Jan FFs (FFF6) are nearly there at 96.37. SFRZ5 is 9632.5.
–It’s all about gold now. A move >1%, like this morning, adds over $270 billion to market cap (estimated at $27T). Almost enough to buy Chevron ($317b mkt cap).
They wanna get my
They wanna get my gold on the ceiling
I ain’t blind, just a matter of time
Before you steal it
–Black Keys

