
Someone looking for a blow-up?
February 21, 2025
*******************
–Just considering yesterday’s flows, and this isn’t particularly rigorous analysis, it seems to me that someone is betting on an accelerated easing timetable, and that longer dated treasuries may see rising yields either as a result, or as an independent move.
–Just after the FOMC minutes on Wed, which discussed a pause in the Fed’s balance sheet run-off, there was a large buyer of SFRU5 9625c covered. That buying continued yesterday paying 11.5 vs 9595 with 28d, I believe up to 50k (11.0s ref 9593). In any case, open interest in the calls rose 62k with total OI 152k. Adding to SFRU5 call open interest was a buyer of 50k SFRU5 9650c vs selling SFRZ5 9700c, taking 0.5 credit (had taken 1 credit on Wed afternoon. Yesterday’s settles 8.0 and 8.5, U5 9593 and Z5 9600). Considering these strikes in the context of Fed easing, current EFFR is 4.33 and the SOFR settings have been around that level or just above by a few bps. An ease would put EFFR at 4.08 or 9592, and SFRU5 settled 9593.0. So the 9625 strike is somewhat aggressive; something bad has to happen.
–Much more definitive was a new buyer of 110k FFK5 at 9571.0. Risk 4 to make 21 on an ease in March. The next meeting is May 7, so even if March results in no action, an ease at the May meeting would put FFK5 at 95.864. FFK5 settled 9572.0.
–On the TY side, early new buyer of TYJ5 108/110 risk rev vs TYH5 108-31, paid 8 for the put 50k. There was also a new buyer of ~20k TYJ5 109p cov 109-045, paying 41. Settled 39 vs 109-095 so 1’25 in the straddle. And a buyer of 20k TYK5 106p for 10.
–In conclusion: buying short-end calls and futures, buying TY puts. Invitation to put on 2/10 steepener? Not sure, but at 23.5 bps it’s near lower end of range… NOT ADVICE. DON’T DO THIS. YOU MIGHT LOSE. (There. A disclaimer).
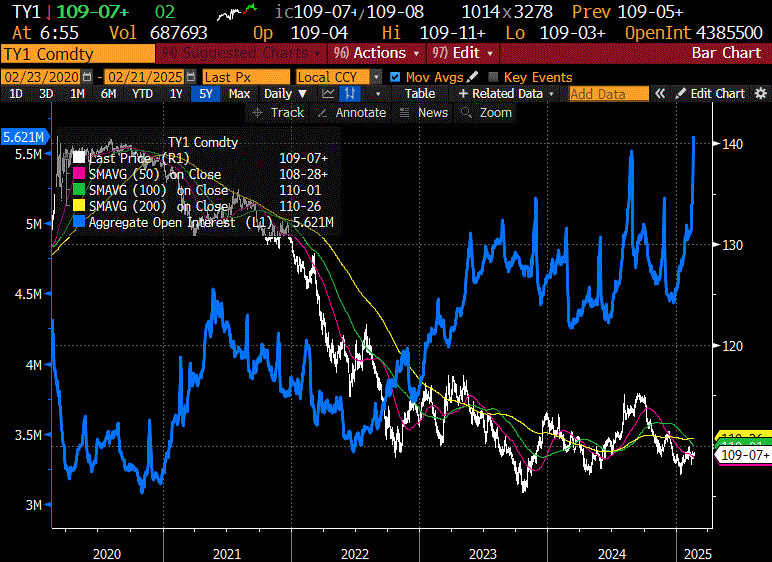
–I would also note RECORD open interest in FV and TY at 7.147m and 5.621m respectively. A lot is driven by basis trades, which Vice-Chair for Supervision Barr touched upon in his comprehensive speech yesterday:
One area that has grown substantially is the Treasury cash-futures basis trade. The basis trade helps provide liquidity and price discovery in normal times, as hedge funds trade with asset managers and other financial institutions to align returns to holding Treasury securities and related futures. But the trade involves high levels of leverage, which can contribute to a rapid unwinding in positions and exacerbate market stress, as we saw in the spring of 2020. In principle, margining practices and participants’ risk-management activities should limit these risks, but individual firms do not account for the spillovers their actions can have on market functioning. These externalities suggest a role for regulation, and the central clearing mandate for Treasury market trading is an important step in supporting the resilience of this market. At the same time, we need to continue to consider how we can support the collection of minimum margin across trading venues and in bilateral trades to avoid loopholes and risks, and continue to monitor banks’ credit risk management practices with these hedge fund counterparties.
–I was taught early on that huge increases in open interest are potential tinder for the next big move. Longs and shorts have staked out their positions, one side is going to be badly wrong and have to scramble to cover. (That was from my technical analysis class given by Ken Shaleen when I was a runner on the floor. With all the complexities and ‘innovations’ in trading, I’m not sure if that idea still has merit, but I’m running with it).
–March treasury options expire today. Below is TY1 (rolling futures) with aggregate OI in blue.
Large SOFR call buys post-minutes
February 20, 2025
*******************
–Early part of the session was quiet, though Housing Starts lower than expected at 1366k (1390 exp and 1515 last). I didn’t expect anything from FOMC minutes, as Powell and other officials had already indicated that inflation concerns would keep the Fed on the sidelines for the near term. However, post-minutes there was a flurry of activity due to unexpected discussions about balance-sheet runoff.
–A lot of SOFR call buying post-FOMC minutes:
0QZ5 9700c vs 9603, 16d. paid 10 to 10.5 for 50k. 10.5s vs 9604.5 in SFRZ6
SFRU5 9625c vs 9589.5, 26d paid 9.5 for 40k and vs 90.5 with 28d 10 for 5k. 10.25s vs 9591.5 in SFRU5
–Below are a couple of snippets from the minutes:
In considering the expected path of the federal funds rate, the manager noted that the modal policy rate path implied by options prices had not changed appreciably on net over the intermeeting period and was broadly consistent with a single quarter-point lowering of the target range for the federal funds rate taking place during 2025. [Market is pretty much in line with Fed officials’ comments]
In their expectations of Federal Reserve balance sheet policy, survey respondents on average saw the process of runoff concluding by mid-2025, slightly later than they had previously expected. [Powell in press conference didn’t seem too concerned about current reserves]
A number of participants also discussed some issues related to the balance sheet. Regarding the composition of secondary-market purchases of Treasury securities that would occur once the process of reducing the size of the Federal Reserve’s holdings of securities had come to an end, many participants expressed the view that it would be appropriate to structure purchases in a way that moved the maturity composition of the SOMA portfolio closer to that of the outstanding stock of Treasury debt while also minimizing the risk of disruptions to the market. Regarding the potential for significant swings in reserves over coming months related to debt ceiling dynamics, various participants noted that it may be appropriate to consider pausing or slowing balance sheet runoff until the resolution of this event.
So there’s the catalyst. Balance sheet adjustment might be ‘paused’, and…if Fed holdings move more in line with outstanding debt, I think that favors a move closer in on the curve.
Below from BBG:
The minutes for the January FOMC meeting were generally in line with expectations. However, a nod to pausing balance sheet runoff during the coming budget negotiations — amid worries about swings in reserve levels — has both equities and Treasuries a touch higher. Given the lack of recent clarity regarding the Fed’s long-term plans for the balance sheet and where exactly “ample reserves” are, traders may be thinking once something stops it will be harder to restart.
–The surprising thing to me is that vol has generally been compressing, even as more plates are added to wobbling spinners already on sticks. That stopped yesterday. In a way, the Fed discussion underscores the Fed’s modus operandi: If the market needs liquidity for any reason, we provide it.
–Though rate futures have been fairly quiet, there ARE markets moving based on Fed and administration ideas: Fannie and Freddie have exploded higher (FNMA and FMCC). Privatization. The largest REITS, Annaly (NLY) and AGNC have had stellar rallies since early January. Tighten MBS spreads? On the other hand, market darling Palantir (PLTR) has dumped around 13% since Tuesday as the Pentagon looks to cut spending.
–Today’s data includes Philly Fed expected 14.3 from 44.3. Jobless Claims 215k (I guess they don’t expect to capture gov’t workers that have been cut, but it’s gotten to the point that DC real estate claims have to be “debunked”
https://www.realtor.com/news/trends/elon-musk-doge-dc-housing-market-crash
–These days every comment has to be prefaced with the disclaimer used by Chris Long (emphasis added):
If data is correct, there are over 12.5m people over the age of 120 receiving Social Security. If you assume $1000 a month (probably too low), that’s $150 billion a year in false payments. Pretty amazing stuff if it’s real.
Rates Quiescent
February 19, 2025
*******************
–Yields rose yesterday with tens up 6.8 bps to 4.542%. Going into Friday’s March Treasury option expiration, I had thought TYH5 would gravitate to the 109 strike, but yesterday’s settle was a bit lower at 108-27.
–Vol was again hit. Example: On Friday SFRH6 9600^ was 74.25. Yesterday, 72.0. It wasn’t all that long ago when the first quarterly SOFR straddle trading around 100 bps was much closer than it is now.
Currently:
SFRU6 9600^ is 96.5 ref 9603.5. 570 dte
A month ago, Jan 17:
SFRM6 9600^ 101.0 ref 9600.5. 509 dte
On Dec 19
SFRM6 9600^ 103.5 ref 9599.5 540 dte
On Nov 18
SFRH6 9612.5^ 100.75 ref 9616.5 480 dte
And Oct 18
SFRZ5 9662.5^ 96.5 ref 9662.5 418 dte
What’s the point? Pre-election premium was pumped. Now it’s not. Today we have the FOMC minutes, but since the last meeting many officials including Powell have said the Fed’s in no hurry to adjust rates. The SOFR strip, with prices clustered just above and below 4% (9600) reflects that, as does option premium.
–Housing starts also out today, expected 1390k.
–Gold making a new all-time high this morning, with spot $2944. In the beginning of this year it was 2600.
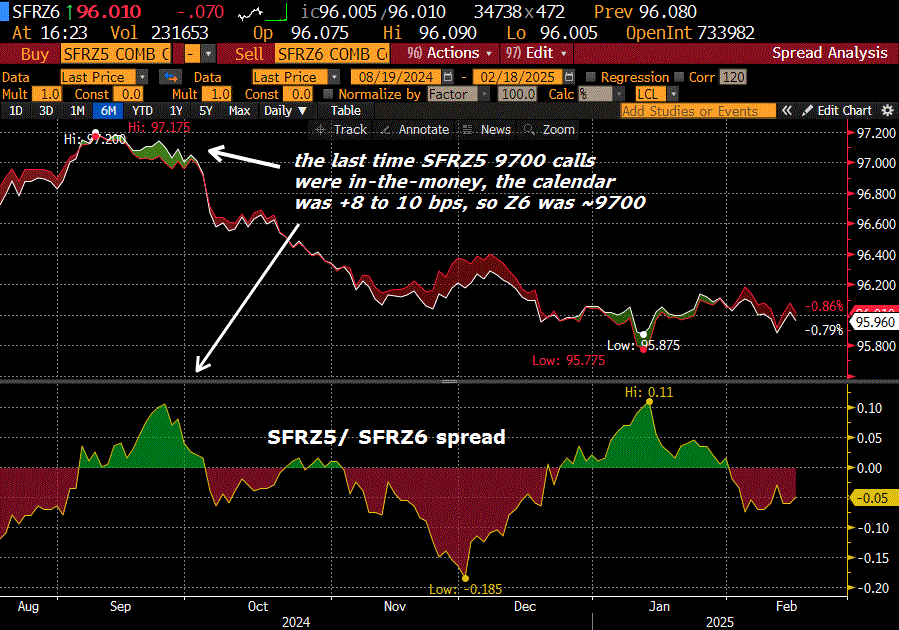
–One trade of note yesterday, that I simply highlight because it’s being accumulated over time in 15k clips, and is a somewhat interesting disaster curve trade:
Buyer 15k SFRZ5 9700c vs 0QZ5 9750c for 3.5. Settles: 8.0 and 4.75 (3.25). Adding, long ~60k, most bot better, call it 1.0 to 3.5. Both options expire 12/12/25. Chart is both contracts (top panel) and sprd in lower. Trade works best in disaster: Z5 above 9700 (under 3%) on aggressive cuts and hopefully Z5/Z6 spread stays around 0 (or at least above -45).
Waller HODL
February 18. 2025
*******************
–From Waller’s speech yesterday:
After two good months of inflation data for November and December, January once again disappointed and showed that progress on inflation remains uneven. I continue to believe that the current setting of monetary policy is restricting economic activity somewhat and putting downward pressure on inflation. If this winter-time lull in progress is temporary, as it was last year, then further policy easing will be appropriate. But until that is clear, I favor holding the policy rate steady.
https://www.federalreserve.gov/newsevents/speech/waller20250217a.htm
–Previously he had opined that further rate cuts were warranted; now wants to wait and see as economy is firm and inflation is bouncy. Waller also briefly touches on the divergence between rate cuts and the corresponding surge in 10y yields, but merely notes that divergences have occurred before, and offers no explanation for the current situation, apart from saying. “It’s NOT OUR FAULT.” I have no idea why that section was even included in the speech:
“This example is just to illustrate that the 10-year Treasury yield may not respond to the policy rate as expected because of a variety of factors that are beyond the control of the FOMC.”
By way of contrast, the Trump admin does NOT think that the 10y yield is beyond its control.
–Friday featured lower yields, as midweek inflation data were ignored. Retail Sales were weaker than expected, supporting treasuries. I marked ten down 5 bps at 4.474%. On the SOFR strip reds and greens (2nd and 3rd years forward) were strongest, up 7.5. Peak contract is SFRU6 at 9608.5, right around 3.9% one and a half years from now. Seeing a bit of divergence currently between bitcoin and nasdaq, as NQH5 is poised to make new ATH, (22450 on 12/16/24 and now 22283), while XBT is middle to lower end of the past 3-month’s range 91200 to 107000 (current 95670). Of course, that divergence could close at any minute, but bitcoin appears to be trading a bit long and heavy at the moment.
–March treasury options expire Friday. TYH5 currently pinning the 109 strike.
Manipulating long treasury yields lower wont necessarily boost the economy
February 16, 2025 – Weekly Comment
___________________________________________________________________
A friend sent me a link to the latest MacroVoices which this week featured Jim Bianco (thanks DDK). The beginning 5 minutes or so is Bianco’s excellent summation of a proposal that’s being called the Mar-a-Lago Accord. A rough outline is that Treasury would issue 100-year bonds that pay no interest. Foreign countries which hold US Treasuries and benefit from US Defense services, would be invited swap their interest-bearing treasuries with the new bonds, essentially paying for defense services by foregoing interest. (No swap, no defense). The Fed could then set up swap lines for any country needing liquidity, and would accept the zero interest bonds as collateral at par.
As mentioned last week, long dated swap spreads continued to surge as regulators are likely on the verge of loosening Supplementary Leverage Ratio (SLR) and G-SIB surcharge rules. (RTRS) “In April 2020 the Fed temporarily excluded treasuries and central bank deposits from the SLR to boost liquidity… But it let the exclusion expire the following year.”
From Fed’s Michelle Bowman speech Feb 5, “Where we can take proactive regulatory measures to ensure that primary dealers have adequate balance sheet capacity to intermediate Treasury markets, we should do so. This could include amending the leverage ratio and G-SIB surcharges…”
From a 2024 ISDA letter to the Fed, FDIC and Comptroller of the Currency:
To facilitate participation by banks in U.S. Treasury markets—including clearing U.S. Treasury security transactions for clients—the Agencies should revise the SLR to permanently exclude on-balance sheet U.S. Treasuries from total leverage exposure, consistent with the scope of the temporary exclusion for U.S. Treasuries that the Agencies implemented in 2020.
Obviously, with massive deficits and the administration seeking to get long-term yields down, it’s important for US banks to absorb UST issuance. A permanent exclusion of SLR rules dovetails with this goal. While it might lessen costs for the US Gov’t, rates on private debts may not see as much relief, but I suppose, at the margin, the ‘crowding out’ effect is reduced.
I did not read the paper, but ZH quotes BofA’s Hartnett: “…rising inflation means Trump in coming months has to go ‘small’ not ‘big’ on tariffs and immigration to avoid fanning 2nd wave of inflation.” Personally I think that’s wrong. Trump is looking to alter incentives, not at the margin but at the core of the system. If it results in some wrenching short-term pain, I think the administration is willing to pay that price, even if stocks falter. Better to take the pain early. I refer once again to Nayib Bukele’s speech on taking decisive action to change incentives:
https://www.facebook.com/nayibbukele/videos/522919087190090/
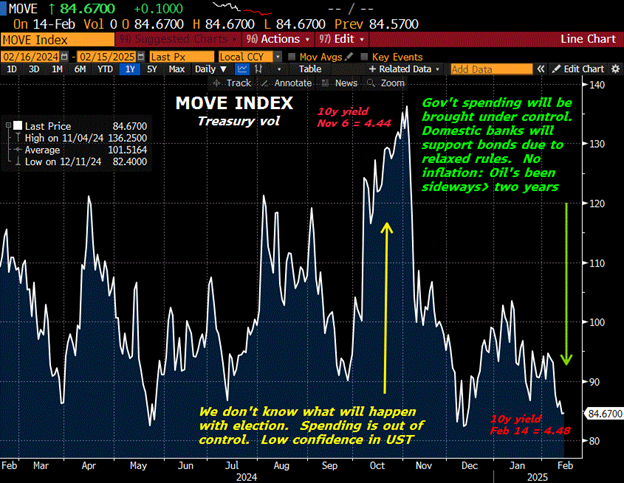
The MOVE chart below is, perhaps, a reflection of confidence in that idea. Bond vol is dropping. I would note as well that VIX at 14.77 is nearing the lower portion of its range.
Market color
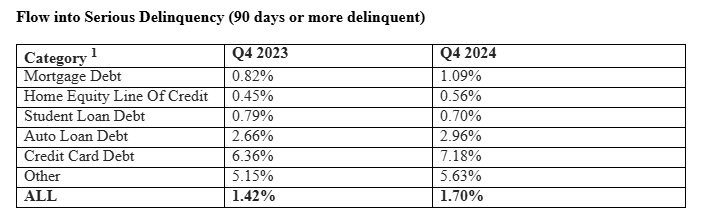
CPI was higher than expected. Retail Sales were weak. The NY Fed’s Consumer Credit report shows that Flows into Serious ( > 90 days) Delinquency on all categories of Consumer loans edged up in Q4, except Student Loan Debt. Mortgages from 0.82% in Q3 to 1.09% in Q4. Auto Loans 2.66% to 2.96%. Credit Cards 6.36% to 7.18%. Conclusion that some analysts are drawing: Stagflation.
Yields ended little changed on the week. On the SOFR strip the largest decline was SFRH5 at 9569.25, down 2.75. The largest gains were SFRZ5, H6 and M6 all up 2.5, prices of 9602, 9606 and 9608. Due to inflation concerns, near contracts are gravitationally pulled down towards the Fed Effective rate of 4.33%, as the Fed is expected to hold steady in the near term. The peak SOFR contracts are closer to 4% reflecting a modest adjustment over time towards the neutral rate. The ten-year yield was nearly unchanged despite auctions, ending 4.48%. Though inflation expectations have increased, the market is looking past these concerns. Last week’s price action simply indicates that a possible acceleration in inflation has been dismissed. The big question is whether the US economy surges due to relaxed regulatory burdens and new domestic investment in energy and manufacturing. Or whether tariffs, an immigration crackdown and decelerating gov’t spending tip the country towards recession. Over the short term, I lean towards the latter and over the longer term, the former.
Regarding SOFR option plays, I personally favor long call spreads, though the 9562.5/9537.5ps in SFRU5 for 1.75 was a popular buy last week. (Settled 1.5 vs 9594.0). This post from George Austin at Pricing Monkey sums it up:
Heavy options skew in SFRU5 (Sept SOFR) centred around 4.37%.
If you need a hedge for a rate hike, put strategies are cheap with the skew (see lower chart).
For upside exposure, call spreads, flys, and condors are all near the bottom of their price ranges, making them attractive plays in this skewed environment.
Friday is March treasury option expiration. Peak open interest is TYH 108.5c with 179k open; settled 55 ref 109-10. These calls were originally purchased in size vs futures, when they were just out-of-the-money. Currently, the 108.5p is just 3/64s. The 109p, which has been heavily jobbed around in the past week or so, settled 9 and has 90k open. I would expect futures to edge toward the 109 strike going into expiry.
(This note is NOT intended as financial or trading advice).
| 2/7/2025 | 2/14/2025 | chg | ||
| UST 2Y | 427.7 | 425.5 | -2.2 | |
| UST 5Y | 433.1 | 432.7 | -0.4 | |
| UST 10Y | 448.0 | 447.4 | -0.6 | |
| UST 30Y | 468.1 | 469.4 | 1.3 | |
| GERM 2Y | 204.8 | 211.3 | 6.5 | |
| GERM 10Y | 237.2 | 243.1 | 5.9 | |
| JPN 20Y | 196.6 | 201.3 | 4.7 | |
| CHINA 10Y | 160.6 | 165.0 | 4.4 | |
| SOFR H5/H6 | -31.5 | -36.8 | -5.3 | |
| SOFR H6/H7 | -2.0 | -1.0 | 1.0 | |
| SOFR H7/H8 | 4.5 | 5.5 | 1.0 | |
| EUR | 103.30 | 104.93 | 1.63 | |
| CRUDE (CLJ5) | 70.74 | 70.71 | -0.03 | |
| SPX | 6025.99 | 6114.63 | 88.64 | 1.5% |
| VIX | 16.54 | 14.77 | -1.77 | |
| MOVE | 93.13 | 84.67 | -8.46 | |
https://www.isda.org/a/h3sgE/ISDA-Submits-Letter-to-US-Agencies-on-SLR-Reform.pdf
In: Eurodollar Options
Bonds and Wheat
February 14, 2025
**********************
–PPI was also higher than expected, with yoy 3.5% vs 3.3 exp, but rather than extend the sell-off from Wednesday’s hot CPI, the market completely erased the move. On Tuesday, TYH5 settled 108-305. On Wed (CPI) 108-085. Yesterday, 108-31. Similar in SOFR, for example SFRH6 9601.5, 9591.0, 9598.5. Today’s news includes Retail Sales for Jan, expected -0.2 but +0.3 ex-auto.
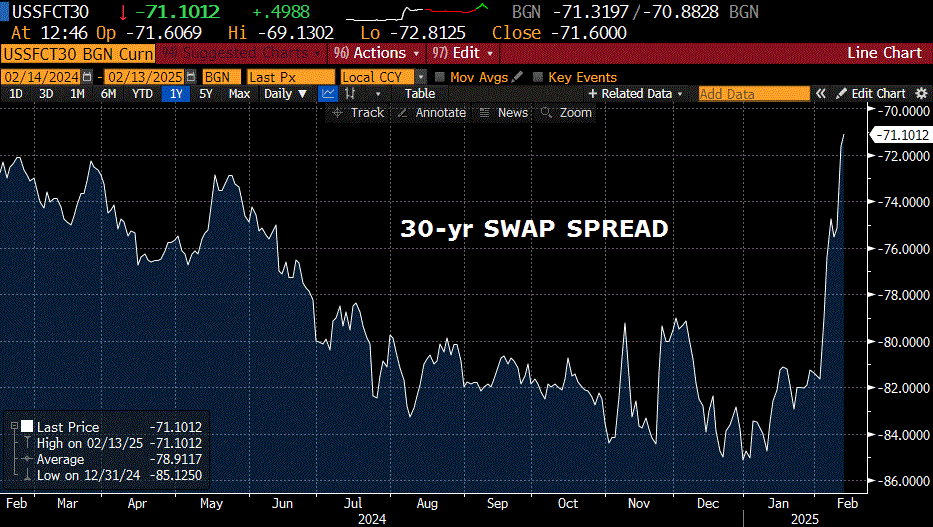
–Perhaps part of the move is related to the surge in swap spreads, with the 30-yr pictured below. This move is being attributed to possible relaxation of G-SIB surcharges and a loosening of SLR (Supplemental Leverage Ratio) rules, according to BBG:
https://blinks.bloomberg.com/news/stories/SRMK84T0G1KW
–Rally has been similar in the ten-yr swap spread. I take marks at the time of daily futures settles, of 10y cash (PX1) and 10-yr swap (page IRSB ). On Jan 3, I marked 10y 4.61 and the swap at 4.133, a spread of negative 47.7. Yesterday, 10y 4.523% and swap 4.146 or negative 37.7. In other words, the 10y yield fell by 8.7 while the swap was up nearly 2 bps in yield.
–Wheat threatening new recent highs, up 9 cents to 601. “BREAKING: Ukraine says Russia has struck the Chernobyl nuclear plant with a drone attack.” The 1986 Chernobyl incident sparked a hard rally in grains (at the time, April 1986, front wheat 289 to 360 in ten sessions). Of course, we don’t know who hit the plant, but it’s being reported as Russia, with no radiation leak. Silver also seeing an upside breakout.
–Yes, I know the new administration is scary and corrupt, so it’s nice just to retreat back into Illinois politics:
NY Times: ‘Mike Madigan, former Illinois House Speaker, found guilty in corruption trial’
Chicago Tribune: Three top city officials stepping down after Mayor Brandon Johnson’s message: ‘If you ain’t with us, you just gotta go’
–Below the chart is a table from Fed’s Consumer Delinquencies. All moving higher, notably auto loans and credit cards.
Inflation… in WIG20
February 13, 2025
*******************
–CPI sent yields soaring, +0.5% m/m vs expected +0.3. Yoy was 3.0%. Recent peak was Sept 2023 at 3.7%. The yoy low was Sept 2024 at 2.4%. Ten year yield jumped 10 bps to 4.635%. On the SOFR strip, blues (4th year forward) were weakest, -14.5 on the day. Typically, reds (2nd yr) would be weakest on a day like yesterday, but there was actually a bit of steepening in the short end as all contracts give up on the idea of easing, with Powell saying the Fed’s in no hurry while data raises fears of actual rate hikes. Five year note was weakest, up 11.2 bps to 4.482%. Once again, treasury vol was slightly lower, especially in March, which expires one week from tomorrow. As of now, panic about soaring yields is NOT being reflected in treasury premium.
–PPI and 30yr auction today.
–One new trade yesterday that I would note: buyer of 20k SFRU5 9562.5/9537.5 ps for 3.5. Not particularly large, top strike is 20 otm with U5 settling 9582.5. In a bearish market with NO ease, the top strike might be near the money. For example, SFRH5 settled at a new low yesterday of 9568.5. But the Sept put spread really requires a hike to pay off at expiration. Back to SFRH5: the 9568.75 straddle settled 3.75 with 30 days until expiration. Remarkably cheap, given the geopolitical backdrop. It’s as if monetary policy is now iced, while the rest of the world is spinning faster. SFRM5 9575^ settled 15.5 with 121 dte vs 9575.
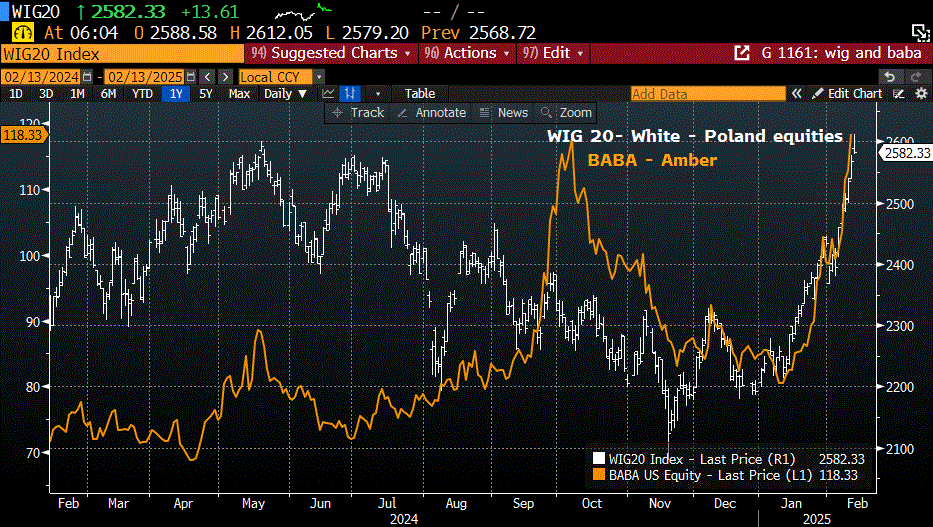
–This morning as I skimmed news I saw something about WIG20, the Poland equity index. It has gained 18% since the start of the year, supposedly on hopes that the Ukraine conflict is nearing an end. Looked similar to BABA chart (China) so I overlaid that stock price, up nearly 50% since early Jan, but obviously for a much different reason, as China is pulling out all stops to support equities.
Inflation expectations have risen. What will CPI say.
February 12, 2025
*******************
–Not much reaction to Powell’s appearance. Yields ended higher on the day with tens up 4.2 bps to 4.535% in front of today’s CPI data and 10y auction. Three year auction was solid at 4.30%. Odds for an ease in March (and beyond) are being squeezed out. Current SOFRRATE is 4.35% or a price on 9565 (ignoring daily compounding). SFRH5 settled -0.5 at 9570.5, while SFRM5 settled 9581.0, down 2 on the day. April Fed Funds are 9568.5 against a Fed Effective of 4.33% or 9567. Peak SOFR contract is SFRU6 at 9604.0 or 3.96%.
–CPI expected 0.3 both headline and core m/m. Yoy 2.9% from 2.9 last, with Core 3.1 from 3.2 last. Whisper numbers appear to tilt higher. Long maturity treasury futures are currently unch’d from yesterday’s settles.
–Late new buyer 37k TYH5 109.75/110.5cs for 6 ref 108-31. Settled 6 ref 108-30+ (8 & 2). Also buyer 20k TYH 109p 18 to 20. Someone seems to be jobbing around 20k clips of 109 puts. In any case, settled 28 with futures 108-30+. TYH5 109 straddle expires one week from Friday and closed 0’53, which I calculate just under 13 bps. For a rough comparison, blue Feb midcurves expire this Friday. SFRH8 settled 9597 and the 9600^ settled 10.5. Slightly cheap in my opinion.
Powell faces off with the Senate
February 11, 2025
********************
–Yields little changed yesterday with tens +1 bp at 4.493%. Interest rate premium hit across the board, with many SOFR straddles losing a couple of bps. For example, on Friday, SFRU5 9593.75^ settled 40.75. With the contract +0.5 to 9593.5, that straddle settled 39.25 yesterday. SFRZ5 9600^ went from 60.5 to 58.5 with Z5 +1 to 9600.5. Large exit seller yesterday of 40k 0QZ5 9700/9800cs at 8.25 to 8.0, settled 7.75 vs SFRZ6 9607.5. In TY, the April 109^ was 1’62 on 3-Feb vs 108-30, yesterday down to 1’43 vs 109-065. Price action and volume are muted.
–Today brings Powell’s testimony to the Senate at 10. Prior to that Hammack (dissented in December to hold rates steady) speaks on the economic outlook. 3y auction of $58b. CPI tomorrow. Perhaps the most important issue for the Fed is that inflation expectations have been pushing higher. Overt recognition of that fact by the Fed Chair would likely be bearish. I’ll just note one SOFR option trade that would probably work on one hike by summer: +15k SFRN5 9562.5/9537.5/9525 put fly 1x3x2, for 0.75. Currently EFFR is 4.33 and SOFRRATE is 4.35 to 4.36, which wouldn’t quite get to the 9562.5 strike even with full convergence. So, this trades needs a hike, or a very strong perception of tightening, to work out.
–There have been obvious signs of stress for lower income consumers, and the middle market has been trading down to lower priced venues. From a BBG piece yesterday citing McDonald’s CEO:
“Across the industry, purchases from low-income guests were down substantially in the fourth quarter, Chief Executive Officer Chris Kempczinski said Monday on a call with analysts following the company’s earnings release.”
–Just a brief note about Treasury rolls, specifically TY:
In the past four days, the roll has traded -0.25 to +0.50. Currently 0.25/0.50.
For the first time in a while, there is very little duration difference between the two contracts,
DV01 in TYH5 is $64.09
DV01 in TYM5 is $64.22
–Yesterday morning there was a block roll of TYH puts to TYJ puts, which typically affects the futures roll. I would expect option rolls, given large open interest levels in TYH would become the primary driver of the TY spread. However, as of now, open interest in TYH5 is 4.888 million while TYM is just 46k. March options expire one week from Friday.
Note that FVM5 has about 6.5% more duration than FVH5 and UXYM5 has less than 1% more than UXYH5:
DV01’s on the contracts ($100k notional)
FVH5 $41.25
FVM5 $43.90
UXYH5 $87.45
UXYM5 $88.02
Peak Taylor
February 10, 2025
*******************
–Front end bore the brunt of selling pressure Friday. Payrolls were mixed with NFP 143k (175k exp) but previous revised up 51k to 307k. Avg Hourly Earnings jumped to 4.1% yoy vs expected 3.8. Unemployment rate fell to 4.0%. The big surprise was U of Mich 1-yr inflation expectations which surged to 4.3% vs 3.3 expected. 5-10 yr inflation expectations also rose to a new cycle high of 3.3%. last seen in 2008.
–Weakest contracts on the SOFR strip were -9, SFRZ5 at 9599.5 and SFRH6 at 9503.5. (Still right around 4%). The two-yr note rose 7.1 bps to 4.277% and 10s rose 4.7 bps to 4.483%. Auctions this week of 3s, 10s and 30s begin tomorrow. New recent lows in both 2/10 at 20.6 bps and 5/30 at 35.1. SFRH5 settled at a new low 9572, at 4.28%, just 5 bps under EFFR at 4.33%. SFRM5 settled new low at 9583 or 4.17%. All SOFR contracts from SFRU5 (9593) to SFRU9 (9589.5) are within 10.5 bps of 4%. The peak contract is now SFRU6 at 9606.5. Easing hopes continue to be squeezed out (though there was significant buying of call spreads last week).
–Powell in front of Senate tomorrow. Most worrisome for the Fed are increases in inflation expectations.
–Peak Taylor as Chiefs were destroyed. Cracks were already showing. Mag7?

