Shorter runway to runoff
February 9, 2025
*****************
Futures Clearing and Execution/ amanzara@rjobrien.com
Truckin’, like the doo-dah man
Once told me, “You got to play your hand”
Sometimes the cards ain’t worth a dime
If you don’t lay ’em down
Truckin’ – Grateful Dead
I always thought it was “…the cards ain’t worth a ‘damn’” not ‘dime’. Another one of my long-held beliefs, shattered. I’m getting used to it. But I’ll double check with Liesman anyway. He’ll know.
These are hard hands to play. Plenty of bluffs. Sometimes better to just fold and preserve capital.
*This note is a little long. Can probably skip the following section; the point is that reserves may not be abundant or even ample; the end of QT draws near. Long-dated swap spreads shifted higher last week. I think the Fed will be extremely careful as it doesn’t want to risk a repo blow-up like that of September 2019. Market color below the charts if you want to skip forward.
*******************************
The Fed’s ‘Monetary Policy Report’ was released Friday, in preparation for Powell’s appearance before Congress this week.
https://www.federalreserve.gov/publications/files/20250207_mprfullreport.pdf
The report is comprehensive, but almost feels dated in some respects. We’re in an environment where things can change rapidly, and the confidence that reserves are ample may be misplaced.
Pages 43 and 44 of the pdf (pp 33 and 34 of actual report) were interesting: Nonfinancial business and household debt-to-GDP trending down since 2020. Bank credit continuing to decelerate.
Regarding reserves, from the Jan 29 press conference, Powell said, “So the most recent data do suggest that reserves are still abundant. …As always, we stand ready to take appropriate action to support the smooth transition of monetary policy, including to adjust the details of our approach for reducing the size of the balance sheet…”
Page 52 of pdf (pg 42 actual report)
Reserves, the largest liability item on the Federal Reserve’s balance sheet, have edged down $68 billion since late June 2024 to a level of about $3.2 trillion. Since the beginning of balance sheet runoff, reserves have been little changed because the reserve-draining effect of balance sheet runoff was largely offset by a $1.8 trillion decline in balances at the overnight reverse repurchase agreement (ON RRP) facility. Since June 2024, usage of the ON RRP facility has continued to decline to levels below $200 billion (figure B). Reduced usage of the ON RRP facility largely reflects money market mutual funds shifting their portfolios toward higher-yielding investments, including Treasury bills and private-market repurchase agreements. Conditions in overnight money markets remained stable. The ON RRP facility continued to serve its intended purpose of supporting the control of the effective federal funds rate (EFFR), and the Federal Reserve’s administered rates—the interest rate on reserve balances and the ON RRP offering rate—remained highly effective at maintaining the EFFR within the target range. Following the December 2024 FOMC meeting, the Federal Reserve made a technical adjustment to lower the ON RRP offering rate 5 basis points. The technical adjustment aligned the ON RRP offering rate with the bottom of the target range for the federal funds rate.
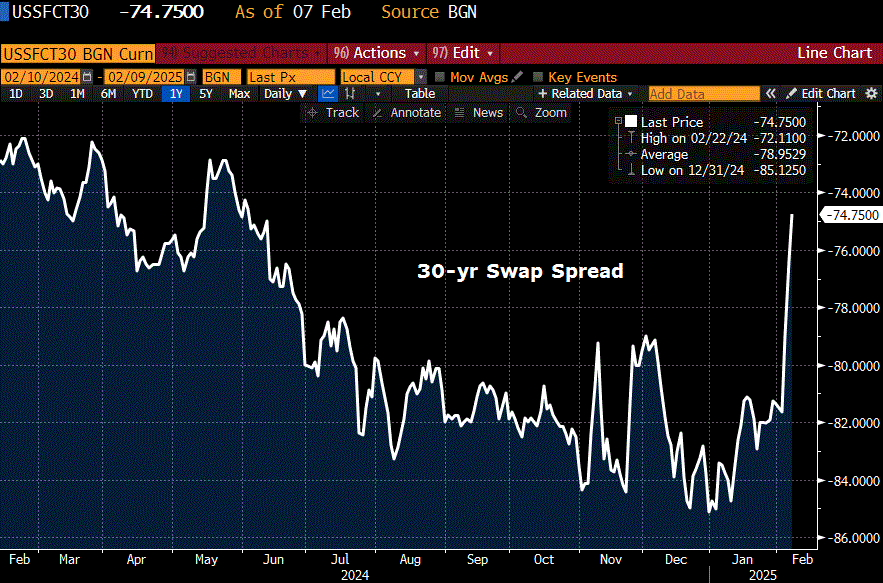
Below is a chart of the RRP. Indicates to me that perhaps reserves aren’t as abundant, and that the end of balance sheet run-off might be a lot closer. The second chart appears to support the thesis, swap spreads surged last week. Another nugget in the Fed’s report is that Hedge Fund Leverage is concentrated in treasury basis trades. Bessent’s comments that the administration is more concerned with ten-year yields rather than the Fed Funds rate might also provide a nudge to end QT.
Market color
Friday’s employment report sparked an increase in yields, most notably in shorter dates. The 2y rose just over 7 bps to 4.277%. SFRZ5 and H6 were weakest on the SOFR strip falling 9 to 9599.5 and 9603.5. SFRZ5 at 4.005% is right on top of the Fed’s FF projection for end of 2025, 3.875%. Notable is that bond vol didn’t ratchet up. The market doesn’t seem all that concerned about the idea of long rates shooting higher. While the 2y jumped 7.1 bps and the 5y rose 6 to 4.331%, the 30y yield only added 3.8bps to 4.682%. Peak open interest in March TY options remains 108.5c with 187k (paper long). On Wednesday there had been a buyer of 100k TYH 109p for 26 down to 18. On Wed that strike settled 20 vs 109-24 with a delta of 32. On Friday, futures settled 109-075 and the put settled 25, 42d (there were exit sales Friday of 20k from 29 to 30). With flat vol, value should have been 29.8, or just above 27 if taking out weekend time value.
Could 2/10 invert again? Sure is starting to feel that way. There was heavy call spread buying in SOFR options last week, but SFRH5 settled 9572, the lowest settle since November. SFRM5 settled 9583, -6.0. In the last several months there is only one lower settle in M5, 9582 on Jan 13. Short-end charts look an awful lot like a hiking cycle since Sept, but they are actually NO EASE charts. How does 2/10 invert? The Fed holds firm, and if data supports economic deceleration, buyers will move a bit further back on the curve. Fed ends QT and we could easily see 2/10 back at the December starting point of 0. Stocks are the wildcard. A hard slide would instantly spark calls for rate cuts.
Inflation expectations seem to be creeping up. A lot of talk about eggs, but since end of September, Live Cattle up 9.2% (ath this year), Corn +14%, Coffee up 50% (ath), Gold up 8.6% (ath). On the other hand, CLH5 settled Friday at 71.00 bbl, down from a high of 78.71 in mid-Jan. Forward oil contracts are lower. For example, CLZ5 contract is 67.70.
On Friday the U of Mich 1y inflation expectation surged to 4.3% from 3.3% and the 5-10 yr measure firmed to a new high of 3.3% from 3.2%, highest since 2008. The five-year breakeven (treasury vs inflation-indexed note) which made its low of the cycle in early September at 187 bps, is 262 bps now, up 75 bps in the five months since the first Fed cut (high since early 2023). 10y breakeven is 243, up 40 bps since mid-Sept.
On Tuesday Cleveland Fed President Beth Hammack gives a speech on the economic outlook. She dissented at the December FOMC, preferring no ease given the healthy labor market and elevated inflation. Powell appears in front of the Senate at 10, just after Hammack’s speech.
In ESH5, the last two Mondays featured hard breaks. First related to DeepSeek and second to tariffs. On Friday 1/24 ESH high was 6162.25 and Monday’s low 5948 (Range 214, midpoint 6055). On Friday 1/31 the high was 6147.75 and Monday’s low was 5936.50 (Range 211, midpoint 6042). Friday’s high was 6123.25 and the settle was 6049.50, right in between the last two midpoints. Weekend risk is back. Tomorrow’s low 5913??? (210 off Friday’s high).
A friend mentioned that spreads between one-month SOFR (SER) and FF contracts have been widening. I would note that FFH5/SERH5 has moved from 0 on 12/17 to 3.0 now, and FFJ5/SERJ5 has gone from 0 on 12/20 to 2.5 now. Below is a chart of FEDL01 (Fed-effective rate) to SOFRRATE.
End of quarter tends to spike. Both FF and SER contracts are arithmetically averaged over the contract month. But these spreads bear watching as March is end-of-quarter and end of Japanese year (March 31 is a Monday). April 15 is tax day. I would NOT be inclined to sell SFRH5 premium at these levels.
***********************
News this week includes:
Monday:
NY Fed 1-yr Inflation Expectations 3.0% last. Perhaps important due to huge jump in U of Mich 1 yr expectations at 4.3%.
Tuesday:
6:00 NFIB Small Biz Optimism
8:50 Hammack on Econ Outlook. Dissented in December
10:00 Powell testifies to Senate
1:00 3yr auction $58b
Wednesday:
8:30 CPI yoy expected 2.9 from 2.9, Core 3.1 from 3.2 Also Annual Revisions
10:00 Powell testifies to House
1:00 10yr auction $42b
2:00 Federal Budget
Thursday:
8:30 PPI and annual revisions. Jobless Claims
1:00 30yr auction $25b
Friday:
8:30 Retail Sales
9:15 Industrial Production
| 1/31/2025 | 2/7/2025 | chg | ||
| UST 2Y | 423.0 | 427.7 | 4.7 | |
| UST 5Y | 436.4 | 433.1 | -3.3 | |
| UST 10Y | 457.1 | 448.3 | -8.8 | wi 448.0 |
| UST 30Y | 482.2 | 468.2 | -14.0 | wi 468.1 |
| GERM 2Y | 211.9 | 204.8 | -7.1 | |
| GERM 10Y | 246.0 | 237.2 | -8.8 | |
| JPN 20Y | 192.6 | 196.6 | 4.0 | |
| CHINA 10Y | 163.0 | 160.6 | -2.4 | |
| SOFR H5/H6 | -33.5 | -31.5 | 2.0 | |
| SOFR H6/H7 | 5.5 | -2.0 | -7.5 | |
| SOFR H7/H8 | 7.5 | 4.5 | -3.0 | |
| EUR | 103.63 | 103.30 | -0.33 | |
| CRUDE (CLH5) | 72.53 | 71.00 | -1.53 | |
| SPX | 6040.53 | 6025.99 | -14.54 | -0.2% |
| VIX | 16.43 | 16.54 | 0.11 | |
| MOVE | 91.76 | 93.13 | 1.37 | |
Payrolls!
February 7, 2025
******************
—Payrolls. NFP today expected 175k from 256k last. I’ve seen some higher estimates. Private payrolls expected 150k from 223k. My personal bias regarding TY and US is that a strong number will be met with dip buyers, while a weak number could cause a powerful rally. In TY I suspect the week’s low at 108-20+ will hold, while on the upside I would target 111 to 111-16. 50% retrace on continuous TY from Sept high 115-07 to Jan low 107-07 is 111-07. (last at 109-19). Consumer credit released at end of the day.
–A few large SOFR opts trades: +50k SFRM5 9612.5/9637.5cs 2.5 vs 9588 and 88.5 with 10d. Settled 2.5 vs 9589. A few sessions ago there was a buyer of 40k same strike April call spread for 1.75. Also a buyer SFRU5 9662.5/9762.5cs WITH 0QU5 9712.5/9812.5cs paid 12 for 10k of each. All new positions. SFRU5 cs settled 5.75 vs 9601 in U5, and 0QU call spread settled 6.0 vs 9614.5 in U6. Currently SFRU6 is the highest point on the SOFR strip.
–In early 2019 after SPX had dumped 20% in Q4 2018 and Powell hiked for the last time in Dec 2018, there was a ton of call spread buyers every day in SOFR. It’s almost starting to feel a little bit like that. I don’t quite understand the catalyst. Stocks are holding near record highs. Data remains generally firm. Powell et al have indicated they are comfortable holding rates steady. However, the flows support the idea of lower rates, in my opinion.
–2/10 spread at futures settle was 23, a new low for this year (2025). This morning prints 20.5 which is the halfway back point of the recent surge, 0 on 25-Nov to +42.3 on 9-Jan.
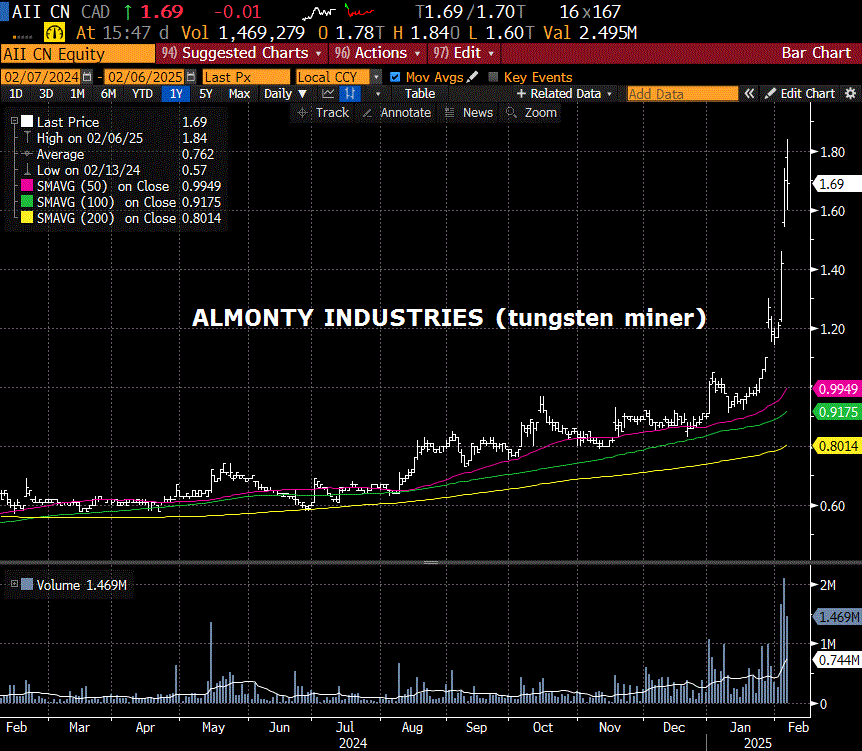
–Attached chart is the stock of Almonty, the largest tungsten miner in N Amer. China’s tariff retaliation includes export controls on tungsten, of which China is, by far, the largest producer. Used in many industrial applications. Supply chain issues resurfacing?
Interesting article:
“We instantiate this network inside the camera lens with a nanophotonic array with angle-dependent responses. Combined with a lightweight electronic back-end of about 2K parameters, our reconfigurable nanophotonic neural network achieves 72.76% accuracy on CIFAR-10, surpassing AlexNet (72.64%), and advancing optical neural networks into the deep learning era.”
Well, when you put it that way, it’s pretty obvious, isn’t it? I wonder if it requires tungsten.
https://interestingengineering.com/innovation/new-camera-identifies-objects-200x-faster
BIG flattener
February 6, 2025
******************
–Back in the Clinton presidency, there was angst about budget deficits. From Bob Woodward’s ‘The Agenda’:
“Clinton recognized that it was the exact argument that Greenspan had made to him the previous month. Deficit reduction could mean lower long-term interest rates.
… Clinton’s face turned red with anger and disbelief. “You mean to tell me that the success of the program and my reelection hinges on the Federal Reserve and a bunch of fvcking bond traders?”
–There was a tacit, or maybe even overt deal. Get the budget under control and the Fed will cut rates.
–From a BBG summary today: Bessent says the Trump admin’s focus is on bringing down 10y yields, not FFs. Bessent believes expanding energy supply will lower inflation and a lower deficit will reduce 10y yields.
–So there you have it, a drop in the 10y yield yesterday of 9.3 bps to 4.418%. Sure we had a low JOLTs number the other day and yesterday ISM Services were a bit lower than expected. But I believe that Musk’s efforts are going to change incentives throughout government, and help reduce the trajectory of spending. Does that justify a ten year yield that’s rapidly closing in on the Fed Effective rate of 4.33%. Maybe not….but maybe. I am sure Powell and Bessent came to a tacit understanding on the issues.
–The outcome is a much flatter curve. Yesterday 2/10 fell 6.4 bps to a new low for 2025, 23.7 bps. On the SOFR curve, all near calendars collapsed to new recent lows. SFRH5/H6 fell 4.5 to -41 (9574.5/9616.5). Just looking at June contracts, M5 +1 at 9590. M6 +5.5, 9617.5. M7 +9.0, 9616.5. M8 +10. 9610.5. A couple of chunky call spread buyers…again, slightly further back on the SOFR curve:
+23k 0QU5 9712.5/9812.5cs 6.5. (settled 7.0 ref 9618.0 in SFRU6)
+25k 2QH5 9650/9700cs covered 9614, 3.25 paid. (settled 4.0 ref 9617.5 in SFRH7)
–Yesterday, a buyer of 100k TYH 109p, starting early at 26 and ending at 18 at the market rallied. Final settle 20 ref 109-24 with 32 delta. Not saying it’s the same guy, but on Jan 14 there was a buyer of 100k TYH 108.5c 28 covered average 107-10, 30d. On Jan 24 a buyer of 50k TYH 108.5c 41 covered 108-11. Yesterday, TYH5 108.5c settled 1’28 (80 delta). TYH 109p have a delta of 30. Protective buys in front of NFP tomorrow?
–Today brings Nonfarm Productivity (1.2% expected) and Jobless Claims expected 213k.
Rate futures find footing
February 5, 2025
******************
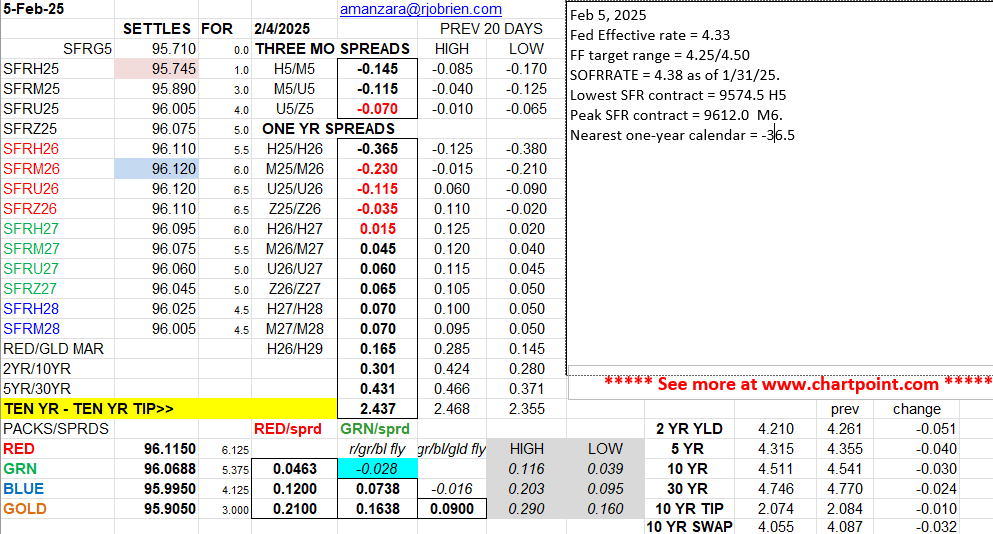
–Near one-year sofr calendars are pressing lower as reds led to the upside (+6.125). SFRH5/H6 settled -36.5 (9574.5, +1 and 9611.0, +5.5). In treasuries the 2y yield fell 5 bps to 4.21% while 10s were down 3 bps to 4.54, so that spread bounced a couple to 30 bps. Overall, the session was quiet.
–JOLTs number was low (7600k vs 8000k expected) which captured the attention of the market. You know it’s boring when JOLTs is the main feature; back to 2019 levels. The inflation mandate still holds sway, but maybe labor concerns will flare again. Payrolls on Friday. By the way, high JOLTs in 2022 was over 12000.
–GOOGL got whacked on earnings and is -7% this morning. On Friday I had thought TY might surpass 109-16 strike. It didn’t, but this morning prints 109-14. USH5 had a low of 113-18 yesterday morning, but now prints 115-07.
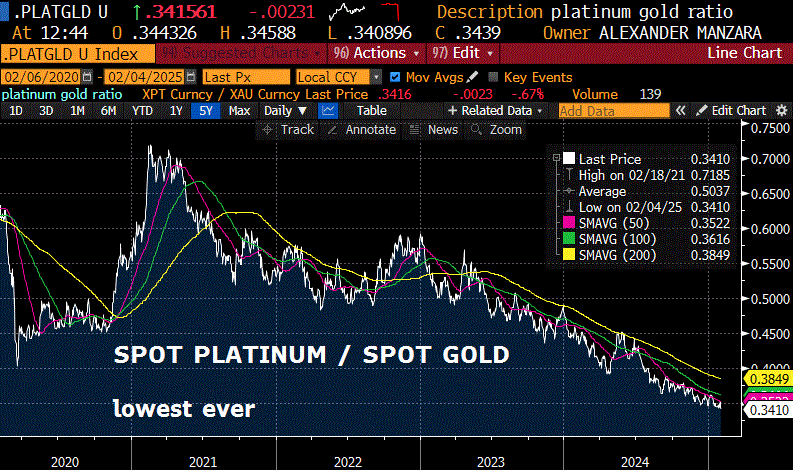
–Platinum cheap. New all-time high in gold; platinum is cheaper to gold than it ever has been. (Market Huddle guest Ole Hansen mentioned it this weekend).
–More SFRZ5 9700c vs 0QZ5 9750c 3.5 for 15k. Settles: 10.75 vs 9607.5 and 7.25 vs 9611.0. Buying front Dec…works well in a disaster, otherwise there’s a slow roll down’ negative carry.
–ISM Services today expected 54 from 54.1. ADP expected 150k from 122k last.
Only halfway thru the first MONTH
February 4, 2025
******************
–Tariffs on both Mexico and Canada were tabled as both countries acquiesced to some US demands about tightening borders. China retaliated with trade restrictions. John Authers has an opinion piece on BBG smugly titled, ‘It’s Almost Like They Knew Trump Was Bluffing.’ I guess he doesn’t think Mexico and Canada really gave anything at all. You know what they say about opinions… I use the analogy of friends going out to dinner. One guy orders the $300 bottle of wine and wants everyone to split the bill. Sure it’s ok once or twice. Friends, right? But eventually, you either stop inviting that guy or want him to kick in a little more. Or drink a beer, like the rest of us.
–Markets are getting rattled due to the new admin. Some stocks continue to make new highs. WMT, COST, IBM as examples. But the backdrop is stretched valuations. Concentration of Mag 7, US stocks at a record percent of global market, market cap to GDP near record high, Cape-Shiller p/e higher than any time since dot-com.
–Big SOFR trade…+40k SFRJ5 9612.5/9637.5/9650/9675c condor for 1.25, then bought another 35k of just the lower call spread for 1.75. Settles: SFRM5 9586.0
Calls: 3.5 1.75 1.25 0.75. Fed Effective is currently 4.33% and SOFR is 4.36 to 4.38. Let’s call it a price of 9565. So the low strike on the condor needs 50 bps of cuts for breakeven. FOMC mtgs 3/19, 5/7. 6/18. We’ll only know the outcome of the March meeting before option expiration, the other meetings rely on perception.
–Bostic echoed Powell, who last week said he’s in no hurry to adjust rates. Bostic said he wants to wait a while and see how the first 100 bps of cuts is affecting the economy.
–Trump put his imprimatur on a Sovereign Wealth Fund.
–ISM Mfg finally poked above 50 for the first time since late 2022. Today brings JOLTS and Durables.
–Curve flattened with 2/10 marked at 28, down 6 bps and a new low for this young calendar year. With Fed officials holding the line, buying necessarily edged out a bit farther on the curve. 2y yield was UP 3 bps to 4.26% while 10s FELL 3 bps to 4.54.
brief note
February 3, 2025
******************
–Starting the month of February with weakness in equities related to Trump imposing tariffs. Dollar surged. Fixed income markets remain weak; on late Friday’s stock sell-off treasuries also fell. TYH5 settled Friday at 108-27. Current print is 108-28+ with ESH 5985 (-82.25).
–In ESH5 the 200 DMA is 5765. The low on Oct 2 was 5776, the low on Nov 4 was 5784, and the low so far in 2025 was on Jan 13, at 5809. Until prices decisively break through these levels, it’s hard to argue that the long term trend has reversed.
–Today’s news includes ISM Mfg, expected 49.9 from 49.3 last. It’s been below 50 since November 2022.

Resilience or Potential Risks
February 2, 2025 – Weekly Comment
***************************************
When I started in this business, there were “Fed watchers”. Guys like David Jones, chief economist for Aubrey Langston, who would occasionally appear on the weekly financial news show, Wall Street Week with Louis Rukeyser. They interpreted what the Fed was doing. It wasn’t always immediately clear if the Fed had hiked or eased. No press conferences, no statements. Just open market operations; liquidity adds or drains, repos or matched sales. Now of course, we have Fed “whisperers”. Journalists who leak the Fed’s message. Fed officials make numerous appearances.
In a way, the old system probably made traders a bit more cautious about possible surprises. Currently we have a lot of people whining about Trump’s unscripted and sometimes contradictory pronouncements which jolt the market. What did you think would happen? We’re going to have this every week.
Thoughtful Money’s podcast last week featured Cem Karsan of Kai Volatility. He made the point that markets may be more volatile for the next few years. Not exactly an earth-shattering revelation. We’re only a couple of weeks into the new administration. It will create both uncertainty and opportunity. But it should also make people much more cognizant of tail risks, something that many analysts have warned about. The range of outcomes is likely wider. When asked in last week’s press conference about financial stability, Powell said,
‘… asset prices… I’d say they’re elevated by many metrics right now. A good part of that, of course, is this thing around tech and AI, but we look at that. But we also look at how resilient the households and businesses and the financial sector are to those things. So, we look at that mainly from our financial stability perspective and we think that there’s a lot of resilience out there. Banks have high capital, and households are actually overall, not all households but in the aggregate, households are in pretty good shape financially these days. So, that’s how we think about that. We also, we look at overall financial conditions, and you can’t just take equity prices, you’ve got to look at rates too, and that represents a tightening in conditions with higher rates. So, overall financial conditions are probably still somewhat accommodative, but it’s a mixed bag.”
The other thing Karsan mentioned (and I’m taking liberties in paraphrasing): “what we call ‘money’ is actually leverage, loans. A lot of new collateral has been created in the system, and it functions in a self-reinforcing way, in both directions.” He implies that the Fed and admin need to pump up liquidity to keep things going, and off-handedly assigns a multiplier of 4 to 6 per 1 unit of ‘liquidity’. The real question in my mind, is what happens at the margin. Does extra liquidity, if it even comes, pump financial assets, inflation, or both?
It gets to the core issue of what might be called “resilience”. Household resilience might be framed in terms of balance sheets, shelter costs as a percent of income, the unemployment rate, amount and risks of government transfer programs. I’ll just cite Household Net Worth, which is at a new high, as shown by the chart below. The slope of the ascent has significantly steepened since covid. A lot of that Net Worth is driven by financial assets/corporate equities. How much of that is resilience, and how much represents a risk that we’ll return to the 2011 to 2019 trendline? If that were to occur, my eyeball estimate is that it would lop off about $30 trillion in assets, equal to a year of GDP. Is this something to worry about?

https://www.federalreserve.gov/releases/z1/dataviz/z1/balance_sheet/chart
https://www.federalreserve.gov/releases/z1/dataviz/z1/changes_in_net_worth/chart
I’ve added a couple of links from the Fed, the top one is pretty much a replica of the St Louis Fed chart presented above. The bottom shows CHANGES in net worth, with the biggest factor being corporate equities. On Monday NVDA alone shed $600 billion in value. On Friday AAPL had a range of $14 from a high of 247.19 to a low 233.44. That’s about 6% of the close at 236. The final close was only down 1.59, but the range represented > $200 billion swing.
I am not drawing conclusions from the above, apart from sharpening focus on risk management.
Adding a couple of charts below, as I spent some time looking at the Fed’s balance sheet and mortgages. The spread between the Bankrate 30y mortgage and the 10y treasury is now around 250 bps. In 2023 it was over 350 bps and last year it was mostly around 290. From 2010 to 2019 the spread ranged from 100 to 225. (Lower chart). The top chart is MBS holdings on the Fed’s balance sheet. Waller had said in a speech that he didn’t think the Fed should own any MBS. Current holdings are $2.2 trillion. In general, balance sheet run-off periods have lasted a bit over two years. Then the next crisis hits. Current run is about 2.5 years.
News this week,
Monday ISM Mfg, Tuesday JOLTS, Durables. Wed, ADP, ISM Services. Thud, Claims and Productivity. Friday NFP expected 170k. Powell to testify before the House on Feb 12.

| 1/24/2025 | 1/31/2025 | chg | ||
| UST 2Y | 426.9 | 423.0 | -3.9 | |
| UST 5Y | 442.8 | 436.4 | -6.4 | |
| UST 10Y | 462.1 | 457.1 | -5.0 | |
| UST 30Y | 484.7 | 482.2 | -2.5 | |
| GERM 2Y | 229.0 | 211.9 | -17.1 | |
| GERM 10Y | 256.9 | 246.0 | -10.9 | |
| JPN 20Y | 190.0 | 192.6 | 2.6 | |
| CHINA 10Y | 166.4 | 163.0 | -3.4 | |
| SOFR H5/H6 | -26.0 | -33.5 | -7.5 | |
| SOFR H6/H7 | 7.5 | 5.5 | -2.0 | |
| SOFR H7/H8 | 8.0 | 7.5 | -0.5 | |
| EUR | 105.04 | 103.63 | -1.41 | |
| CRUDE (CLH5) | 74.66 | 72.53 | -2.13 | |
| SPX | 6101.24 | 6040.53 | -60.71 | -1.0% |
| VIX | 14.85 | 16.43 | 1.58 | |
| MOVE | 86.75 | 91.76 | 5.01 | |
Longer maturities accepting the idea of lower yields
January 31, 2025
******************
–Q4 GDP advance estimate was just 2.3%. Today, PCE prices are released:
m/m expected 0.3 from 0.1
Core 0.2 from 0.1
Yoy 2.6 from 2.4
Core 2.8 from 2.8
–Odds for an ease in March declined slightly. FFJ5 settled 9571.5, down 1.5, around 20%, and SFRH5 settled 9575, down 1. However, deferred contracts rallied, with SFRH6 +3.0. The one-yr H5/H6 calendar settled at a new recent low of -38, and M5/M6 at a new recent low -21 (9592/9613).
–Trump rattled the market late in the day with tariff announcements on Mexico and Canada, but ESH5 settled 6099.25. +31.75. Gold hit a new all-time high, with GCJ5 2845.20. SPX has nearly erased the DeepSeek sell-off that started the week. DJIA never even noticed. AAPL bounced around after yesterday’s results, but appears to have resolved higher, now over 245.
–2/10 treasury spread eased a couple bps to 31.3, with 2s -2.7 to 4.197 and 10s -4.7 to 4.51. Straddle prices eased across the board. TY open interest up another 55k to 4.97m. Though futures price action was fairly muted, TYH5 settled +9 at 109-07+.
–Lacy Hunt on Thoughtful Money cites a study by Barry Habib noting that shelter inflation is significantly overstated. I do not know details, though a friend said Habib has been tracking the basis between Corelogic rent and CPI rents for some time. Newly signed leases are indicating meaningful deceleration. Implication is, of course, that CPI may already be at the Fed’s target. FNMA (Fannie Mae) had spent last year between 1 and 2. In December it was around 2.75, now near 6 on expectations of privatization.
FOMC just hawkish enough to flatten curve slightly
January 30, 2025
******************
–I thought the FOMC press conference leaned slightly hawkish, but a client read it the other way, and I skimmed a couple of summaries noting that the statement was hawkish, but Powell walked it back. I would say the market supported the idea of a Fed on hold. At futures settlement, the curve had flattened. SFRM5 -3.5 (9591.5), M6 -2.5 (9609.5), M7 -1.0 (9602.5). In treasuries the 2y was up 2.1 bps to 4.224%, 10s +1.1 at 4.557% and 30s unch’d at 4.788%. April FF, which price odds for a March cut, settled 9573.0, down 2 on the day, i.e 28% chance of 25bp ease.
Initial focus was on this change in the statement:
From DEC:
Inflation has made progress toward the Committee’s 2 pct objective but remains somewhat elevated.
Yesterday:
Inflation remains somewhat elevated.
–In the press conference, Powell said the Fed is “… not highly restrictive, but meaningfully restrictive.” Said another way (which he did) funds are still above neutral, and “inflation remains somewhat elevated.”
–With respect to the new administration, he cited uncertainty about four things: tariffs, immigration, fiscal policies, and regulatory policies.
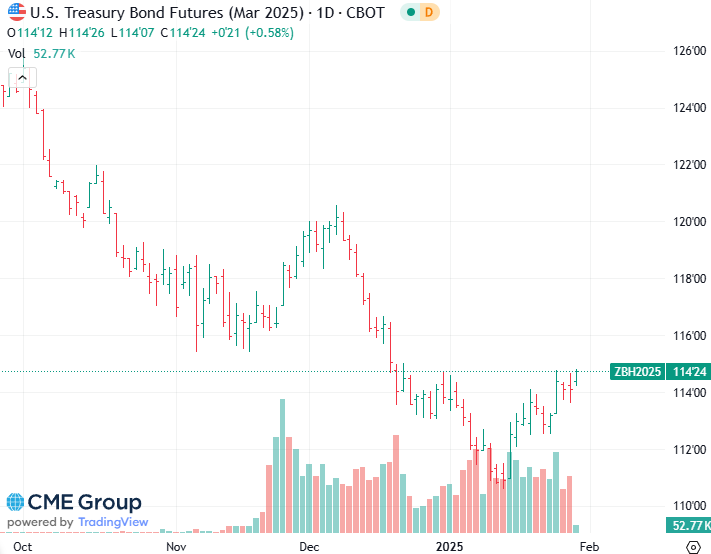
–I focused on USH5. Pre-Fed it had been hugging highs at 114-13. Post-Fed sold off, settling 114-03. Late in the electronic session, right back to 114-12. This morning the contract is testing the neckline traced out at recent highs. Hi on 12/31 114-23. Hi on 1/27 114-25. Now 114-23 (high this morning 114-26). This contract wants to go higher.
–Perhaps high PCE prices (released tomorrow) could change the mood, but I sort of think low numbers could cause all treasuries to rally, and marginally higher data will only serve to solidify the idea that the Fed’s not moving, which could cause more flattening and buying of the long end.
–One last thing: TY open interest added another 52k yesterday to 4.936m (on Dec 20 was 4.434m). A lot of buying in TY wk5 109.5 calls (paid 10 outright >10k and paid 7 for 109.5/110cs for 40k). These expire tomorrow, 109.5c settled 3 with OI 78k.
–Today Q4 GDP expected 2.6% (tho ATL Fed was revised down to 2.3%). Jobless Claims 225k.
..
FOMC Day
January 29, 2025
******************
–Boring day in rates as stocks rebounded from yesterday’s pullback (related to NVDA plunge/DeepSeek). Ten year yield +2 to 4.546%. In SOFR, all contracts from SFRU5 thru SFRU9 were -1.5 to -2.5. Vols softer. Late seller 6k TYH5 107.75/110.225 strangle at 32. Settled 32 down 3 on the day vs TYH5 settle 109-01.
–Today is the FOMC decision. There is no SEP (projection table) for this meeting, but there is a press conference. At the Dec FOMC, 2025 estimates for PCE and Core Prices were jacked up to 2.5% from 2.1% and 2.2% respectively. In the press conference, Powell said several times that the FF rate is now much closer to neutral. Hammack was the dissenter, and preferred no cut at that time. Since then, the economy appears to remain on firm footing. The Atlanta Fed GDP Now was just revised up to 3.2% for Q4 2024, and the NY Fed’s GDP Nowcast is 3.0% for Q1 2025. The latest yoy CPI was 2.9% and PCE prices, which are released on Friday, are expected 2.5% yoy with Core 2.8%. This little preamble is only to assess Powell’s posture at the press conference. If I had to guess, I would think he would lean slightly hawkish despite, (or maybe because of) Trump’s vocal wish for lower rates.
–MSFT. META and TSLA report today. AAPL tomorrow.
–From Alyosha/ market vibes: “DeepSeek offers its services at a significantly lower price point. For instance, DeepSeek starts at just $0.50 per month for its subscription, while ChatGPT’s premium models begin at $20 per month. This makes DeepSeek’s operational cost for users approximately 40 times cheaper in terms of monthly subscription fees.”
–(RTRS) Doomsday Clock moves up one second to 89 seconds to midnight — its closest ever to the 12 o’clock apocalypse point.
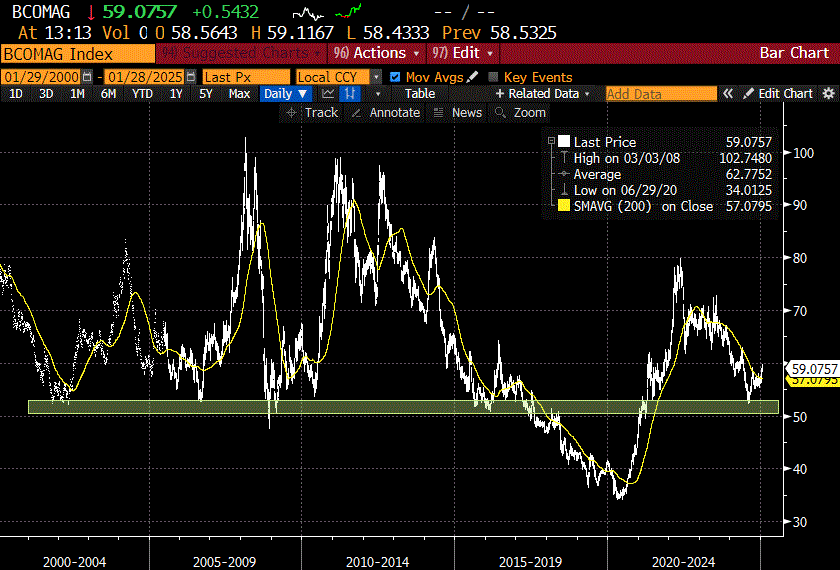
–Below is the BBG Commodity Ag sub-index. Soybeans and products, Corn, Wheat, Sugar, Cotton, Coffee. Same price as it was 20 years ago.