
FIVE PCT
October 19, 2023
******************
–Tens appear to want to test 5% today as 20’s hit 5.25% yesterday before the auction. According to St Louis Fed the high ten-year yield in 2006 was 5.20% which followed the Fed’s 2004-2006 hiking campaign. Tens now 4.955% vs ending at 4.90% at yesterday’s futures settlement.
–Does this have something to do with it? From the Kobeissi Letter, “Total US debt has grown by ~$22 billion PER DAY for the last month… Since the debt ceiling “crisis” ended, total US debt is up over $2 trillion.” Sort of makes the $5 billion or so a month of supposed student loan debt pay-off look inconsequential.
–Powell speaks at noon today at the Economics Club of NY.
–While the Nov 1 FOMC has been taken off the table in terms of a hike, the December 13 meeting is showing increased odds. For example, yesterday FFX3/FFF4 spread settled 9 and had been 9.5 bid late in the day. (9465.5/9456.5). The Jan contract alone is 5.435%, 10.5 bps above the current EFFR…almost halfway there. However, in SOFR, Dec3/March4 spread is -6 (9452.0/9458.0). So, leaning for an end of year hike followed by bias for ease. Rarely does the market have perfect timing. Actually, on the FF curve both FFF4 and FFJ4 settled 9456.5, so at this point, the market leans toward ease AFTER Q1.
–Attached chart was from yesterday, 20yr yield at 5.25% exactly at lower band of FF target range, and just above the 2yr. A positively sloped treasury curve helps the banks…but not if long rates are so high that bankruptcies jump and lending is curtailed.
What I CAN observe is my bond position disintegrating
October 18, 2023
******************
–Rate futures imploded to new lows on stronger than expected Retail Sales +0.7 m/m vs +0.3 expected with the previous month revised up 0.2 to +0.8%. As a result, Atlanta Fed GDP Now was jacked up to 5.4% from 5.1%. Even Barkin said that his contacts don’t paint the same strong picture of economic activity…if the Fed guys don’t trust the data then we have problems. Of course, Barkin was a lot more nuanced in his comments, mostly saying that the wealthy have seen higher equity & housing prices, and aren’t negatively impacted by variable cost debt (perhaps just the opposite) and are spending apace. Maybe that means the Fed has to target lower stocks?
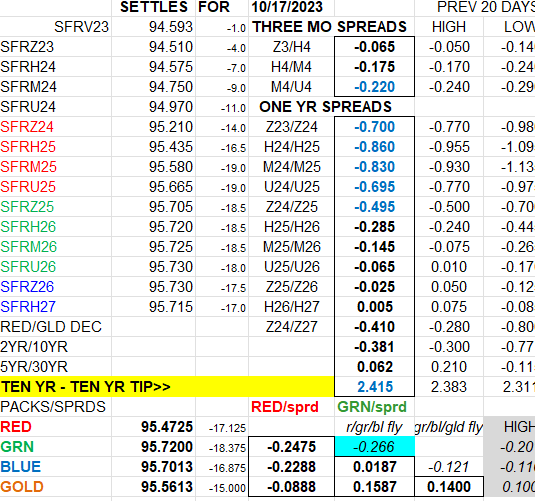
–New highs in all near 1-yr calendars with SFRH4/SFRH5, the most inverted 1y calendar on the strip now at -86 (9457.5/9543.5), indicating a chance of only about 3.5 Fed cuts over that year. SFRZ4 was the most heavily traded contract with 560k in volume. Like almost all SFR contracts, it settled at a new contract low 9521.0, down 14 on the day. On May 11, as the Fed was still trying to contain fallout from regional banking failures, SFRZ4 settled 9723.5, over 200 bps higher than it is now. (And the current price still implies a few cuts next year).
–WSJ’s Nick Timiraos tweets that Barkin was once asked a question about the Neutral Rate. “Before answering, he offers this preamble about the neutral rate: ‘An animal in the wild that everyone talks about but no one has ever seen.'” A perfect lead-in for today’s WSJ headline: Wall Street’s Latest Obsession is an Unknowable Number. ‘The debate centers on the unobservable “term premium” that models say is surging.’
No sh-t. The models say that, eh? When they come out with sharpened pencils spreadsheets to quantify all the pricing components of a given ‘security’, you can be pretty sure that actual prices are getting away. Just how do you price fear? I guess high implieds give a little indication. But what really needs to be priced is potentially massive open-ended losses. And it feels like that variable is eating at the perimeter of not only markets, but the total geopolitical structure.
–Today’s news includes Housing Starts and the Fed’s Beige Book. 20yr auction today; the yield was 5.15% at yesterday’s future settlement time. Biden continues to request huge sums for Ukraine, and whatever one thinks of his policies, bond holders don’t like it.
Wall Street’s Latest Obsession Is an Unknowable Number
The debate centers on the unobservable “term premium” that models say is surging.
Fast hikes, slow ease. Isn’t that backwards?
October 17, 2023
–Today’s news includes Retail Sales, expected 0.3% from 0.6 last. Ex-auto and gas 0.1% vs 0.2%. Industrial Production 0.0 from +0.4%.
–New high Monday in SFRH4/SFRH5 one-year calendar at -95.5 (9464.5/95.60) up 3.5 on the day. This is currently the most inverted 1-yr on the curve. In early Sept the 1-yr spreads were around -120 to -130. There are now no spreads implying more than four 25 bp eases over a given year. The Fed has successfully tamped expectations of aggressive easing out of the market even as many officials have signaled a November skip (yesterday Harker again said that the Fed is likely done with hikes). Today, Williams, Bowman, Barkin and Kashkari. Bowman said last week that more hikes might be necessary, but the majority of speakers suggest a wait-and-see approach. From July 2022 to July 2023 the Fed hiked 300 bps from 2.25-2.5 to 5.25-5.5. Current spread pricing implies comparatively glacial easing. However, out of the money calls still reflect a high cost to insure against rapid easing. For example, SFRH4 9662.5 calls, just five months until expiration and 200 bps out-of-the-money, settled 4.5.
–Twenty year auction is tomorrow. At the time of futures settle, cash 2y was 5.094% and 20y wi was 5.08/5.075. 20y will likely become the highest point on the curve. Ten-year yesterday 4.708 (+8.1 bps) and 30y 4.863 (+8.6) as flight to quality bids unwound.
Thursday’s extremes are guideposts
October 16, 2023
–USZ3 bond contract is under pressure this morning, trading 111-29 from Friday’s settle of 112-25. Thursday was a big day last week, with longer end maturity contracts making new highs early and then plunging after a weak 30y auction. Continued supply is weighing on treasuries. TY, US and WN all had large outside range days on Thursday, and closed near the lows. In my opinion, a close below Thursday’s lows ( 107-04 in TY, 111-07 in US, 115-06 in WN) will mean a move to much higher yields. Important events will be tomorrow’s Retail Sales and Wednesday’s 20y bond auction. Closing above Thursday’s highs may well signal the end of the bond bear market. (TY 108-16, US 114-10 , WN 119-14). This morning the 20y yield is 5.05%, very close to being the highest point on the treasury curve (2-yr currently 5.07 and 30’s are 4.84). By Wednesday afternoon 20s will likely be the highest point.
–There are a few Fed speakers this week, but in general the message is: financial conditions have tightened, the long end and stronger dollar are doing the Fed’s tightening job, we can afford to wait in the larger context of risk management.
Barbaric Relic
October 15, 2023 – Weekly comment
***************************************
One hundred years ago John Maynard Keynes wrote, “In truth, the gold standard is already a barbarous relic.” (page 172, A Tract on Monetary Reform). Keynes was talking about the gold standard, but over time gold itself has been tagged as a relic.
Here are a couple of clips from the same treatise:
Consequently gold now stands at an “artificial” value, the future course of which almost entirely depends on the policy of the Federal Reserve Board of the United States. The value of gold is no longer the resultant of the chance gifts of Nature and the judgment of numerous authorities and individuals acting independently.
And – most important of all – in the modern world of paper currency and bank credit there is no escape from a “managed” currency, whether we wish it or not; convertibility into gold will not alter the fact that the value of gold itself depends on the policy of Central Banks.
Another tie-in to this theme is the book, Barbarians at the Gate, which documents “The fall of RJR Nabisco”. This story covers the LBO craze of the 1980’s which saddled the target company with unmanageable debts. (Also made into a great 1993 movie).
The focus on gold this week is a result of barbarism in Israel/Gaza, leading to a jump of 3.4% in spot gold on Friday to $1933/oz, just above the 200 dma. On the week gold gained $100. Of course, in terms of commodity rallies this one is tame for now.
The Keynes commentary is perhaps a precursor to Friedman’s “Inflation is always and everywhere a monetary phenomenon…” and it’s clear that Federal Gov’t spending is linked to monetary growth. The core problem is beginning to resemble the same one RJR had: huge Federal Government debts without enough cash flow for smooth servicing. An LBO of the Federal Gov’t.
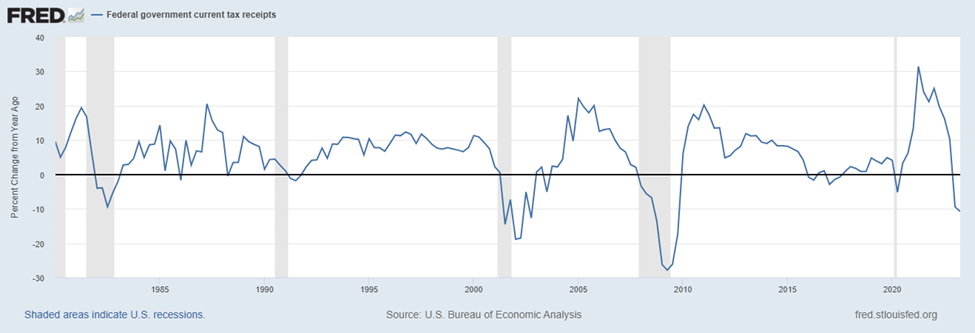
There have been a lot of stories about the size and growth of the Federal deficit, and the chart below gives a sobering view of the year/year percentage change in Federal tax receipts. (Thanks YZ). In Q2 tax receipts were falling at a yoy rate of -10.8%. [chart is a bit hard to see so here’s a link https://fred.stlouisfed.org/series/W006RC1Q027SBEA# The link may take you to the “billions of dollars” setting, which needs to be edited for yoy % change]. By the way, the billions of dollars measure equals $2.8b, which seems insignificant in relation to Federal spending. When the growth rate of income severely lags the growth rate of spending, the difference is borrowed and the interest rate demanded should increase. A bullet point summarizing Waller’s comments last week says the same thing: “When the deficit is 6% with low unemployment, it’s hard to see that as sustainable. Clearly issuance has to have an impact on yields.”
What about the “real” yield?
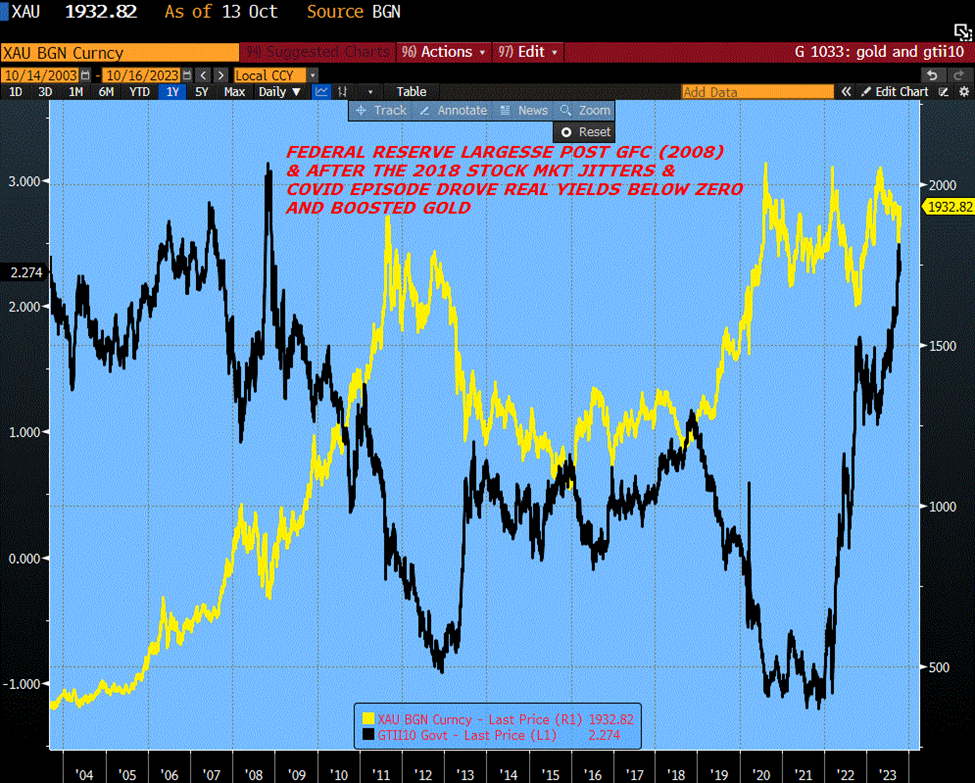
After the GFC the real rate, as portrayed by the ten year inflation-indexed note yield, went from over 2% (positive) to nearly 1% negative. As the next chart shows, gold surged. Again, after the stock market swoon in Q4 of 2018, and the Covid episode, the tip rate went from +1% to -1% and gold surged. Now the tip yield is near a new recent high at positive 225 bps. Gold is not pulling back. And THAT is the canary in the coal mine.
It’s often said that the real rate is a huge impediment to the gold price because gold has no yield. I have a small investment in a company run by friend Keith Weiner, Monetary Metals, that actually pays an interest rate on physical gold, with physical gold. I’m not saying that Keith’s company has single-handedly squashed the “positive real rates kill gold” narrative. (Or am I?). What I am saying is that rising nominal rates and a rising real rate coupled with a rise in the price of gold give an unsettling picture of the economic environment which is likely unfavorable to most financial risk assets. Perhaps the economic landscape was appropriately captured by Citigroup CEO Jane Fraser, who said, “September is always a busy month seeing clients, and I’m struck how consistently CEOs are less optimistic about 2024 than a few months ago.”
For a somewhat different view, I’ll cite James Fishback from an Axios article: “…the average duration for investment-grade corporate debt has doubled from four to eight years… companies are paying less in debt now than a year ago. US corporate net interest payments have fallen for the past five quarters, according to BEA data. At the same time, businesses are earning 4-5% on their cash holdings. Many companies have actually benefited from higher rates.” [Recession deferred?]
https://www.axios.com/newsletters/axios-macro-bf4a058b-5001-48d8-ae4f-c52c52e61bc2.html?chunk=0&utm_term=twsocialshare#story0
But maybe it’s not a different view. Current issues are driven more by government than by the corporate sector. Perhaps the rising gold price is a true reflection of that dynamic.
OTHER THOUGHTS/ TRADES
The curve flattened this week as officials continue to indicate that the Fed is on hold for the time being as financial conditions have tightened, but that rates aren’t being lowered any time soon. The 2/10 treasury spread went from -30 bps to -42 (5.05%/4.63%) as the flight-to-quality was more of an influence on longer maturities (despite poor auction results). This week’s 20y auction is on Wednesday, and it is at the high point of the curve outside of the 2y. 20y yield 4.963% on Friday. Not looking for stellar results on this one.
FFX3 settled 9465.0 (+5.5 on the week) or 5.35% vs Fed effective 5.33%. FFF4 settled 9459.0 (+4.0 on the week) further squeezing out perceptions of another hike prior to year end. FFF5 settled 9539.0 a spread of -80 to FFF4, indicating about 3 Fed eases over next year. This spread hit a recent low of -140 in August, so in the last two months the Fed’s higher for longer mantra has lessened the magnitude of perceived easing.
There were several SFRH4 call flies traded through the week, but I especially favor this one: SFRH4 9550/9600/9637.5 broken call fly bought for 1.25. Settled 1.5 (10.5/7.25/5.5). Max loss is premium paid. Breakeven is 9551.5 but on the upside any settle above the top strike makes 11.0 as the lower call spread is 50 and the upper is 37.5 wide. Max value of 50 occurs with the unlikely settled of exactly 9600. The 9550/9600/9650 c fly traded and settled at 1.0 and has the same max value at 9600, but a close above the upper strike will mean a loss of the initial premium spent.
********************************
Monetary Metals info at https://monetary-metals.com/ On twitter or X: @RealKeithWeiner
Also, for those from the CME floor, I saw a great movie this weekend by Mike Tamarkin’s (HWK) son, Blake Tamarkin! Poignant and funny treatment of an age-old story, fine acting, fabulous soundtrack, superb location shots in Chicago. Really impressive.
THIRD WHEEL. Watch for it at upcoming film festivals. I highly recommend it not just for the old floor community, but for all.
https://www.eventcreate.com/e/thirdwheel
| 10/6/2023 | 10/13/2023 | chg | ||
| UST 2Y | 508.1 | 505.2 | -2.9 | |
| UST 5Y | 474.8 | 464.2 | -10.6 | |
| UST 10Y | 478.3 | 462.7 | -15.6 | |
| UST 30Y | 493.8 | 477.7 | -16.1 | |
| GERM 2Y | 313.3 | 313.9 | 0.6 | |
| GERM 10Y | 288.4 | 273.7 | -14.7 | |
| JPN 20Y | 159.2 | 151.7 | -7.5 | |
| CHINA 10Y | 268.1 | 268.0 | -0.1 | |
| SOFR Z3/Z4 | -85.5 | -83.5 | 2.0 | |
| SOFR Z4/Z5 | -50.5 | -57.0 | -6.5 | |
| SOFR Z5/Z6 | 4.5 | -3.0 | -7.5 | |
| EUR | 105.90 | 105.11 | -0.79 | |
| CRUDE (CLZ3) | 81.28 | 86.35 | 5.07 | |
| SPX | 4308.50 | 4327.78 | 19.28 | 0.4% |
| VIX | 17.45 | 19.32 | 1.87 | |
https://delong.typepad.com/keynes-1923-a-tract-on-monetary-reform.pdf
We Won. (Just keep saying that to yourself)
October 13, 2023
–CPI a bit stronger than expected with headline m/m 0.4 vs expected 0.3 and y/y 3.7% vs expected 3.6%. The NY Fed is discontinuing its UIG (Underlying Inflation Gauge) perhaps after Nobel laureate was deservedly heckled for this ridiculous post:
–“Very little cost”… if you take out the price of necessities and ignore the gargantuan budget deficit. As Curly would say, “Is everybody dumb?!”
–Oh, also included in the “very little cost” is soaring long end yields, exemplified by a poorly received 30 yr auction. W/I was 4.802 and actual result was 4.837, a significant tail. USZ3 contract sold off aggressively and settled 111-15, down 1-29. It was an outside day with a lower close. At futures settle the 30y yield was 4.87%. I guess the mortgage market didn’t get Krugman’s memo as the 30-year fixed is still 7 7/8-8%. Red, green and blue SOFR contracts settled -9 to -10.5.
–Russell 2k futures also having a hard time digesting the “We won” scenario, dropping 39 points or 2.2% yesterday. It’s not quite at the year’s low, but the cash index was over 2000 in mid-summer and is now 1734. The small cap guys are wondering how to roll debt, or if they’re completely shut out of the market. Bank results this afternoon include JPM, C, WFC. I’m no bank analyst, but would suspect there will be some discussion of deteriorating credit quality and more stringent lending standards.
I’ve got an idea…
October 12, 2023
–CPI and 30y auction today. On y/y basis, CPI expected 3.6 vs 3.7 last and Core 4.1 vs 4.3. Social Security will reveal its COLA today, expected 3.2% for 2024, down from 8.7% last year and 5.9% in 2022. JPM, C and WFC report on Friday.
–Interesting bullet point from Waller yesterday:
When the deficit is 6% with low unemployment, it’s hard to see that as sustainable. Clearly issuance has to have an impact on yields.
–What’s the response from the braintrust at Treasury? Well according to a Barclay’s report (from a BBG piece in the morning):
Barclays predicts treasury is about to slow terming-out of debt. “Int rate strategists at Barclays said they expect the US Treasury to ‘slow the pace of terming out’ debt starting next month in response to a sharp increase in term premium and strong demand for bills.” …Slowing the treasury’s terming out could reduce term premium and flatten the curve.
–Oil high? Sell out of the SPR. Long rates high? Trim bond sales. Don’t have coal to heat the house? Burn the furniture. Idiots.
By the way, another gem from Yellen: She said the price cap on Russian oil had “significantly reduced Russian revenue over the last 10 months while promoting stable energy markets.”.(RTRS).
I guess we now characterize stable markets as selling Russian oil to India which is then purchased by Europe.
–The US curve did flatten aggressively yesterday, with 5/30 down to 13 bps from a new recent high of 21 on Tuesday. This, despite a 30 year auction today, which follows tailing results in both the 3y and 10y.
–I think the phrase, “This is going to end badly” is way overused and somewhat stupid, but appropriate here (and you can apply the last characterization to either the situation or the author regarding today’s missive).
–Large buying yesterday of SFRZ3 9468.75/9475/9481.25/9487.5 c condor for 0.25 (mostly) up to 0.5, about 50k. SFRZ3 9468.75/9481.25 c spread bought about 10k, synthetically from 0.65 to 0.75. SFRZ3 settled 9457.0. These trades require a strong expectation of ease in the former, and either that or an actual end-of-year ease in the latter.
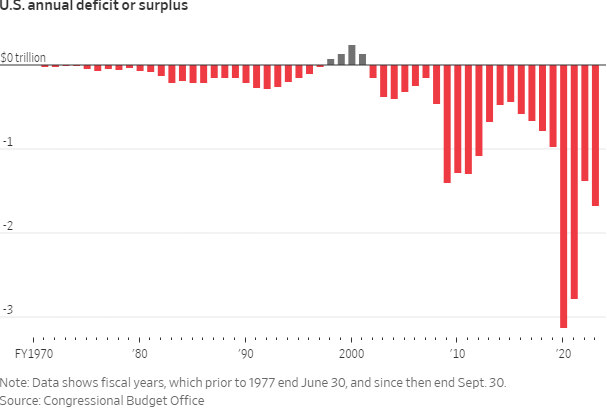
Here’s a stark picture of the US deficit from today’s WSJ. Below that is a Game of Trades post: Bank credit is now contracting. Has only happened once: in the GFC.
https://twitter.com/GameofTrades_/status/1712157718507901325/photo/1
bank credit contraction
..
A few notes
October 11, 2023
–Several Fed speakers have suggested that tighter financial conditions/higher long-end rates are mitigating the need for the Fed to continue raising short term rates (Logan, Jefferson, Bostic). Daly said yesterday that the nominal neutral rate is likely between 2.5% and 3% “2% inflation plus 0.5 real rate”. I would mention that the 10y inflation-index yield is currently 2.33%, so the 0.5 “real rate” is probably a lot higher. However, Bowman this morning said inflation above target may mean the Fed needs to keep hiking….before listing a string of financial system vulnerabilities (banks, CRE, the treasury market) that could keep the Fed on hold or tilt toward a lower policy rate. Risk assets have taken the message and continue the bounce from Monday morning. Surprisingly (in my opinion anyway) the long bond yield is also falling, down to 4.828% on Tuesday. I did mark 5/30 at a slight new high of 21 bps. If the Fed is done and Biden opens the checkbook for defense spending, then long end rates should have a near term floor.
–NFIB small business optimism, was released yesterday at 90.8. This isn’t a particularly big data point, but it’s still notable that it’s essentially at the same level as the beat low of the pandemic in 2020. I would personally place greater emphasis on NFIB than on consumer confidence surveys. Today brings PPI expected 0.3% and 0.2% core m/m. YOY expected 1.6% from 1.6% with Core 2.3 vs 2.2. Ten year auction (3’s tailed about 1.5 bps yesterday) and the FOMC minutes. Waller speaks again today, and given all the recent comments from Fed officials the minutes are likely meaningless. A lot has changed since Sept 20.
–FFF4 settled 9460 or 5.4% vs current EFFR of 5.33%. There are two meetings prior to this contract, Nov 1 and Dec 13, so obviously the current level leans toward the Fed being done. Implied vols pulled back from Monday’s strong closes. For example SFRU4 9625^ settled 104.5, down 3 from Monday’s settle and front SFRZ3 9456.25^ settled 17.75 from 20.25 with the future down only 0.5 to 9458. It feels like market makers are trying to paint marks lower, for example yesterday treasury straddles lost 1 to 1.5 64’s in the last five minutes prior to official settles.
The Fed is likely done
October 10, 2023
–Stocks shook off early weakness related to horrors in Israel/Gaza with SPX +0.6%. XLE (energy etf) gained 2.9%. ITA (defense) +4.45%. Individual names like Genl Dynamics soared even higher, +8.4%. Comments by both Dallas Fed President Logan and Gov. Jefferson indicated that tighter credit conditions and higher long-term rates may mean the Fed is done with short term tightening. FFX3 rose 4.5 bps to 9464 or 5.36%, just 3 bps higher than EFFR of 5.33% so around 12% chance of a Nov 1 hike. SFRZ3 rose 5.5 bps to 9458.5. SFRZ3 9475c settled 5.25 but traded as high as 6.0 late with futures printing 59. (This strike has the most Open Int of any SOFR call).
–Logan focused on term premium in the long end and the tightening of financial conditions (highlighted):
…in setting the stance of monetary policy, the FOMC needs to account for how that stance will translate to the broader financial conditions, including long-term rates as well as credit spreads and other factors, that influence economic activity…
Financial conditions tightened substantially in recent months. Much of the tightening came from movements in longer-term interest rates. Higher long-term interest rates have also contributed to equity price declines and dollar appreciation over recent months.
–Jefferson said he was mindful that the cumulative effect of past rate increases have not been felt, and said the Fed can proceed carefully amid a better risk balance, and will keep in mind the tightening impact of higher long-maturity yields.
–Implied vol in SOFR futures exploded higher with many straddles up 3 to 6 bps (partially due to the shift to higher strikes). For example, on Friday, SFRU4 9512.5^ settled 1.01 ref 9509.0. Yesterday the contract was up 16.5 to 9525.5. The 9512.5^ settled 105.0 and the 9525^ settled 107.5 (from 104.5).
–3yr auction today. Early, we get NFIB Small Business Optimism which was 91.3 last, expected 91.0. The low this year is 89.0 which was the lowest level since 2013. To put it in context, the Covid low in 2020 was 90.9 (about where we are now) and the high in late 2020 was 104. I think it could come in sub-89.
Safe haven flows muted so far
October 9, 2023
–Huge bounce off the lows in rate futures Friday, following larger than expected NFP of 336k (though Household survey was only +86k). This weekend’s attack on Israel and inevitable response caused flight to quality buying in treasuries, but does not appear to have changed the trend towards higher rates, at least for now. Inflationary aspects of expanding war, from oil to other supply shocks, and from increased US gov’t spending on weaponry will likely cap any rally in the long end. However, gold had an outside day at new lows and closed higher Friday. Only up about $20/oz this morning, but could easily benefit further from safe haven flows.
–This week brings inflation data and 3,10, 30y auctions. Dallas Fed’s Lorie Logan speaks on the economy at 9 this morning, Governor Jefferson at 1:30 (with Q&A).

