
Bunker Mentality
October 8, 2023 – Weekly Comment
**************************************
On September 21, the day after the last FOMC, the ten-year yield was 4.5%. On Friday I marked it at 4.78% at the time of futures settle, or more than ¼ % higher. The Bankrate 30y mortgage was 7.59% on Sept 20 and is now 7.93% (with many examples of quotes >8%). Several Fed officials mentioned tighter financial conditions as a substitute for more overt hiking by the Fed. DXY weakened slightly last week but was 105.36 on Sept 21 and 106.04 on Friday, an additional headwind for the global economy.
Another example of tighter/looser conditions comes in the form of oil prices. On Sept 27 CLX3 settled at a high for the year of 93.68. On Friday, just 7 sessions later, it settled 82.79. The Yom Kippur war of 1973 started 50 years ago in October. Oil more than doubled. I’ve seen several analysts say that the Hamas attacks on Israel this weekend are unlikely to play out like 1973. I think that’s wrong. The entire world seems to be in political disarray, and this proxy war will spread. I think the following snippet from Bloomberg’s Javier Blas is worth noting (For Oil, It’s Not 1973. But It Could Still Get Ugly):
5) Even if Israel doesn’t immediately respond to Iran, the repercussions
will likely affect Iranian oil production. Since late 2022, Washington has turned
a blind eye to surging Iranian oil exports, bypassing American sanctions. The
priority in Washington was an informal détente with Tehran. As a result, Iranian
oil output has surged nearly 700,000 barrels a day this year – the second-
largest source of incremental supply in 2023, behind only US shale. The White
House is now likely to enforce the sanctions. That could be enough to push oil
prices to $100 a barrel, and potentially beyond.
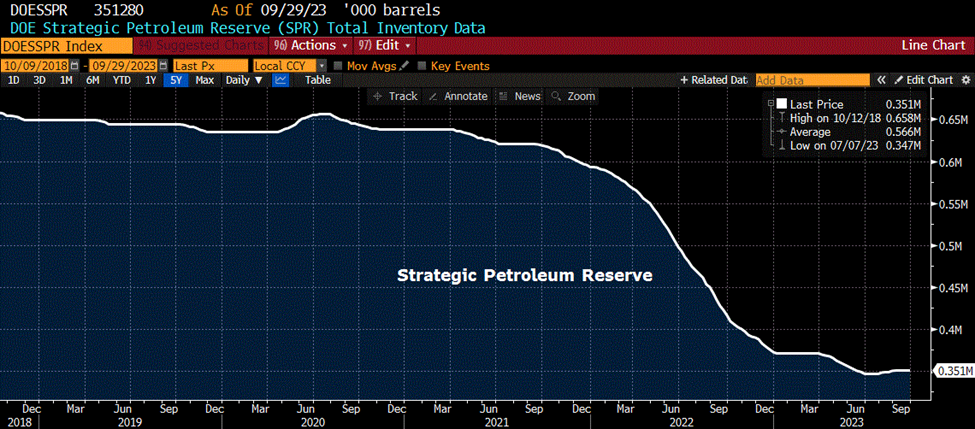
My inclination is to hunker down and shun risk assets. The US is going to support Israel which risks even worse budget implications. Blas says the US could still tap the SPR. As the attached chart shows, that well is running dry. In my opinion the implications are tightened credit conditions. I’m not sure of the ultimate response of long-end treasuries. There’s a natural flight to quality, but tame energy prices were widely credited with deceleration in inflation. That dynamic may change quickly. Supply remains a problem (both treasuries, too much, and oil, too little).
There’s a fair amount of news this week, including several Fed speakers, the most important of which are probably Logan on Monday and Waller on Tuesday. CPI on Thursday with Core expected 0.3% m/m and 4.1% vs 4.3% last y/y. FOMC minutes on Wednesday, but faced with uncertainty, the Fed is likely to hold fire at the Nov 1 meeting.
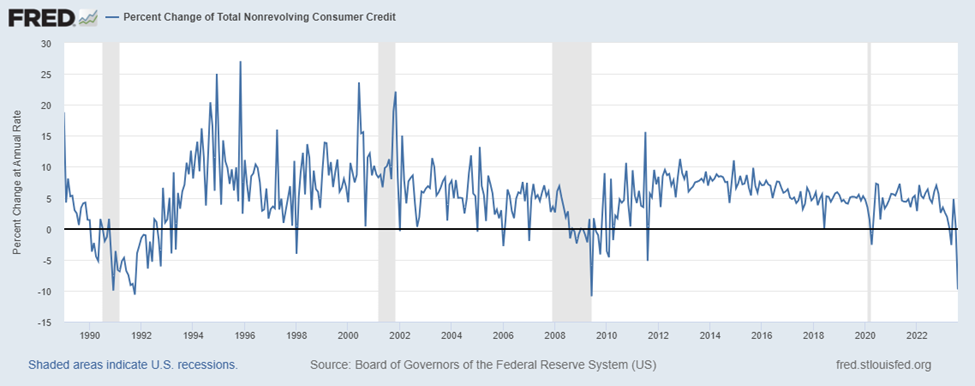
The consumer is showing strong signs of rolling over. Expansion of war is not going to help. Although I would guess this data might be revised, Friday’s plunge (-9.8% annual rate) in non-revolving credit is eye-opening. The outstanding level fell over $30 billion from $3.715T in July to $3.684T in August. As can be seen on the chart, since 1990 there are only two other examples of this magnitude of decline. (Revolving credit increased from $1.27T to $1.285T).
This is a big week for news and speakers:
Monday- Lorie Logan on the economy with Q&A
Tuesday – Bostic at 9:30 and Waller at 1:00
Wednesday – PPI expected +0.3 m/m with Core +0.2 m/m. FOMC minutes. Collins at 4:30
Thursday – CPI +0.3 m/m both headline and Core. Core expected 4.1 y/y vs 4.3 last
Friday – Harker at 9:00.
OTHER THOUGHTS/ TRADES
The 2/10 treasury spread easily posted a new high for the year, ending Friday around -30. A double bottom from around -105 in March and last June suggests a target of +25 which is also about halfway back from the 2021 high of +157 to the 2023 low of -108.
There was a fair amount of buying last week of SFRZ3 9475/9500cs for 1.375 to 1.5. Settled 1.25 (3.25/2.0) ref 9453.0. SFRZ3 9475c has 471.7k of open interest, the most of any SOFR call. Underlying SFRZ3 contract has 1.4m open. Current SOFRRATE is 5.32% and EFFR has been 5.33% since the July FOMC. An immediate ease would, of course, put these 9475 calls in the money. If there are no further hikes at the next two meetings and CERTAINTY of a 25 bp cut at the Jan 31 meeting, then SFRZ3 would likely trade around 9480. Of course, if an emergency develops, the first cut could easily be 50.
I am not recommending +SFRZ3 call spread vs 2QZ3 call spread, but just as a comparison, I would note that with SFRZ5 settling 9589.0, the 2QZ3 9687.5/9712.5cs settled 1.5, and it’s nearly 100 bps out of the money.
Above all, the Fed saves the banks. At Friday’s close of 40.57, Citi’s share price is below the March low. This week’s low was 39.81, a lower close than any price since the pandemic. Same thing with BofA at 26.07. US Bancorp at 31.86 is above the 2020 low, but in May it posted a low of 28.68, below the 2020 low. At the margin, the weakest players have a tendency to shake the entire system.
| 9/29/2023 | 10/6/2023 | chg | ||
| UST 2Y | 504.8 | 508.1 | 3.3 | |
| UST 5Y | 460.5 | 474.8 | 14.3 | |
| UST 10Y | 457.1 | 478.0 | 20.9 | wi 478.5/78.0 |
| UST 30Y | 470.8 | 494.0 | 23.2 | wi 494.0/93.5 |
| GERM 2Y | 320.3 | 313.3 | -7.0 | |
| GERM 10Y | 283.9 | 288.4 | 4.5 | |
| JPN 20Y | 147.7 | 159.2 | 11.5 | |
| CHINA 10Y | 268.1 | 268.1 | 0.0 | |
| SOFR Z3/Z4 | -86.0 | -85.5 | 0.5 | |
| SOFR Z4/Z5 | -63.5 | -50.5 | 13.0 | |
| SOFR Z5/Z6 | -1.0 | 4.5 | 5.5 | |
| EUR | 105.73 | 105.90 | 0.17 | |
| CRUDE (CLX3) | 90.79 | 82.79 | -8.00 | |
| SPX | 4288.05 | 4308.50 | 20.45 | 0.5% |
| VIX | 17.52 | 17.45 | -0.07 | |
Scotty: I don’t know how much longer I can hold her together
October 6, 2023
–Yesterday Daly gave a speech which made the pause case:
If we continue to see a cooling labor market and inflation heading back to our target, we can hold interest rates steady and let the effects of policy continue to work. Importantly, even if we hold rates where they are today, policy will grow increasingly restrictive as inflation and inflation expectations fall. So, holding rates steady is an active policy action.
Likewise, if financial conditions, which have tightened considerably in the past 90 days, remain tight, the need for us to take further action is diminished.
–The market continues to price the possibility of tightening, but less so. For example, FFF4 is 9458 or 5.42% vs Fed Effective 5.33. Meetings are Nov 1 and Dec 13. FFX3/FFF4 which had been bought for 6 in good size on Sept 21 in a play targeting the Dec meeting for a hike, settled yesterday at 3.5 (9461.5/9458).
–Today we get payrolls, expected 170k. Rate expected 3.7% from 3.8% and Avg Hourly Earnings yoy 4.3%. Bloomberg headline says it might be the last of strong labor data. In any case, there was decent upside buying yesterday, notably 7k 0QV3 9550/9575cs for 5.5 followed by 20k 0QV3 9556.25/9581.25 cs for 5.0. SFRZ4 settled 9545.0, call spreads settled 6.0 and 4.5, expiry one week from today. PPI and CPI on Wednesday and Thursday. 3, 10, 30 yr auctions next week as well.
–In 2006/07 there were a lot of crappy mortgages rolled into securities that garnered AAA status from the ratings agencies. Mortgages are no longer at the heart of financial stress, this time it’s the Federal Gov’t with gargantuan borrowing and Corporates that need to roll debt in the next year. However, I saw an interesting tweet citing Kirian van Hest: “Every single bond inside the largest Mortgage-Backed Securities ETF has been downgraded and nobody is talking about it.” I believe the ETF is MBB. I didn’t have time to listen to it, but here’s the link:
https://twitter.com/JG_Nuke/status/1709742289059246487
Econ commodities and rate spreads send a worrisome signal
October 5, 2023
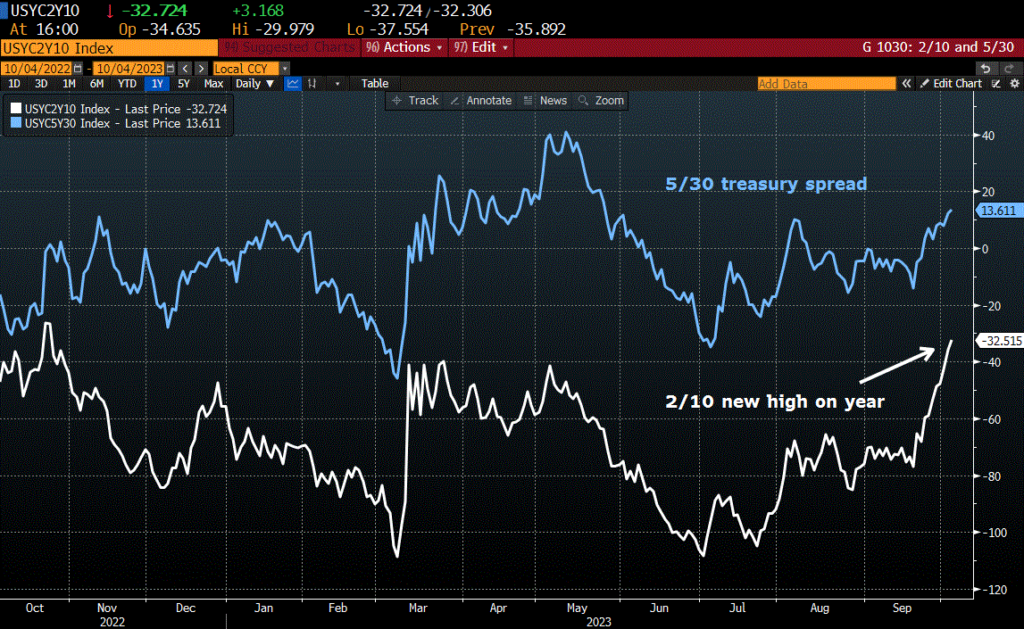
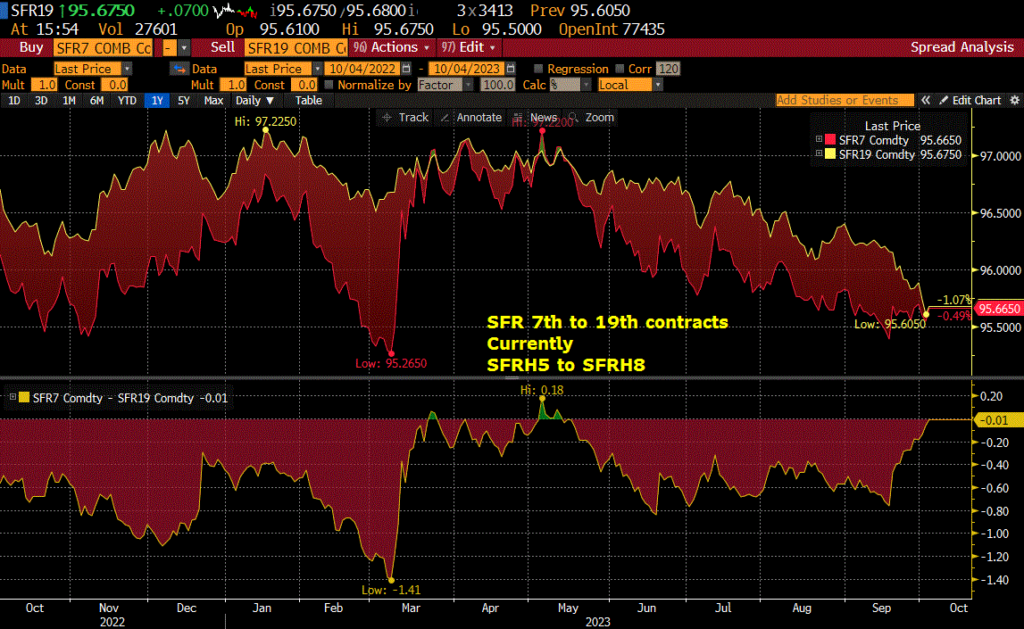
–Last Thursday Nov Crude touched $95/bbl. This morning it’s 83.50 after a 5 dollar plunge yesterday to 84.22. Along the same lines, Dec Copper is at a new low for the year, printing 3.5555 after having been over 4.25 in January. BofA has reported decelerating credit card spending for several weeks (Consumer Credit released late tomorrow). Equities had a small bounce yesterday and the curve bull steepened with the red pack +10.5 on the day. The 2y note plunged 10.2 bps in yield to 5.048%, whiles tens fell 7 to 4.735%. The spread between the two made a new high for the year at -31.3 [chart attached]. Also attached is a chart of the spread between SFRH25 and SFRH28; both contracts settled at the exact same price of 9566 or 4.34%. Every contract in between is at a higher price, with the peak SFRZ25 at 9591. What does it signify? First the lower rates in near contracts show a steadfast belief that the Fed’s going to be cutting, it’s just a question of how fast and how hard. The steepening from Z25 back is a more normal situation; as the Fed cuts the back end of the curve will steepen further. More than that, this spread, on a rolling 7th to 19th quarterly contract rolling basis is back where it was in the aftermath of the regional banking crisis in March. Of course, the spread could be wrong, but when coupled with evidence of declining prices in economically sensitive commodities, it points to a not so good landing.
–In terms of fast and hard, there was a new buyer yesterday of 50k SFRZ3 9475/9500cs which settled 1.5 vs SFRZ3 9456.0. Might just be protection, as this trade requires easing for the lower strike to be in the money.
–Jobless Claims today expected 210k. Kaiser Permanente strike announced yesterday is 75k employees. Several Fed speakers on the schedule, including Mester, Barkin, Daly, Barr. “We might need another hike but we expect the job market to remain resilient.” That’s my guess anyway. What might become important is if they talk about the theme of higher long-term rates choking off the need for Fed vigilance on the short end. Which would be a green light for buying the last reds and greens and selling more deferred, even though the spreads have already had strong moves.
Bond vigilantes
October 4, 2023
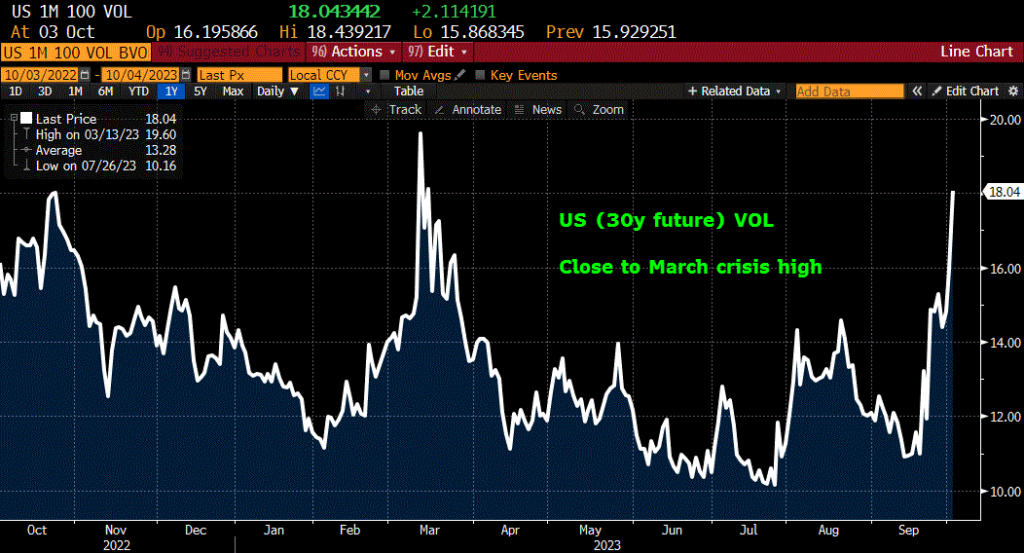
–We’re getting a change in leadership, no I’m not referring to McCarthy’s ouster as House Speaker, but in the rise of the long bond yield. And it’s not ‘leadership’ in a good way, which is an omen for our political class. The thirty yr yield soared 14.5 bps to 4.939% while the two-yr rose only 4.4 bps to 5.15%. A realtor friend (thanks RR) told me yesterday that Proper Rate had quoted him 8.125% on a 30y fixed mortgage. As the attached chart shows, US vol is approaching the panic high of March. TLT (long bond ETF) has exploded in volume on new lows in price.
–Almost all SOFR calendar spreads made new highs. SOFR pack changes: Whites -0.75, reds -5.625, greens -10.75, blues -12.75 and golds -13.0. For the first time since May (in the aftermath of the regional banking eruption) the red pack to gold pack closed postive. However, in May the packs were just above a 3% yield as the market perceived a robust Fed put which would lead to rapid rate cuts. Currently the red pack (2nd year forward) settled 95.58875 and the gold pack (5th year) settled 95.57875, so both around 4.4%, about 100 bps lower than the current Fed Effective rate of 5.33%. New highs in 2/10 treasury spd at -34.5 and 5/30 at +13.6.
–$/yen pulled back sharply from 150 yesterday on suspected intervention, but FT reports that Japan spent $12.7b today buying JGB’s to cap yields that have jumped to the highest in a decade. 10y JGB above 80 bps. JPY went as low as 147.43 yesterday but is now back above 149.
–The question now is what stops it. Markets have started Q4 by becoming increasingly untethered. As a small example, HYG (hi yield ETF) was down 1% yesterday and closed at a new low for the year. VIX is around 20, though in March it ticked to 30. It’s at times like this when the two words ‘counterparty risk’ start to pop up more frequently. At the end of 2018 it was the Fed pivot that turned things around. But how is the Fed going to address wealth disparity and climate change without making everyone poor? Just joking of course…
–Payrolls tomorrow as Kaiser Permanente faces a strike by 75000 employees.
From 60/40 to 0/100 and a long vacation
October 3, 2023
–New highs in treasury yields. Tens up 11 bps to 4.681% and 30s +8.6 to 4.794%. Additionally, the 10y inflation-indexed yield rose to a new high 2.334%, a level last seen in 2008. As of this writing TYZ and USZ remain pinned to yesterday’s lows, with TYZ3 107-07 (-3.5) and USZ 112-07 (-5). Dollar/yen is 149.85, awaiting intervention, while DXY is holding around 107. FFX3 settled 9460 (5.40%), down 3 on the day with heavy volume of 188k and an open interest increase of 48k. Hedging against a Nov 1 hike.
–Interesting tweet from David Dierking: Over past 6 trading days, the S&P 500 is down 1% and the utilities sector is down 11%. The last time that utilities underperformed by 10%+ while the S&P 500 was negative over a six day span? Never over the past 25 years.
–YTD SPX is up a bit over 12%. The three-month bill is around 5.5%. Has to be pretty tempting to shut down the equity portion of the portfolio, take the bill yield and glide into year-end in Q4. BofA and Morgan Stanley both made new lows for the year yesterday. Gunjan Banerji posts a tweet: BofA has a chart of rates going back to “3000 BC”. Sounds like BofA is looking around for historical anomalies that will explain correlation breakdowns of bullet-proof hedging strategies that didn’t quite work out this time. “It’s quite like the environment 970 years ago…”
–ISM Mfg yesterday a bit stronger than expected at 49.0 vs 47.9 expected. Today JOLTs forecast at 8808k vs 8827k last.
Can Talyor Swift keep the economy humming forever?
October 2, 2023
–A couple of morning headlines might give the idea that bonds are finding support:
Reuters: Eurozone factory activity stuck in steep downturn
FT: Asia faces one of the worst economic outlooks in half a century, World bank warns.
But…WSJ: American’s still spend like there’s no tomorrow. [Can Taylor Swift keep this economy humming forever?]
And…Congress averted a shutdown in order to keep the US Gov’t open. TYZ3 is currently printing 107-20, -14, nearing new lows.
–Late Friday there were a couple of large put buys: TY wk2 106.25p 8 paid 10k and TY wk2 106 put, 7 paid 10k, both new, settled 8 and 6 ref 108-02. Expire Oct 13. Just prior to those buys were a couple of large call purchases: +20k TYX 110/112cs for 11 (settled there) and +20k TYX 111c for 7. With the government open, NFP will be released Friday.
–Powell and Harker will participate in a roundtable discussion at 11:00. This morning ISM Mfg expected 47.7 from 47.6 last, with prices 48.6 expected from 48.4.
Parallels
October 1, 2023 – Weekly Comment
**************************************’
Just a few charts and thoughts this week.
Treasury yields made new highs, led by longer maturities. On Thursday, the 20yr poked just above 5% but came back down to end the week at 4.90%. Similarly, the 30yr popped above 4.80% but ended near 4.70%, up 19 bps on the week. Using the w/I from last week, the 2yr note ended down 2 bps to 5.048%.
What was interesting about Thursday is that even though bonds were posting new high yields (high since 2011), SPX remained above Wednesday’s low, so there was a small divergence. On the week SPX was only down 0.7% to 4288. The fact that Congress was able to kick the can a short distance down the road with temporary legislation to keep the government running may be viewed favorably, but overall price action in equities remains weak, with a poor close on Friday.
Below is a chart comparing general patterns from 2007 with now. In March of 2007 Bear Stearns revealed problems with their mortgage funds; they were essentially marked down to zero. In March of this year SVB and a couple of other regional banks were marked down to zero. Stocks sold off in both events but soon recovered early March highs.
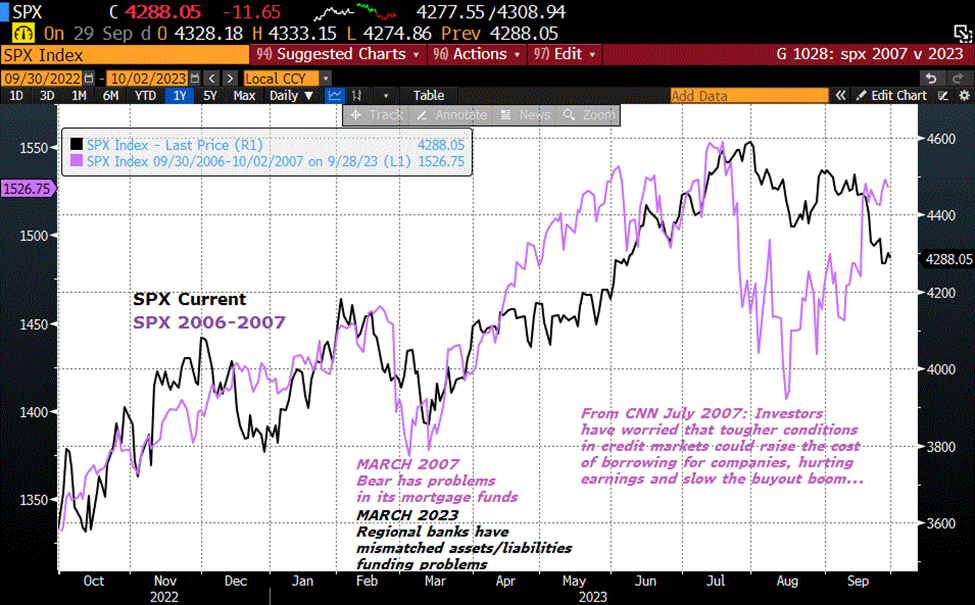
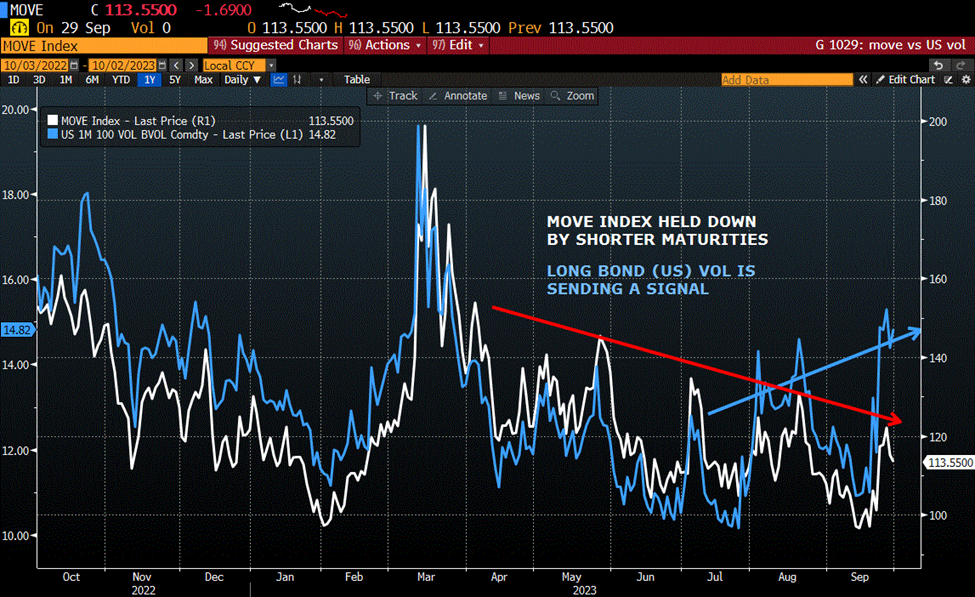
In July of 2007, SPX suffered a sharp drop. CNN Money attributed the move to tough conditions in credit markets. This year SPX put in a recent top at the end of July. It has been a much more gradual decline since then (as compared to 2007) but underlying conditions are similarly suggestive of a much more difficult environment for companies to roll debt. Spreads have not really blown up, but I would argue that the surge in long bond implied volatility to the highest levels since March indicates that broader problems in credit markets are around the corner. (I marked USZ vol just above 15% on Friday; USZ3 114^ settled 5’20). NOTE: The MOVE index does not give the same warning, because it is comprised of volatility levels across the treasury curve. In fact the MOVE has posted successively lower highs in late May, July, August and Sept. (chart at very bottom).
The first chart doesn’t show it, but the ultimate top in 2007 came on October 11. Surprisingly, after the sharp drop in July, the index came back to make a new high…and then began a painful slide. You’ll notice that in 2007 the swoon in mid-August did not quite take out the March low. That low was taken out in January. This year the March low was 3809. With SPX ending the week at 4288, we’ll need a decline of another 11% to reach the March low.
It felt like the big move this week was the curve. However, the chart of 2/30 below doesn’t really signal a momentous change in trend, even though the spread gained over 20 bps. Rallies in the curve are typically associated with Fed easing or the strong expectation of a looser central bank.
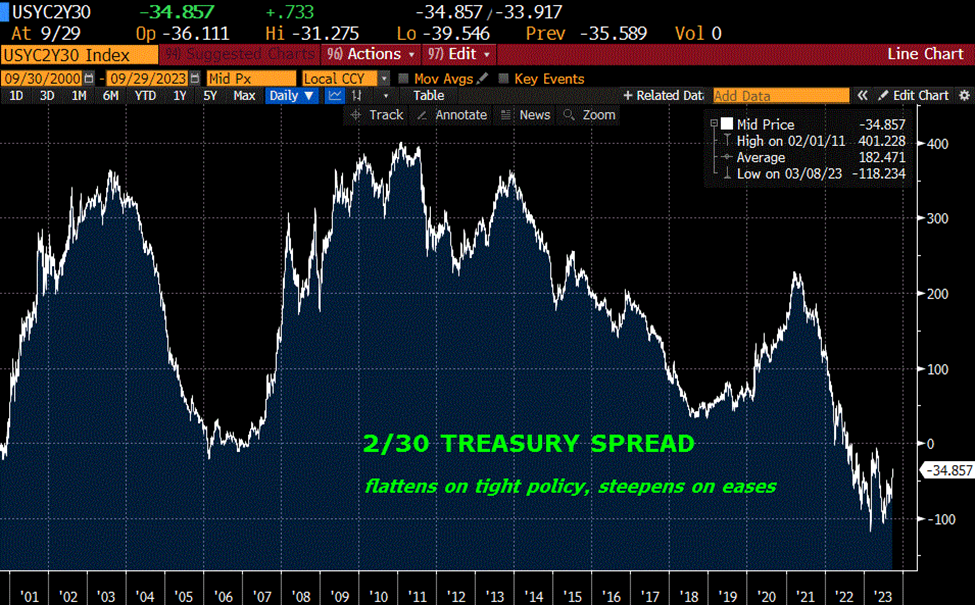
This time, the Fed is trying to project a harder line in the fight against a possible resurgence in inflation expectations. It’s not typically the case that bond yields rise aggressively in the context of monetary restraint, but that’s where we are now, and most bets are centered around 1) how long before something breaks 2) how has the perception of the Fed put changed? Will the Fed ease rapidly or grudgingly?
One last chart is a long term $/yen. The 150 level was tested this week. The 10y JGB hasn’t been this high in yield since 2013 (76 bps). The 20y JGB ended at 1.48% and the 30y at 1.73%, also both new highs. Higher costs for capital globally and a stronger USD don’t bode well for long-dated US assets.
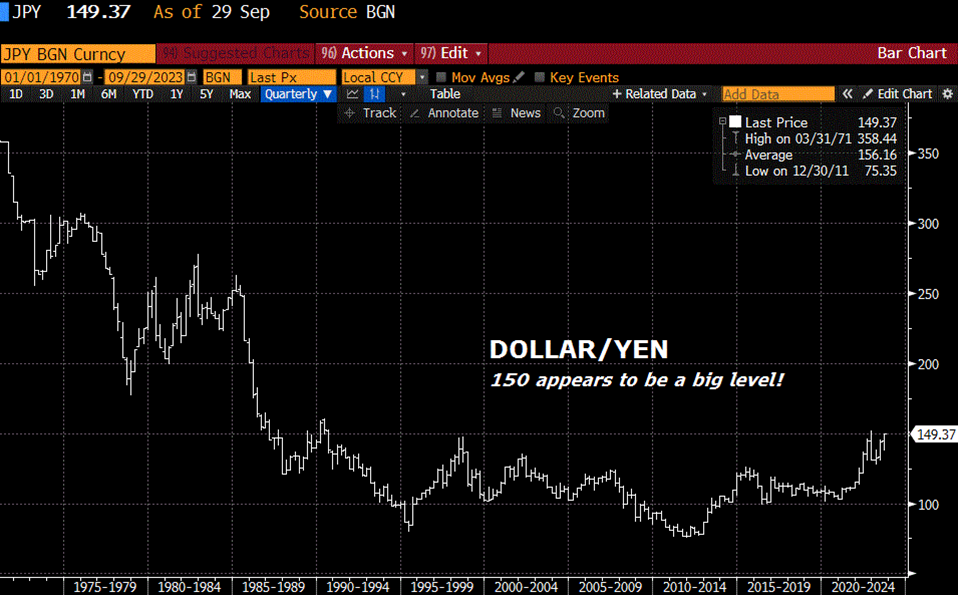
Chart below is MOVE vs US vol
| 9/22/2023 | 9/29/2023 | chg | ||
| UST 2Y | 506.7 | 504.8 | -1.9 | |
| UST 5Y | 456.7 | 460.5 | 3.8 | |
| UST 10Y | 443.6 | 457.1 | 13.5 | |
| UST 30Y | 451.8 | 470.8 | 19.0 | |
| GERM 2Y | 325.9 | 320.3 | -5.6 | |
| GERM 10Y | 273.9 | 283.9 | 10.0 | |
| JPN 20Y | 144.9 | 147.7 | 2.8 | |
| CHINA 10Y | 269.2 | 268.1 | -1.1 | |
| SOFR Z3/Z4 | -82.5 | -86.0 | -3.5 | |
| SOFR Z4/Z5 | -68.0 | -63.5 | 4.5 | |
| SOFR Z5/Z6 | -8.5 | -1.0 | 7.5 | |
| EUR | 106.45 | 105.73 | -0.72 | |
| CRUDE (CLX3) | 90.03 | 90.79 | 0.76 | |
| SPX | 4320.06 | 4288.05 | -32.01 | -0.7% |
| VIX | 17.22 | 17.52 | 0.30 | |
Capitulation in reds
September 29, 2023
–Large reversals yesterday. Back end of the curve steepening. 2/10 high of the year is around -40 and now around -47 (getting close) though that’s partially due to new 2y and the roll (i.e. the old 2y ended at 5.125 at futures close and the just-auctioned 2y is 5.07, making 2/10 seem a lot steeper). However, look at something like SFRZ4/SFRZ7 (red/gold dec). That spread jumped 9 bps today to -50, so the move to a steeper curve is real. SFRZ4 settled 9538.5 (+10) and SFRZ7 settled 9588.5 (+1). I have attached a chart; Z4/Z7 needs a few closes above -40 to indicate a change in trend.
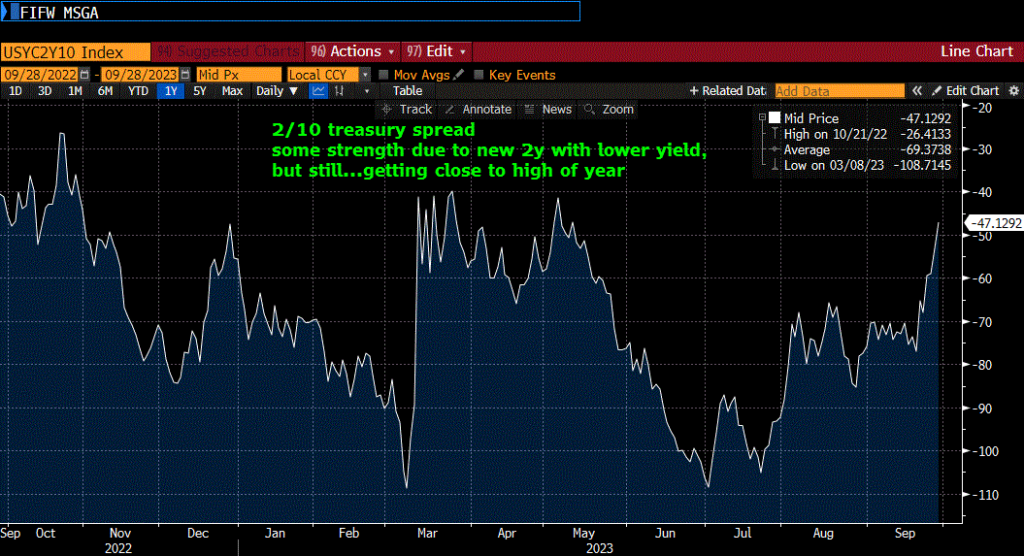
Below is red Dec/gold Dec SFRZ4/Z7
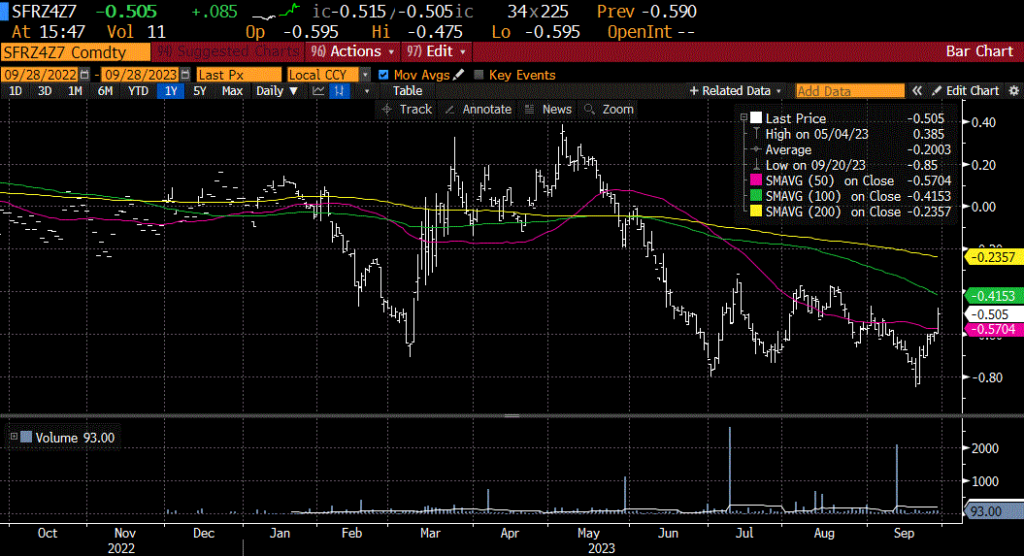
–In addition, SFRZ4 contract staged an impressive reversal. Wednesday featured a new contract low settle at 9528.5. Thursday had an outside range and a close near the high at 9538.5. This price action suggests that shorts should be exited. Of course, new info could change that, but for now selling pressure has been shut off, and vol declined. Consider long call spreads on this part of the curve. USZ3 settled exactly unchanged at 113-16. USX3 at-the-money 113.5 calls and puts each dropped 10/64s from 1’63 to 1’53, so the straddle went from 3’62 to 3’42. This, after the 30y yield had surged to over 4.80% and 20y to just over 5% in the morning. 30y ended 4.727%.
–News today includes PCE prices expected 3.5% yoy from 3.3 last. Core expected to decline to 3.9% from 4.2. Chicago PMI expected 47.6 from 48.7. ISM Mfg on Monday. The gov’t shutdown will likely delay Friday’s NFP release.
–I am surprised that since August CLX3 has traded from 79 to 92, yet gasoline prices at the pump have barely changed, and have even declined slightly, at least in the Chicago area. My bias is that gas prices are a constant signal influencing consumer confidence and behavior. I thought the BBG clip below summarizing Powell’s comments yesterday were somewhat amusing, given that Powell has repeatedly said the Fed isn’t quite sure how things will evolve and why some economic data have been difficult to understand.
(Bloomberg) — The Federal Reserve’s ability to influence
the economy depends on whether “people understand what we are
saying,” Chair Jerome Powell said, highlighting the importance
of work done by economic educators.
When Fed officials publish their projections for interest
rates and the economy, “one of our goals is to influence
spending and investment decisions today and in the months
ahead,” Powell said in comments prepared for a town hall event
with teachers in Washington Thursday.
“That will only be the case if people understand what we
are saying and what it means for their own finances.”
The Fed chair didn’t comment on his outlook for rates or
the economy.
–I’ll tell you what the trading public DID understand: that a 50 bp jump in the 2024 dot plot signals continued restraint and diminished value of forward cash flows.
In: Eurodollar Options
New low settles in SOFR contracts
Sept 28, 2023
–Rate futures continue to trade extremely weak, with most near SFR contracts closing at new low settles. For example, SFRU4 settled over 5% for the first time, at 9499 or 5.01%, down 6 on the day. To reach the current SFRZ3 price would require another 47.5 of roll-down. SFRU4 9500 straddle settled 95.0 with 352 days to go, breakevens near 4% and 6%. However, the 6% strike 9400 put settled 9.25 and the 4% strike 9600 call settled 22.5.
–There were a couple of new notable downside trades: a seller of 100k FFX3 at 9462.5 (settled 9461.5, open interest +71k), and a buyer of 45k SFRF4 9425/9400p 1×2 for 0.5 (settled there, 4.5, 2.0, vs SFRH4 9456.5). A hike on Nov 1 would obviously be an instant payout to the FFX seller as the contract would settle around 9443. There would need to be perceptions of another Fed move to 5.75-6.0% for the Jan 1×2. By the way, the March expiration 9425/9400p 1×2 settled at a credit of 0.75, 7.25/4.0.
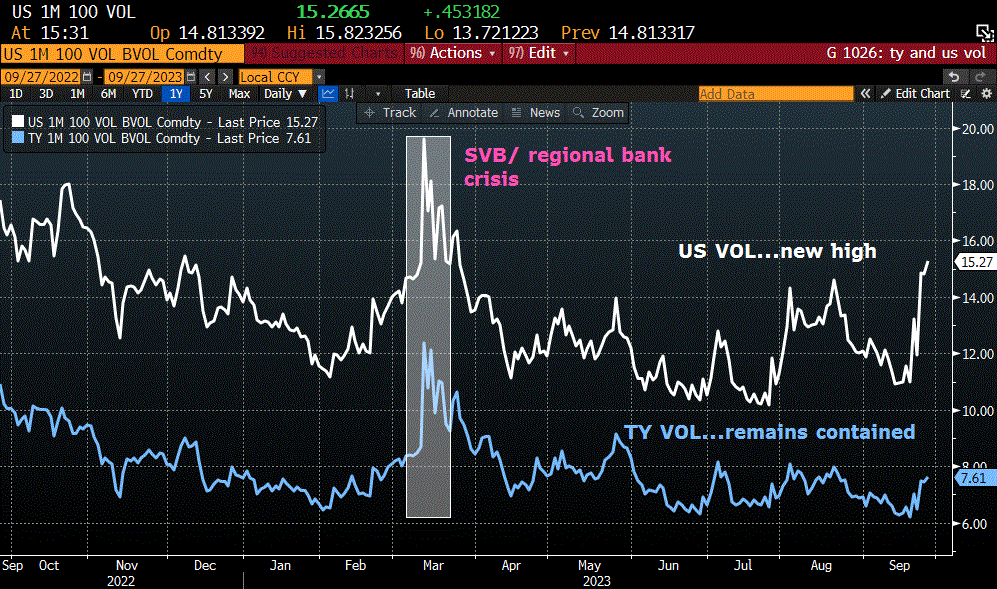
–Nov Crude closed at a new high 93.68, up 3.29 on the day. Treasury yields also continue to rise, with the ten year yield up 6.4 bps to 4.624% and 30s up 3.3 bps to 4.73%. Implied vol firmed to a new high in US as shown on the attached chart, but it’s not quite breaking through old highs in TY. Somewhat interesting to note that on Friday, SFRZ3 9450 straddle settled 16.5 vs 9453, and yesterday against 9451.5 that straddle settled 19.5. Yesterday SFRZ3 9475c settled 3.5, which was up 0.75 on the day with the contract -1.5! Maybe it was the large FFX sale that re-focused traders on the idea that the Fed might not be done. Maybe it was Kashkari talking about one more hike. And maybe it’s just that the world seems a little unhinged and financial stress is piling up.
–Today we have revisions to GDP National Accounts. Jobless Claims and the 7 year auction. Goolsbee comments at 9. Powell has a town hall meeting with educators at 4. Tomorrow PCE prices yoy expected 3.5% from 3.3 last.
In: Eurodollar Options
Where there’s smoke
September 27, 2023
–Stocks tumbled yesterday with SPX -1.5% and Nasdaq Comp -1.6% (though there’s a small bounce this morning). 30y bond yield continues to lead rates higher, ending 4.687% at futures settle, up 4.2 on the day. Shorter maturities unchanged to up slightly. New recent highs in 2/10 at -57 bps and 5/30 at +7.2. Fed Funds: November FFX3 settled 9462.5, 5.375% and FFF4 9456.5 or 5.435% vs Fed Effective 5.33. Market leans toward the idea of the Fed standing pat at the Nov 1 FOMC; Jan isn’t even at 50/50 for the Dec 13 meeting.
–In SOFR options there are more targeted easing plays focused on SFRH4. For example a buyer of 30k SFRF4 9462.5/9468.75/9481.25/9487.5c condor for 1. Max value 12.5 between middle strikes, with underlying SFRH4 near the lower strike at 9461. Similar idea +20k SFRH4 9475/9487.5/9500/9512.5 c condor for 1. Max value 12.5 between middle strikes. This one requires an actual ease, but not the prospect of emergency cuts (which could conceivably take us through the top strike). Additionally, there is continued accumulation of SFRM4 9600/9700c spread 7.0, now up to about 150k total position. Settled 12.25 and 5.25 ref 9479. This trade requires easing that is more aggressive. That’s what it’s all about now: when the easing starts, is it measured, or an emergency? The fiscal bullets are now spent, so it’s all going to be on Powell’s shoulders when the embers left in the ashtray are knocked over by the cat, and catch on the tablecloth, and the conflagration starts. And that’s more along the lines of the buy of 10k FVX 108 calls for 3.0. About 65 bps away, with the current cash 5y 4.625%. Like putting out fire…with gasoline.
–Today’s news includes Durables and the 5y auction. One last tidbit: CLX3 is 91.84 as of this writing, close to the high tick of the month at 92.43. On the 4th of July it was 70. As Dec Copper makes new lows.
In: Eurodollar Options

