
Curve and vol back to pre-SVB
June 7, 2023
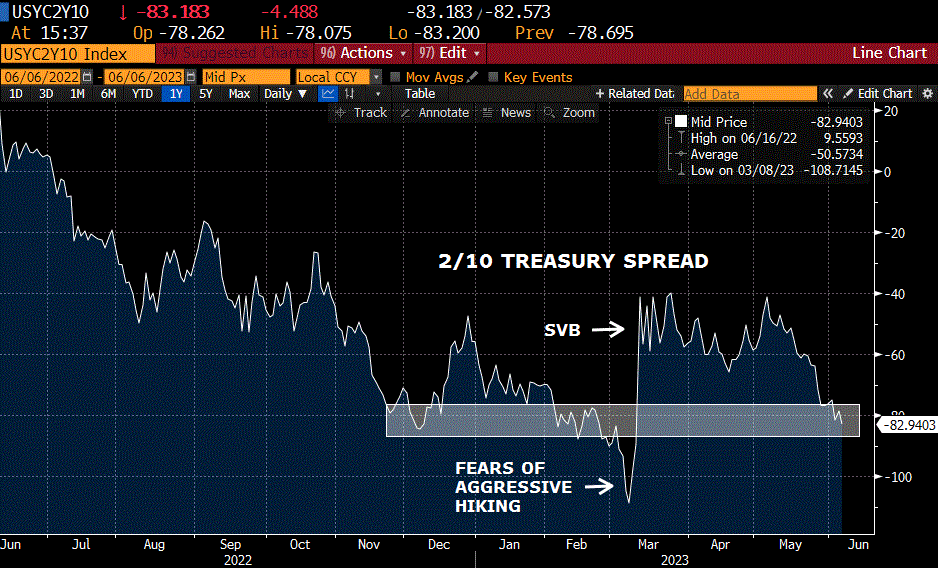
–Main feature Friday was a more inverted curve with 2/10 around -83 bps, 4 lower on the day. That’s right around the level from the end of last year which was the most inverted since the early 1980s, until the early March plunge to -108 on fears of continued aggressive hikes. Then SVB hit, sparking a rally to -40. Despite skip/pause talk for the June 14 FOMC, the market perceives the Fed as extremely tight, though expected t-bill issuance is also a dynamic. Clarida helpfully opined that a skip in June doesn’t signify an end to hiking, though perhaps he was just talking his book. Like he did at the Fed.
–Implied vol in treasuries similarly slid back to pre-SVB levels with TYU right around 7%. All is right again.
–On the SOFR curve, reds (2nd year forward) were weakest, down 8.125 bps to an avg 9637.5 (3.625%) while blues (4th year) were actually up 0.5 to 9687.0 (3.13%). At a settle of 9489, June FF are signaling acceptance of a pause (will settle 9492 on no move vs 9481 on hike of 25). If the Fed skips June but hikes in July then FFN3 should settle 9488; yesterday’s settle was 9484.
–New buyer of 40k SFRZ3 9887.5 call for 2 yesterday covered 9510.5 with 5 delta. Settled 1.75 vs 9504.5. Buyers of strikes around 1% and lower is a continuing theme.
–China exports reportedly lower than expected, damping ‘re-open’ hopes. US consumer appears to have run out of steam.
Et tu Dollar General?
June 2, 2023
–Vol crushed yesterday as debt-ceiling legislation passed. Skew came in. For example SFRH4 up 7.5 at 9569.5, 9600c only +1 (49.5), 9650c up 0.25 (35.25) and 9700c unch’d (24.75). Some calls marked lower on the day even on the rally. Curve edged steeper with the 2y yield down 5 bps at 4.337% and tens -3.2 at 3.605. On SOFR curve: reds +6.75, greens +4.125, blues +3.375. Yesterday’s Unit Labor Costs up only 4.2%. ISM Prices paid plunged to 44.2 versus 54.3 expected. ISM Mfg was 46.9…these are pretty much at the lowest levels outside of covid.
–Employment report today with NFP expected 190k and yoy Avg Hourly Earnings 4.4%, same as last.
–Dudley penned an early morning opinion that the Fed should keep going. On the other side, late in the day Harker echoed Jefferson for a pause. After a string of crappy retailer reports citing a weakening consumer, yesterday Macy’s and Costco, Harker said, ‘retail reports are weak….LET’S JUST SKIP A MEETING, see how it goes…’ You know, ‘let’s just WING it!’ It reminds me an awful lot of friend YZ saying, “Let’s run it through the model: * takes coin out of pocket and flips it * BUY”. On the other hand, it’s one thing if a bunch of retailers like HD, TGT, COST warn, but when Dollar General (DG) gets whacked 20% on the session, you KNOW there’s a problem.
–The Fed used to remind us that FF rate change policy is a blunt tool. What’s it supposed to do? Change behavior…eventually. COSTCO said that customers substituting into cheaper goods, which has been common in previous recessions. I.e. the consumer IS changing behavior. The most notable change has been pulling excess funds out of low interest rate bearing bank accounts into high yielding money markets. A friend of mine used to run a gym and say people wanted instant results. He’d respond, “it took you several YEARS to fall out of shape. It’s going to take a while to get you back”. It works with a lag.
*** No missives until middle of next week
Skip
June 1, 2023
–It’s the strategy I thought was an appropriate pivot for the Fed, continue to talk tough but don’t actually hike. That way, the threat of future tightening stays alive which would limit near-term ease speculation. In any case, Mester said she sees no compelling reason to pause rate hikes, followed by Fed Governor Philip Jefferson: “… skipping a rate hike at a coming meeting would allow the Committee to see more data before making decisions about the extent of additional policy firming.”
–Banks are still weak. For example PACW was 20 in Feb now 6.45. KEY was 20 in Feb, now 9.34 (down 6% yesterday). USB 50 in Feb now sub 30 (-2.5% yest). Is the credit crunch upon us? Chicago PMI was 40.4 vs 47.3 expected. Dallas Fed Tuesday was -29.1, worst since depths of Covid.
–When Jefferson’s comment was released (and duly tweeted by WSJ Timiraos: “The Fed is firming up plans to slow down the pace of rate rises by skipping a June hike, barring a blowout jobs report on Friday), FFN3 was trading 9474. Within a few minutes it was up to 9481 and settled 9482. A six bp move can be roughly thought of as shaving 25% off odds of a hike (On no hike FFN3 should be 9492). So FFN3 settled +8 at 9482 but FFQ3 only settled +5.5 at 9471; a spread of 11. NFP Friday expected 190k from 253k last, Avg Hourly Earnings yoy expected 4.4, same as last. It’s worth noting that CPI is June 13, the day before the FOMC.
–Jefferson’s comment is a pretty clear signal to exit treasury curve curve trades, though short term bill issuance may keep the curve under pressure in the short term. 2/10 rose 2.6 bps to -75. On the SOFR curve, SFRZ3/Z4 made a new low -160, down 2.5 on the day, while SFRU3/U4 remains the most inverted at -165.5.
No Ceiling, just open sky
May 30, 2023
–After closing lower in 11 of the last 12 sessions, SFRZ3 is getting a small bounce. Settled 9501.5 on Friday, now 9507.5. On March 8 the settle was 9446.5, the high settle a week later, following SVB was 9616.5. This latest sell-off started with a high close of 9579.5 on May 10, so on a settlement basis a drop of 78 bps. The Fed’s March SEP pegged year-end FF target at 5.1%; Friday’s settle was 4.985% (getting close). The end-of-2024 estimate in SEP is 4.3%, and Dec’24 SOFR settled 9647 or 3.53%. SFRZ3/Z4 is now the most inverted one-year calendar spread at -145.5.
–The debt ceiling agreement has sparked buying in stock index futures, though it also means a withdrawal of liquidity as the TGA is built back up (from fumes to $5-600 billion). Additionally the end of student loan forbearance is, according to McCarthy, going to result in $5 billion a month being transferred to the government. I doubt the number is anywhere near that high in reality, but it’s still a liquidity suck on the economy and consumer spending. 2/10 treasury spread at a new low of -75 bps (-78.5 this morning) is projecting much slower growth.
Feeling the blues
May 28, 2023 -Weekly Comment
*****************
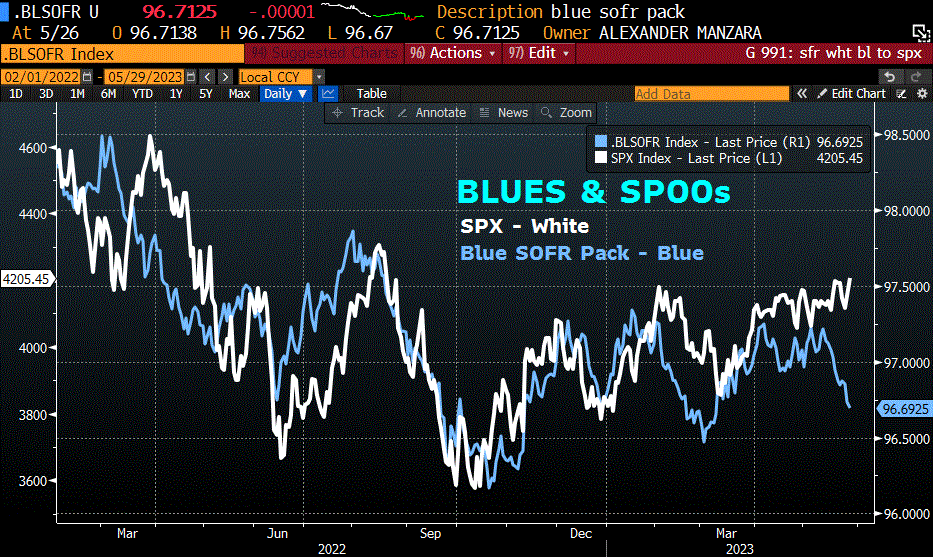
As far as I know, David Zervos, Chief Market Strategist for Jeffries, coined the memorable catchphrase “SPOOs and Blues” a short time after the financial crisis. It’s not always the case, but since the Fed began hiking rates, the two have pretty much traded in tandem, with moves in forward interest rates appearing to lead. (Blues are 4 years forward, SFRM6, U6, Z6, H7).*
Friend JC has steadfastly maintained that the back end of the SOFR curve has played the lead supporting role for stocks. If forward rates are declining that will be a good tailwind for stocks and help juice up discounted forward earnings.
So what happened in May? SPX closed at a new high for the year (thanks NVDA). However, from the high settle on 4-May the blue pack fell over 50 bps, to an average price of 9669.25 or about 3.3%. This calendar year, the 30yr bond has ranged between 3.5% and 4%, edging just above 4 on Thursday. For the past six months the blue pack has ranged between 9730 (2.7%) and 9650 (3.5%). In other words, the four year forward 1-year rate has averaged about 3.1%, 200 bps lower than the current Fed Effective rate of 5.08%. This week appears to have set off a silent warning that stocks are vulnerable to a setback (SPX that is).
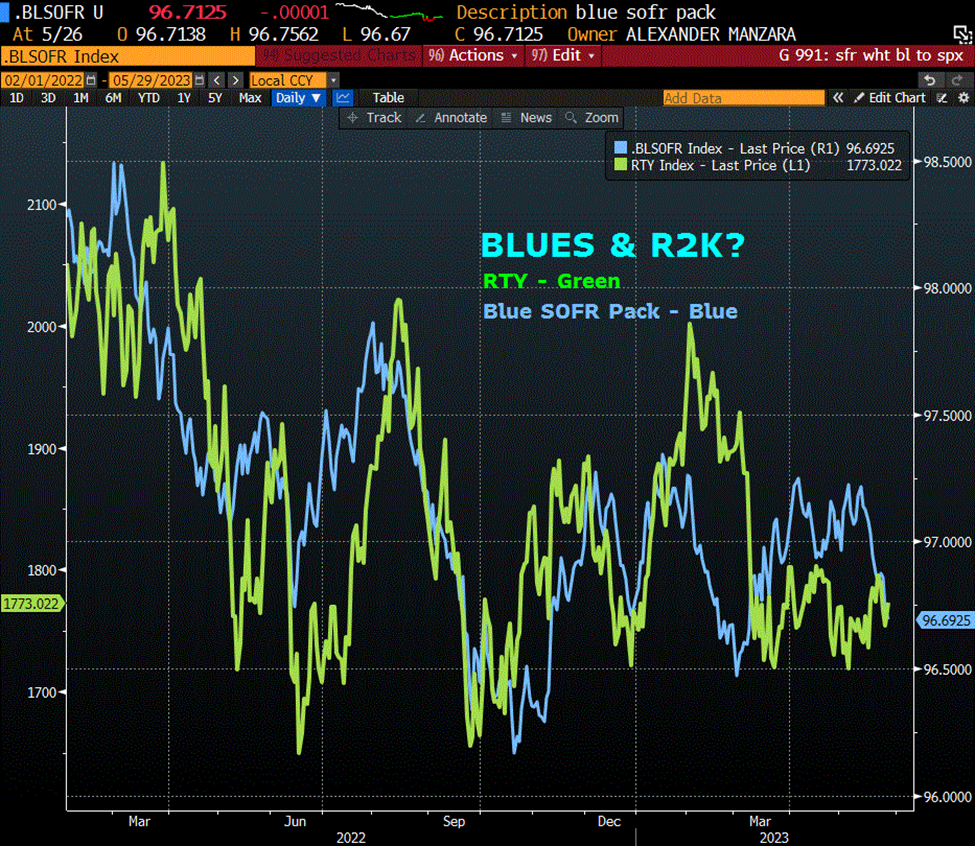
However, if you look at blues overlaid with the Russell 2000, the vulnerability is laid bare. That index (R2K) has never really recovered following the SVB revelation that regional banks were walking around naked, having lost the garb of low-cost stable deposits to fund assets backed by CRE. As Warren Buffett might say, the tide has gone out. Depositors have flocked to the high rates and safety of t-bills, with yields likely to be further enhanced by another Fed hike and increased supply once the debt ceiling can pass Congress.
We all know that “stocks” can mean a lot of different things. NVDA added $200 billion in market cap at the end of the week, close to 10% of the TOTAL cap of Russell 2k ($2.6T). Completely reasonable….right?
On the week, US yields soared as inflation data disappointed (Q2 GDP Price index +4.2% and PCE Price Index +4.4%). The two-year (using WI from the previous Friday) rose 33.7 bps to 4.564%. Tens added 12.2 bps to 3.81%. The 2/10 spread is -75 bps. On the SOFR curve, Whites (1st year) down 32 bps with a rounded pack price of 9496, Reds down 33.75 to 9628, Greens down 20.75 to 9671 and Blues down 18.25 to 9669. For this note, I focused on the forward part of the curve embodied by blues, but it’s worth a mention that higher US rates have also boosted DXY from a low near 101 in the beginning of May to 104.20 on Friday, with $/yen 140.60, a new high for the year, highest since last November. August Fed Funds settled 9466.5 or 5.335%, 25.5 bps above the current Fed Effective of 5.08%.
News this week includes ISM Mfg on Thursday and Payrolls on Friday, with NFP expected 190k. The tentative debt-ceiling deal may be put to a vote on Wednesday.
For your holiday barbeque listening enjoyment, here’s a fitting BLUES anthem from Albert King: Born Under a Bad Sign. (Full volume)
“If it wasn’t for bad luck, I wouldn’t have no luck at all”
| 5/19/2023 | 5/26/2023 | chg | ||
| UST 2Y | 422.7 | 456.4 | 33.7 | |
| UST 5Y | 370.5 | 393.2 | 22.7 | |
| UST 10Y | 368.8 | 381.0 | 12.2 | |
| UST 30Y | 394.4 | 396.7 | 2.3 | |
| GERM 2Y | 275.7 | 294.2 | 18.5 | |
| GERM 10Y | 242.7 | 253.8 | 11.1 | |
| JPN 30Y | 123.2 | 124.9 | 1.7 | |
| CHINA 10Y | 271.9 | 272.2 | 0.3 | |
| SOFR U3/U4 | -152.5 | -143.5 | 9.0 | |
| SOFR U4/U5 | -35.0 | -52.0 | -17.0 | |
| SOFR U5/U6 | 2.5 | 1.5 | -1.0 | |
| EUR | 108.06 | 107.29 | -0.77 | |
| CRUDE (CLN3) | 71.69 | 72.67 | 0.98 | |
| SPX | 4191.98 | 4205.45 | 13.47 | 0.3% |
| VIX | 16.81 | 17.95 | 1.14 | |
*A ‘PACK’ is simply the average of the 4 contract prices. The blue pack starts with SFRM26 9670.5, U6 9669.5, Z6 9669.0 and H7 9668.0. The average of the prices is 9669.25.
Washout
May 26, 2023
–Washout in rates continues. SFRZ3 settled -15 at 9508. Range on the month in that contract has been 108.5 bps and high settle to yesterday’s low settle is 89.5 bps. New highs in near SOFR calendars as another near-term hike is priced: FFQ3 settled 9467 or 5.33%, exactly 25 bps above the current EFFR of 5.08% (there are 2 FOMC meetings in front of the August contract). SFRM3/M4 made a new recent high of -126.25, while SFRH4/H5 made a new recent low of -121.5. I.e. weakness is concentrated in the 3rd, 4th and 5th forward quarterly contracts, H4 (-19.5, 9551), M4 (-21.5, 9594.5), U4 (-20.0, 9630.5). Inverted spreads indicate that eases are still expected, but this price action suggests they are coming a bit later and perhaps less aggressively. On the other hand, when something bad happens, the Fed USUALLY eases rapidly. Of course, we’re in a bizarro world with a bizzaro Fed: Hike Fast and Cut Slow?
–2/10 spread new low -69 bps (2y +16 at 4.506 and 10y +9.8 at 3.815). The thirty year bond yield ended at 4%, the top of this year’s 3.5 to 4% range. High in 2022 was 4.4%.
–Today we get the Fed’s preferred inflation measure, PCE prices, expected 4.3% yoy vs 4.2% last, with Core 4.6 from 4.6.
–SOFR option pit closes at noon Chicago today. Box until 4.
A soft, easy hike
May 25, 2023
I left a good job in the city
Working for the man every night and day
-Tina Turner Proud Mary
–Jobless Claims today expected 245k. 7yr auction. As Waller said yesterday, the labor market remains tight and inflation is stubbornly high, but credit conditions are a wild card which could lead to a skip in June. My sense is that the Fed is likely to skip, but to continue to jawbone that hikes are needed, which will have the effect of bringing forward SOFR contracts nearer to the current FF rate. In a way, that strategy serves as a “soft hike” and buys time. SFRZ3 (weakest contract) fell another 8.5 bps yesterday to 9523 or 4.77 vs EFFR of 5.08%, while SFRH4 fell 8 to 9570.5.
On Friday, we will be getting April inflation data based on personal consumption expenditures and then May CPI data on the first day of the FOMC meeting. These are two critical pieces of data I will be looking at between now and the June FOMC meeting to learn more about inflation dynamics and if we are seeing some easing in inflation pressures. (Waller)
https://www.federalreserve.gov/newsevents/speech/waller20230524a.htm
–Good news, bad news: NDVA exploded after hours on earnings and outlook, adding >$150b to market cap, while the US is looking at a credit downgrade by Fitch as debt ceiling talks drag on.
–UK CPI yesterday was +8.7% vs estimate of 8.2%. Huge drop in SONIA contracts with Dec3, March4 and June4 atll down 33 bps (9463, 9477, 9498). BOE’s Huw Pill was right, “British people need to accept they are poorer.” from April 25. In SOFR, new high in M3/U3 at -14.75 and in U3/Z3 at -34.5 as back contracts converge toward front. SFRZ3/Z4 new recent low at -152; the lowest settle in this particular one-yr calendar was -158.5 just before SVB. The most inverted one-year spread remains SFRU3/U4 at -162. Forward easing has been pushed back a little but is still being priced.
Front contracts weak
May 24, 2023
–Short end rates continue to press higher; weakest SOFR contract was SFRZ3 at 9531.5 (-3.0) but Z4 closed UP 2 at 9677 and Z5 UP 2 at 9691.5. So, the curve flattened with 2/10 at a new recent low of -63.5. Regarding SFRZ3, on May 10 the settle was 9579.5, and since then it has closed lower for 9 sessions in a row, printing 9530 (4.70%) this morning. It’s worth noting that the last FOMC projections in March had the end-of-year 2023 FF target at 5.1%, exactly where the target is now (5.0 to 5.25%). Currently, the market appears to believe the Fed will be able to hold the line this year on the FF target, and might even raise at the June 14 meeting. Of course, some of the weakness may be related to the idea of a tsunami of bill issuance if the debt ceiling clown-show ends.
–From yesterday (MNI): Benchmark John Deere filed prospectus to issue $36b in medium term notes, details over timing and individual size TBA. If DE does issue $36b at one offering, it would be the fourth largest on record, $5b larger than last week’s 8-tranche jumbo issued by Pfizer. [Stock is down about 18% from the year’s high]
–Today includes the 5y auction (wi at futures settle was 3.715%), immediately followed by a speech by Waller and then the FOMC minutes. NVDA reports today.
A quiet economic warning from copper
May 23, 2023
–ZH quotes Zoltan Poszar about banking issues: “It’s basically lessons in not being able to run interest rate risk, not knowing how to make a loan that will be weathering a rising interest rate storm.” Of course, deposit flight due to “bail-in” fears is a big part of the problem. Jamie Dimon is also warning of more failures. It’s not a surprise; costs of funds rapidly increasing while quality borrowers are sparse (except for the Federal Gov’t, and they’re doing their best to undermine THAT credit quality).
–Copper making new lows this morning for this calendar year at 3.63 (HGN3). July WTI holding around $72/bbl as, according to BBG, “Saudi Energy Minister Tells Oil Specs to ‘Watch Out'”.
–No debt-ceiling deal yet.
–Bullard yesterday said perhaps two more hikes would be in order, and says that “flush” households will keep the economy going. Perhaps we’ll get a sense of consumer strength (or NOT) in some retailer reports today: Lowes, BJ’s warehouse, Dick’s Sporting Goods, Auto Zone, Urban Outfitters.
–New high settled in SFRM3/SFRU3 at -18.25 (9480.25/9498.5) as Sept converges closer to the current EFFR of 5.08%. Vol firmer across the board as debt negotiations drag. Late new buyer of 10k SFRU4 9987.5/100.25 cs for 2.0. Underlying SFRU4 settled 9654.5. Revisiting the zero-bound next year? New Home Sales today.
Pause
May 22, 2023
–Debt ceiling talks continue.
–Powell on Friday: FED WAS EXPECTING FURTHER TIGHTENING UNTIL RECENTLY
@NickTimiraos Powell: “The risks of doing too much versus doing too little are becoming more balanced.”
–From MarketWatch
“Fed’s Kashkari says he’s open to a pause in rate hikes in June”. The tide appears to favor a pause at this point. Bullard speaks at 8:30 today, followed by Daly at 11:00.
–Seller of 50k SFRZ3 9675/9775cs Friday at 10. Settled 9.75 vs 9540. Roll down of short 9775 calls. There are still 266k open in SFRZ3 9550c which settled 45.0. Recall a large buyer >50k Z3 9550/9750cs in February; seems to have adjusted top strike lower over time but still holds longs in 9550s. SFRZ3 atm 9537.5 straddle settled 95.5. Vol subject to progress on debt ceiling.
–SFRM3/U3 settled new recent high -19.75 as expectations of ease are squeezed out of the Sept contract (settled 9504). In early March this spread was above zero (high of 6.0 with SFRU3 settling as low as 9430.5) but with the mid-March bank failures the spread plunged to a low tick of -47. Low settle has been -43, made on 4-May. Since SVB range has pretty much been -40 to -20, current -21. Market still expects easing into the end of the year, but the magnitude is lessening.

