Rumbling beneath the surface
May 21, 2023 – Weekly comment
*******************************
In the past week, yields rose aggressively. The five-year ended at 3.74%, up about 30 bps on the week. The thirty-year bond added 17 bps, to 3.944%. On the SOFR curve, June’24 (SFRM4) was the weakest, down 39 bps in price to 9625.5 or 3.735%.
The treasury curve flattened with 2/10 down about 6 bps to -60 bps. On the SOFR curve the SFRM3/SFRM4 one-year calendar soared 30.75 bps from -173 to -142.25 (9482.25/9526.5) while SFRM4/SFRM5 fell 8.5 to -64 (9526.5/9690.5); both moves due to relative weakness of SFRM4.
All rates had plunged in March due to the SVB banking earthquake, but are now retracing as aftershocks become muted rumbles (though Yellen warned of more banking consolidation). The 2y yield has retraced about 38% of the March swan dive from 5.07% to 3.77%. The ten year yield about 50% from the March high of 4.06% to the early April low of 3.31% and the 30y bond nearly 90% from the March high of 3.99% to the early April low of 3.55% (now 3.94%).
In terms of Fed policy, officials appear divided on whether or not to pause in June. For example on Thursday Logan said we’re not quite there in terms of evidence which would support a pause, but on Friday Powell said the balance of risks between tightening too much or too little were about evenly balanced. July Fed funds settled 9487.5 or 5.125% which is 4.5 bps over the current EFFR of 5.08. Of course, a hike in June would cause EFFR to go to 5.33 or 9467.0, and there’s another FOMC on July 26, worth 4 bps to FFN3 on a 25 bp hike at that meeting. Ignoring the July meeting, FFN3 is reflecting odds of 18% for a hike at the June FOMC.
An issue for the Fed, which they have been jawboning against, is that when the market perceives an end to hikes, the next move is naturally presumed to be an ease. Of course, that has been abundantly clear on the SOFR curve: even though SFRM4 fell 39 bps this week, it still is at a yield 142 bps lower than SFRM3. If I were the Fed, I would want to convince the market that rates can be HELD at relatively high levels for a few quarters, in order to really tamp down on higher inflation expectations. It’s not the exact level that’s critical, it’s the duration. PCE prices are released on Friday, expected 4.3% yoy with Core 4.6% vs 4.6% last. With FF 5-5.25%, one can easily argue the Fed is now in restrictive territory. I would say that in the past week, the Fed has been successful in terms of paring back future easing expectations. For example, SFRM3/SFRZ3 spread settled 12-May at -75, but rose to -55.75 by Friday, i.e. the forward rate reflected in the end of the year contract increased. In my opinion, the Fed should continue to talk about higher rates, even after pausing in June. As Powell alluded to on Friday, stricter credit allocation due to the banking shake-up cannot be quantified yet, and the Fed will just have to monitor how much restraint is actually imposed on economic activity and inflation.
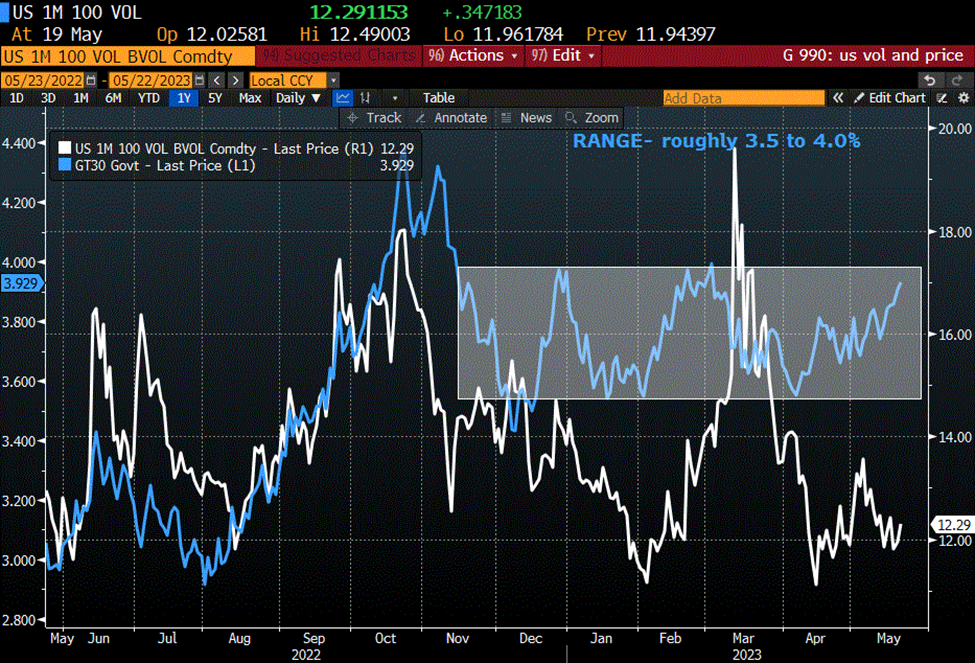
However, there is another looming issue which could send shockwaves through markets, and that of course, is the debt ceiling. VIX and MOVE are suggesting a complete lack of concern, with the former near 12-month lows and the latter well off the highs from March and slightly below the average for the past year.
The Market Huddle with Kevin Muir featured a fascinating discussion with Jim Leitner covering the debt ceiling. Leitner thinks the market is underpricing the risk of default and believes participants may begin to question the safety of treasuries. If that were to happen it would have far-reaching negative consequences as treasuries are used system-wide for collateral. He gives a hypothetical example of a futures broker suddenly declining to take treasuries as margin, causing massive forced position unwinds. He also mentions the 14th Amendment, which might allow Treasury to continue issuing debt even without a debt-ceiling agreement. Here’s a link to a short article explaining that scenario:
https://www.ncsl.org/state-legislatures-news/details/the-debt-ceiling-and-the-14th-amendment-the-jury-is-still-out#:~:text
From the article:
Some scholars say that Biden could argue that the government is required to pay its bills and that the language of the constitutional clause supersedes the statute limiting the size of the federal debt.
The point is that things could get sloppy quickly. Leitner mentioned he’s long TY 111p for end of June (I assumed he means TYN3 111p which settled 10/64, -0.11d). He indicated that he had bought for protection as opposed to a high expectation of ‘win’. A couple of weeks ago I suggested buying otm US puts as the yield on the 30y approached the recent range low of 3.5%. On the next page is a chart showing bond (US) vol overlaid with the yield on the 30-yr. From August to October of last year, vol strengthened right along with the surge in yields. In the March SVB fiasco, vol screamed to new highs as yields plunged. Currently the 30y yield is marching higher, but it’s not yet through the upper end of the recent range. However, if that’s what vol did when a regional bank couldn’t meet its obligations, imagine where it might go if the Federal Gov’t fails to honor the sanctity of its debt.
Apart from the debt limit, other things to watch this week are:
Fed speakers:
Bullard and Daly on Monday. Might cancel each other as Daly typically parrots Powell.
Logan (again) on Tuesday
Waller on Wednesday followed by the FOMC minutes
PCE price data, the Fed’s preferred measures, are released Friday.
I don’t typically follow earnings reports closely, but NVDA, which has a market cap of $733b reports on Wednesday; the stock has more than doubled from the end of last year, from 146 to 312 as AI fever builds. There are also a lot of retailers reporting next week which might provide more of a read on the consumer. Some of them:
Monday: Nordstrom
Tuesday: Lowes, Dick’s Sporting, BJ’s Wholesale
Wednesday: Kohl’s, Petco
Thursday: Costco, Best Buy
OTHER THOUGHTS / TRADES
Though the curve flattened, USM3 appears more inclined to an upside breakout in yield terms. July option expiry is June 23, which is after the June 14 FOMC. With USU3 settle at 127-11, USN3 120p settled 0’14 with a delta of -0.08. DV01 on the contract is approx $147, so a full point is ~6.8 bps. Current 30y yield is 394.4, so 4% should equate to 126-16 or so. A breakout above 4% would likelly result in another 25 bps relatively quickly. The 30y high yield from last October was 4.38% and the front contract at that time traded below 118.
There are a tremendous amount of option trades predicated on the settlement of SFRM3 on 16-June. My bias is for a settle above 9493.75, though I think it’s quite unlikely at this point to get above 9506.25 (unless the debt-ceiling wheels fall off). On the put side, SFRM3 9493.75 puts have the most open int at 650k, settled 13.5 vs 9484.25. On the call side the 9500s has 309k open, settled 3.25.
| 5/12/2023 | 5/19/2023 | chg | ||
| UST 2Y | 399.1 | 428.5 | 29.4 | wi 423.0/22.5 |
| UST 5Y | 344.3 | 374.2 | 29.9 | wi 371.0/70.0 |
| UST 10Y | 345.5 | 368.8 | 23.3 | |
| UST 30Y | 377.5 | 394.4 | 16.9 | |
| GERM 2Y | 259.4 | 275.7 | 16.3 | |
| GERM 10Y | 227.6 | 242.7 | 15.1 | |
| JPN 30Y | 123.9 | 123.2 | -0.7 | |
| CHINA 10Y | 270.6 | 271.9 | 1.3 | |
| SOFR M3/M4 | -173.0 | -142.3 | 30.8 | |
| SOFR M4/M5 | -55.5 | -64.0 | -8.5 | |
| SOFR M5/M6 | 2.5 | -0.5 | -3.0 | |
| EUR | 108.50 | 108.06 | -0.44 | |
| CRUDE (CLN3) | 70.02 | 71.69 | 1.67 | |
| SPX | 4124.08 | 4191.98 | 67.90 | 1.6% |
| VIX | 17.03 | 16.81 | -0.22 | |
Brainiacs
May 19, 2023
–Lorie Logan yesterday (Dallas Fed President and former head of the NY Markets desk).
“The data in coming weeks could yet show that it is appropriate to skip a meeting. As of today, though, we aren’t there yet.”
–August Fed Funds (FFQ3) closed down 6.5 at 9485.5 or 5.145% vs current EFFR of 5.08, while FFN3 settled 9484.0. SFRU4 led the decline, closing at 9661.5, down 18 on the day. Several Fed speakers (Mester, Bullard, Barkin, Logan) have indicated that a pause is not necessarily in the cards. Weakness in nearer contracts reflects that sentiment; the ‘pivot’ is being less aggressively priced and slightly pushed forward in time. New lows in one-year spreads M4/M5 at -68 (9630/96.98; -3 on the day) and U4/U5 at -38 (9661.5/9699.5, -5.5 on the day)… moving a bit farther back. SFRM3/U3 hit a new recent high of -21 as SFRU3 has sold off and is converging toward the current FF target. SFRU3 settled yesterday at 9502, more than 100 bps lower than the highs registered during the SVB fiasco (high settle on 3/15 was 9598.5 while the high tick was 9647.5).
–Against this backdrop Powell and Bernanke speak today and will likely repeat the paternalistic mantra that the banking system is ‘sound and resilient’ and that the Fed will not stop until it’s sure that the scourge of inflation has been vanquished. Is there irony in an environment where money is pouring into a few big tech stocks associated with Artificial Intelligence, thus masking weakness across the broader equity landscape, while at the same time the brain trust of the Fed discusses inflation? With apologies to Jules, “Check out the big brain on Ben”. After all, Bernanke, in a tenacious effort to fight deflation, stoked the embers that led to the current fire.
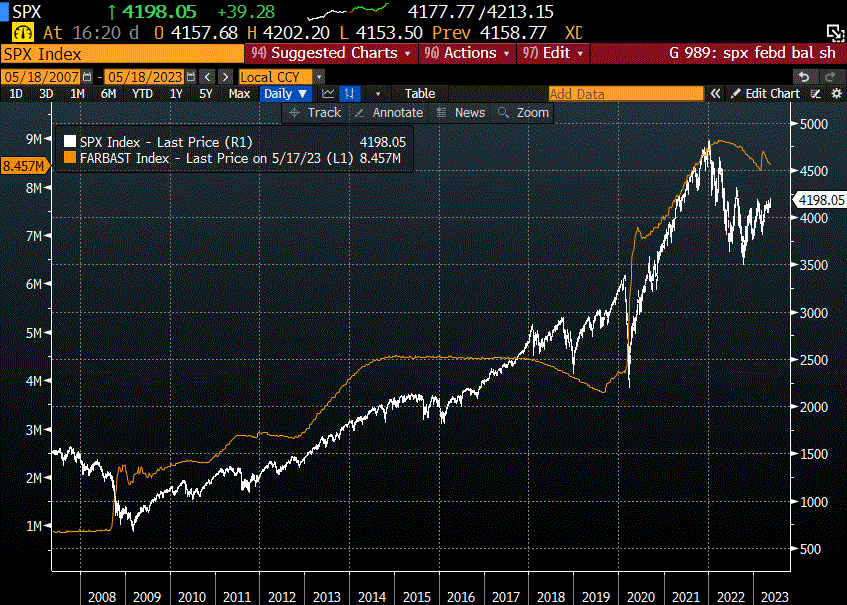
–The Fed’s balance sheet, having temporarily blown up in March as banking problems flared, is back below $8.5 trillion. Attached chart shows balance sheet and SPX. The good news is that the debt-ceiling is being raised, the bad news is that t-bill issuance is going to drain liquidity to replenish the TGA. Eleven months ago, at the June 15, 2022 FOMC, the committee decided to raise the FF target to 1.5-1.75%. They talk about policy having an effect 6-12 months after the initial moves. 3.5% of the rate hikes have been in that window.
Feel-good
May 18, 2023
–June’23 SOFR options expire 16 June, four weeks from tomorrow. SFRM3 settled 9486.5, or 5.135% with EFFR pegged at 5.08% (9492.0). The contract has 1.296 million open. What is pretty amazing is the amount of put open interest on SFRM3, a total of 5.146 million. Over 900k puts traded yesterday. For example, a buyer of >50k SFRM3 9493.75/9487.5/9481.25/9475p condors bought for 2.0. This trade has max value of 6.25 bps between the middle strikes, and max loss of premium paid. It’s not that I believe there will be some sort of squeeze; it’s pretty clear that the Fed has squashed expectations of an ease at the July 26 meeting with August FF settling exactly at 9492.0. However, it is somewhat interesting that SFRM3/U3 calendar is -25, with SFRU3 9511.5. Attached below is an image of players from @PNTOptions.
–Overall, vol down pretty hard. Example, SFRH4 settled 120.5 (9600^ vs 9602.5) vs 9612.5^ on Tuesday at 122.5. Just considering atm puts: SFRU3 settled 9511.5; 9512.5p 27.75, breakeven at 9484.75. SFRZ3 settled 9552.0; 9550p 46.0, b/e 9504.0. SFRH4 9602.5; 9600p 59.0, b/e 9541.0. Clearly expecting eases over time, and if one thinks the Fed can hold the line, there are some attractive put structures.
–Jobless Claims today expected 252k from 264 last. A print above 270 would be more indicative of weakening labor. Both HD and TGT (yesterday) have warned of slowing retail sales trends. Powell and Bernanke tomorrow, but the groundwork has already been done by various speakers: no reason to think rate cuts will occur and the banking system is sound and resilient.
–Feel good rhetoric on the debt ceiling helped spark a bid in stocks, with continued flows into AI. For example NVDA closed above 300, more than doubling since the start of the year.

–To their credit, not even trying to hide it any more. Here’s a proposal from members of Chicago Mayor Brandon Johnson’s transition team.

More hikes = more bank failures
May 17, 2023
–Fed continues leaning against the short end curve, which has priced significant easing this year. Mester started it off by saying the Fed is not quite at the ‘hold’ rate yet. Barkin said he’s willing to raise again if necessary. Barr and Williams said the banking system is “sound and resilient”. Goolsbee said it’s too soon to be talking about cutting rates. SFRH4 was the weakest contract -9 at 9611.5. SFRU3 settled 9515, down 6 on the day, but that rate is still just 4.85% compared to EFFR of 5.08%. I.e. the market is giving a bit of ground, but not all the way. Spreads continue to reflect expectations of significant easing, even if the timetable is pushed out marginally:
–SFRZ3/Z4 made a new recent low a -150 (9558/9708, down 4.5 on the day), low settle just before SVB was -158.5. Lowest 1-yr calendar is still SFRU3/U4 at -174.5. SFRZ3/M4 6-month calendar settled exactly at -100 (9558/9658, down 1 on the day). Ten year yield rose 4 bps to 3.547.
–Powell speaks on a panel Friday joined by Bernanke, our friendly advocate of helicopter money to fight deflation. From his November 2002 speech: ” But the U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.” Does it have an “on/off” switch?
–Home Depot warned about forward sales. Retail Sales were +0.4. Not great on a real basis. PACW settled 4.57, down 14.6%. PACW was around 30 in early February. I am seeing many articles and ads about high CD rates; banks need funding costs below that of their assets. The Fed seems intent on driving funding costs higher. It doesn’t help much if a bank is able to maintain its deposit base if those funds cost significantly more…
–Seeing a bit more about the dwindling balance in the TGA, now around $87b vs typical need of > $600b.
Retail Sales today, 20y auction Wednesday
May 16, 2023
–Retail Sales today expected +0.08, ex-auto and gas +0.2%. Yesterday’s Empire State Mfg at -31.8 was much lower than expected, has only been more negative once since covid.
–NY Fed’s Household Debt and Credit report shows that auto loan and credit card delinquencies are rising, but not yet at dangerous levels.
–Markets were quiet. All SOFR straddles down 1-3 bps at settle. For example, SFRH4 9618.75 straddle was sold down from 128 to 124.5 and settled 123.75 ref 9620.5.
–Attached chart is 5y and 10y breakeven rates on top panel, and the spread between the two in lower panel. In lower panel, shaded red area represents 5y < 10yr. Green shade is opposite, 5y > 10y, which reflects the recent inflation burst. 5y is now lower again, 213 bps vs 220.5, indicating inflation panic has subsided.

https://twitter.com/AlexManzara/status/1658196289744510977
Free Loans at Risk
May 15, 2023
–Selling pressure across rate futures on Friday, led by weakness in the front end. SFRZ3 settled 9567.5 (-10) or 4.325%. The red pack settled 9698.0 or 3.02%. down just over 12 on the day. The 2y note ended at 3.99%, up 8.7 bps on the day, tens +6 at 3.455%. Vol softened considerably in SOFR. For example, SFRU3 9525^ settled 63.0, one week ago the atm 9531.25^ was 74.0. On Friday SFRU3 option trading favored the upside. Buyer of about 15k each SFRN3 and U3 9525/9575/9625 c flies, settled 4.0 and 3.0 ref 9522.5. Seller of 20k SFRU3 9506.25/9493.75/9481.25 put tree for credit of 0.75 to 0.5 (buying top strike for credit; settled -0.25).
–Retail Sales tomorrow. Several articles note that credit card spending is slowing.
–According to @FreightAlley, ever since COVID, “$1.12 trillion of student leans remain in forbearance… On July 1, 2023, the student loan forbearance program ends and payments will resume.” This deferral has been repeatedly extended by the Biden administration, but there is apparently a suit that questions the legality of using the HEROES act to extend non-payment.
–Total student loans are over $1.7 trillion with most of that owed to the federal government. If the interest rate is 5% and the amount in forbearance is $1 trillion, then that’s a subsidy of $50 billion/yr. The attached link claims $5 billion per month. That’s a lot of Starbucks lattes. I view this as a direct withdrawal from Consumer spending (if it occurs). It’s not as if gov’t spending goes up due to the windfall, gov’t spending will continue at its same unsustainable pace. Also, it’s likely the case that a large chunk of those loans will never be paid. But if the deferral ends, it’s another factor likely to restrain consumer spending.
$1.12 trillion worth of student loans remain in forbearance, meaning that payments have been temporarily paused. On July 1, 2023, the student loan forbearance program ends & payments will resume.

4.99%
If you got your Direct Subsidized or Unsubsidized Loan on or after July 1, 2022, and before July 1, 2023, it will have a fixed interest rate after the payment pause ends: For undergraduate students, the interest rate for Direct Subsidized Loans and Direct Unsubsidized Loans is 4.99%.
Prices don’t lie
May 14, 2023 – weekly comment
**********************************
Still a man hears what he wants to hear and disregards the rest.
–Simon and Garfunkel- The Boxer
The odds that the United States will fall into a recession at some point over the next 12 months have risen to a 40-year high, according to a probability model from the NY Fed.
The probability that the country will enter a recession within the next year has risen to 68.2 percent, according to the New York Fed, which is the highest level since 1982.- Epoch Times
What does that mean for us? We’re probably in recession now. Does it mean that equities in general will decline? That interest rates fall?
From Michael Lewis’ book, The Undoing Project:
As it turned out, the Jackson Prison inmates choosing between gambles had a lot in common with Kenneth May’s students when they chose between spouses: After they had said they preferred A to B and B to C, they could be induced to prefer C to A. Even when you asked them up front whether they would ever choose C over A and they insisted they would never do such a thing, they did it…
In some of our biological systems we are equipped to detect big differences, in others small ones – say a tickle versus a poke. If people can’t detect small differences, Amos figured, they might violate transitivity.
This book is about decision making, mostly exploring the work of Daniel Kahneman and Amos Tversky. It has many fabulous examples of flawed choices resulting from unconscious bias. In a world filled with cocksure confidence and righteousness about every social topic, it’s a refreshing read especially from a trading perspective. An early summary of research by Tversky:
People predict by making up stories.
People predict very little and explain everything.
People live under uncertainty whether they like it or not.
People believe they can tell the future if they work hard enough.
People accept any explanation as long as it fits the facts.
The handwriting was on the wall. It was just the ink that was invisible.
People often work hard to obtain information they already have and avoid new knowledge.
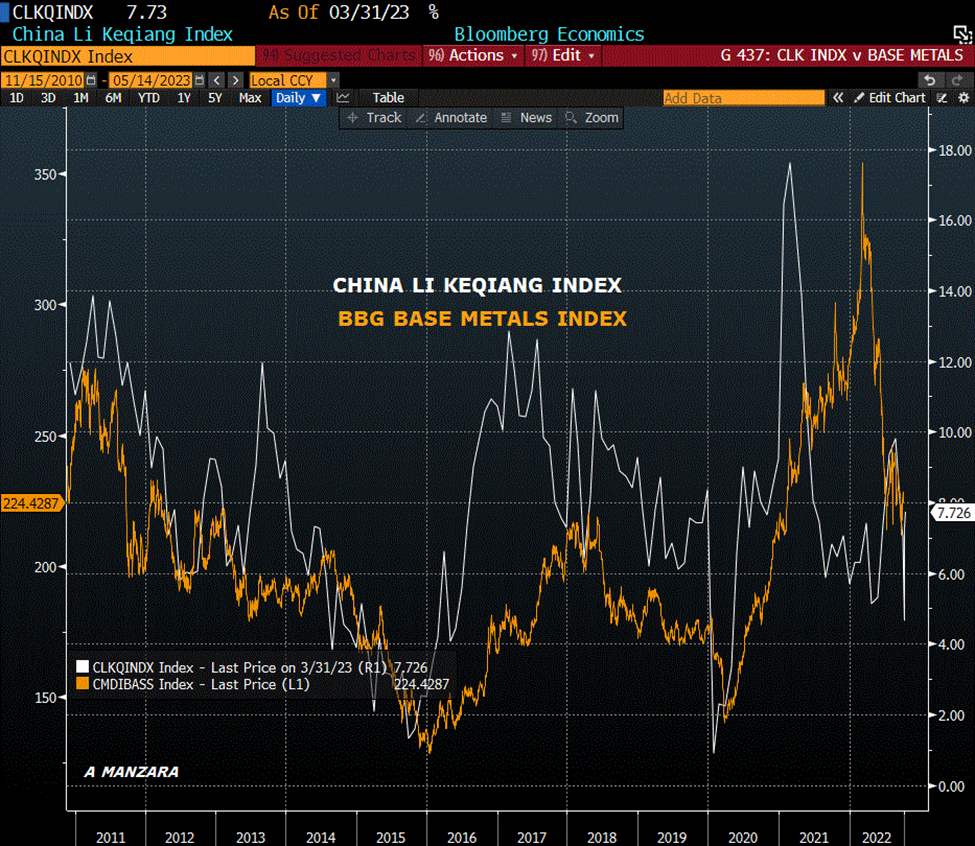
I have seen several articles about the vibrant China “re-opening”. However, when looking at the Li Keqiang index, base metals prices, and China’s ten year yield, the story seems to be one of economic stagnation. The Li index measures rail freight, electricity consumption and bank lending. China’s ten year yield is now 2.7%, at the low of this calendar year, having been as high as 2.93% in the beginning of March.
Here’s a little clip from Barron’s:
Many investors are underweight stocks and focused on what could go wrong. A possible Federal Reserve rate pause is something that could go right.
Is that some sort of insight to help with our investment decision-making? If anything, it’s a disservice.
There are a lot of stats like the NY Fed recession probability one, cited not just as two-in-three but 68.2%. What’s the purpose of the extra decimal? Probabilities in markets change all the time, the search is to trade one market with high odds of a given scenario, vs one trading at lower odds.
In US markets, expectations of rate cuts are gaining ever more traction. This fact is overtly priced. The rolling first to fifth SOFR one-year calendar spread has been inverted almost the entire year, apart from a brief flirtation with zero after February’s stronger than expected payroll and inflation data. SFRM3/SFRM4 settled -173 on Friday and SFRU3/U4 settled -172.5, both near lows of the year, which happen to be near historic lows. FFU3/FFU4 settled -179; it’s the most inverted 1-yr spread on that curve. The two-yr yield has oscillated around 4% since mid-March, having been above 5% just prior to SVB’s collapse. The green and blue (3rd and 4th year) SOFR packs have been consistent with forward funding rates of 2.5% to 3.25% all year. Green pack (SFRM5, U5, Z5, H6) settled just above 9721 on Friday, or 2.79%, while the blue pack (M6, U6. Z6, H7) settled 9713.75.
Rate futures are forecasting lower inflation and growth. The response in the past week has been to play for a somewhat accelerated timetable of possible easing. For example, there was a buyer of 15k SFRN3 9525/9575/9625c fly for 4.0 (settled 4 vs U3 9522.5). The same structure was bought in September, and SFRU3 9512.5/9537.5/9562.5 c fly was bought for 1.75 (settled 1.5). These trades stand to work if the thesis is right, with limited damage if wrong.
Obviously, new information could change the outlook. The stories being predicted by Federal Reserve officials have not been particularly accurate and often haven’t even fit the facts.
In the clearing stands a boxer
And a fighter by his trade
And he carries the reminders
Of every glove that laid him down
Or cut him till he cried out
In his anger and his shame
“I am leaving, I am leaving”
But the fighter still remains
| 5/5/2023 | 5/12/2023 | chg | ||
| UST 2Y | 392.2 | 399.1 | 6.9 | |
| UST 5Y | 341.6 | 344.3 | 2.7 | |
| UST 10Y | 343.3 | 345.5 | 2.2 | |
| UST 30Y | 375.3 | 377.5 | 2.2 | |
| GERM 2Y | 257.2 | 259.4 | 2.2 | |
| GERM 10Y | 229.0 | 227.6 | -1.4 | |
| JPN 30Y | 126.4 | 123.9 | -2.5 | |
| CHINA 10Y | 273.6 | 270.6 | -3.0 | |
| SOFR M3/M4 | -176.0 | -173.0 | 3.0 | |
| SOFR M4/M5 | -50.5 | -55.5 | -5.0 | |
| SOFR M5/M6 | 5.0 | 2.5 | -2.5 | |
| EUR | 111.46 | 108.50 | -2.96 | |
| CRUDE (CLM3) | 71.34 | 70.04 | -1.30 | |
| SPX | 4136.25 | 4124.08 | -12.17 | -0.3% |
| VIX | 17.19 | 17.03 | -0.16 | |
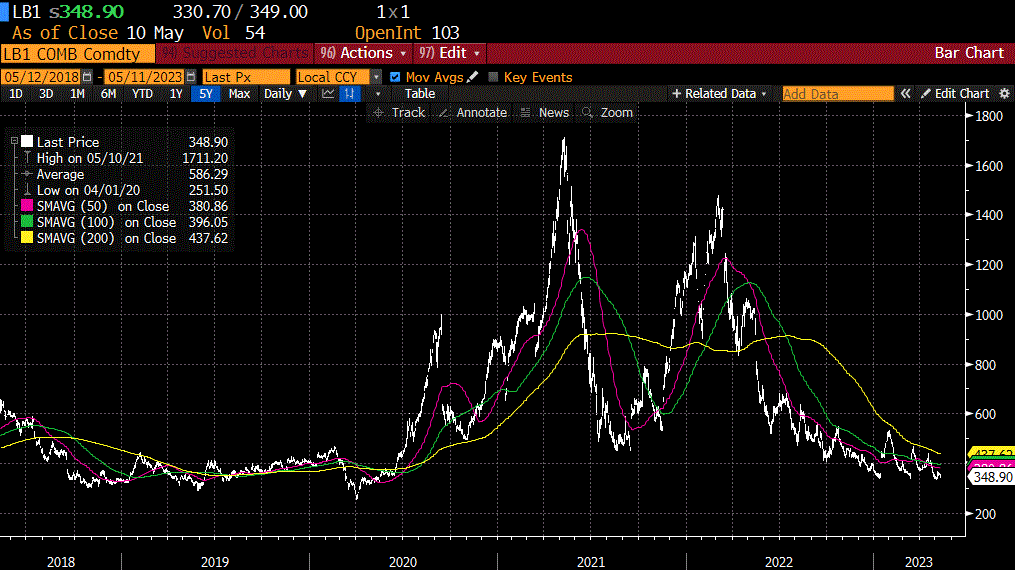
Lumber was 1600 in 2021. Now 348.
May 12, 2023
–PPI yoy just 2.3% yoy. Core 3.2%, both lower than expected. Yields fell immediately but ended only marginally lower. 10s fell 4.3 bps to 3.394%.
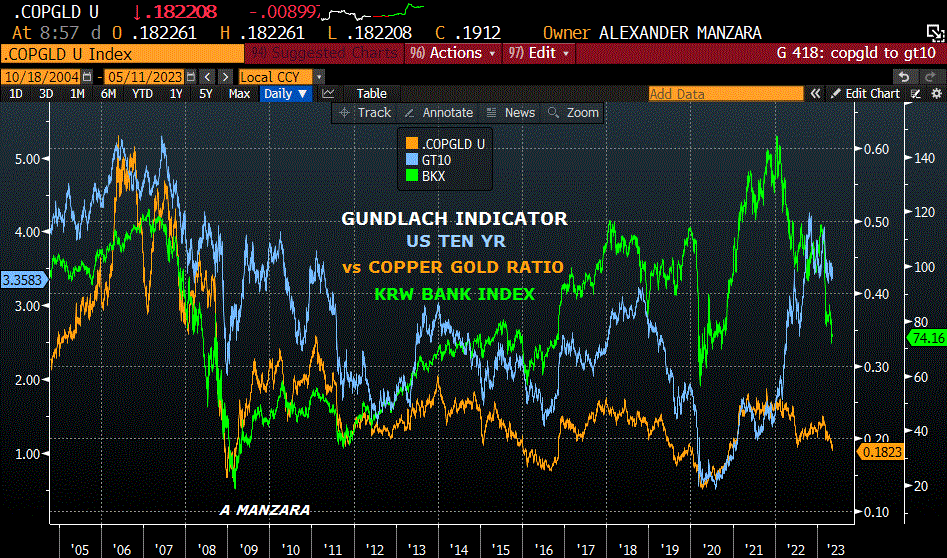
–Copper futures fell to their lowest level in 2023 (HGN3 3.71). As can be seen on attached chart, lumber is back at 2018 level, less than one-quarter of the high price set in 2021. Ten year breakeven (treasury/tip) ended yesterday at a new recent low 217 bps. An indicator Gundlach has cited is the copper/gold ratio vs the ten year yield. The latter should be crashing, not that 3 3/8% is high.
–New low in SFRU3/U4 at -177 bps. SFRM3/M4 settled -183.5; the front spread is the most inverted. A twitter clip from yesterday said the ratio between tech stocks and S&P 500 is 2 standard deviations above the historical mean. Not even sure why I am adding that snippet, except to say that it’s all about big tech, which trade like long-dated bonds.
–May SOFR option expiration today. SFRM3 is trading 9494.5, pegging the 9493.75 strike. There are 82k May 9493.75c open, settled 2.0 and 226k 9493.75 puts open, settled 1.25.
Gundlach indicator below…added BKX, a regional bank index
Lumber
Inflation deceleration
May 11, 2023
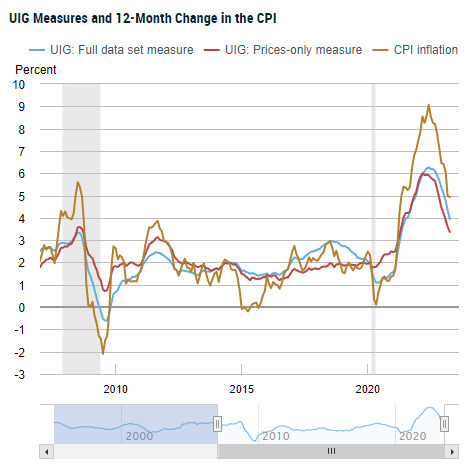
–CPI slightly better than expected at 4.9% yoy. NY Fed’s Underlying Inflation Gauge declined as well:
- The UIG “full data set” measure for April is currently estimated at 4.0%, a 0.3 percentage point decrease from the current estimate of the previous month.
- The “prices-only” measure for April is currently estimated at 3.4%, a 0.2 percentage point decrease from the current estimate of the previous month.
–Rate futures immediately surged as the market was set up short going into the data. Tens ended down about 8 bps to just over 3.43%. SFRM4 was the leader on the SOFR curve, closing +16 at 9679. New low settle in SFRU3/U4 one-yr calendar spread at -176 (9532/9708) down 6 on the day. (Low settle on any 1-yr calendar has been M3/M4 at -192).
–On Tuesday NY Fed’s Williams said he didn’t see any reason for the Fed to cut rates this year. Consider these six-month spreads: SFRU3/SFRH4 settled -102 (9532/9634). SFRZ3/SFRM4 settled -99.5 (9579.5/9679). The market doesn’t much care what Williams thinks, forward spreads indicate fairly dramatic cuts, even if the Fed can hold steady in the short term.
–The stock market DOES care however, about what Nick Timiraos says: “If the Fed was poised to take a summer vacation, the April CPI report won’t spoil those plans.” (Afternoon tweet). Stocks responded positively. The good news is that inflation is stabilizing. The bad news is that the credit crunch is just beginning and the debt ceiling circus is in full swing.
–PPI and 30y auction today. PPI yoy expected 2.4% with Core 3.3%.
Inflate out of it
May 10, 2023
–Three yr wi was 3.723, went off 3.695; strong demand. 10y today. NFIB small business optimism weak at 89.0.
–CPI today expected 5.0 yoy vs 5.5 and Core 5.5 vs 5.6.
–Vol up in front SOFR contracts, for example SFRH4 was down 0.5 at settle (9618.5) but almost every otm call settled +1 on the day. SFRH4 9625^ settled 132.75, was 129/130 Monday.
–Yesterday I cited St Louis Fed chart showing that HH equity in residential real estate was near a record high 71%.
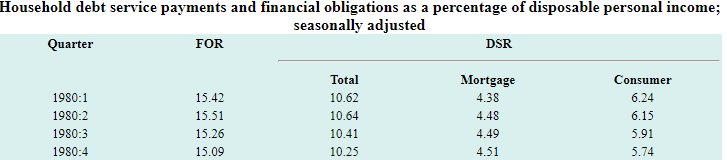
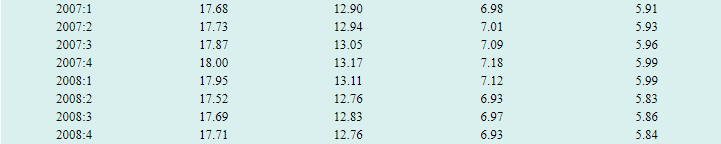
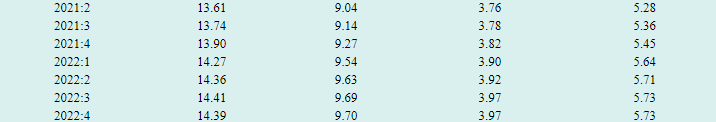
Today are some excerpts from the FOR, Financial Obligations Ratio, which shows mortgage & consumer credit in separate columns. The FOR adds rents, auto leases, home insurance and property taxes. Overall the household sector currently looks ok, though the report notes that calculations are difficult and that changes are the most important aspect of the report.
https://www.federalreserve.gov/releases/housedebt/