
The Hard Part
May 12, 2024 – Weekly Comment
***********************************
“See, you know how to TAKE the reservation. You just don’t know how to HOLD the reservation. And that’s really the most important part of the reservation: the HOLDING.”
“The easy part of private credit is lending money. The harder part is getting it back.”

The first quote is from a Seinfeld episode where the car rental desk does NOT have the midsize which Jerry reserved. The second is from James Morrow of Callodine Capital, cited in an April 18 BBG article and again by Danielle DiMartino Booth in a Blockworks podcast this week. DDB also said this: “Traditional banks are now expediting price discovery [writing down asset values] when it’s incumbent on private equity and private credit to slow the process of price discovery.” She implies that there are a lot of dodgy assets on private equity books that are tucked in dark corners (with fingers crossed for rate cuts). I happen to have first-hand experience with this dynamic. I worked at Refco when it went public. I bought shares in the IPO; as much as I thought was prudent. The CFO assured me I was thinking too small, that Refco was on a path to go head-to-head with the CME. I knew guys that took out second mortgages for this deal. Then, as the stock was climbing, a non-performing, or actually, a non-existent asset was discovered (un-discovered?) on the books. I think it was an uncollectable debt related to the previous blow-up of a famous trader. Fraud. And that, as they say, was all she wrote. Stock went to zero. CEO went to jail. That was in 2005.
They don’t let that happen any more.
If it’s private, you can value it wherever you like. Tough for the end investors to really know. There was a May 7 article by Business Insider for example, saying that Blackstone’s BREIT is not generating the cash flow out of operations with which to pay investors. It’s a pretty harsh accusation: From the article: “Craig McCann, a financial analyst who served as an economist at the Securities Exchange Commission, wrote last year. ‘Investors should not accept anything Blackstone and BREIT state as truthful.’ ” But BX isn’t anywhere near zero. It’s only about 6% away from the year’s high.
I’m not saying these things are true or untrue. But we’ve all seen situations unravel in a hurry. Everyone knows that, but now thinks the Fed will always be there. Bullshit.
Last week I cited the SBUX earnings call as a dead canary regarding the consumer. This week ‘Goldman warns consumers are cracking’ (ZH). McDonalds is vowing to bring back value. Whole Foods is “…expanding its generic brands to offer more affordable options and minimize the impact of inflation.”
In April, Consumer Confidence sank to the year’s low of 97.0 from 103.1 in March. On Friday, U of Mich Consumer Sentiment plunged to 67.4 from 77.2. On Tuesday we get NFIB Small Business Optimism, which was 88.5 last, below the COVID low. Last time it was here was 2012. Also on Tuesday is the Q1 NY Fed Report on Household Debt and Credit. This report is released at 11:00 am, but there’s a press call at 9:30, so someone will have the details before the 11:00 am release. (if not already)
NFIB is tracking the path going into the GFC (in a downtrend from 2005 to the beginning of 2009). Note that the last Fed hiking cycle of similar magnitude ended in June 2006. FFs remained at 5.25% for 15 months, until Sept 2007. In the current cycle, the last hike was in July 2023. Fifteen months puts us just before the election. This weekend Bowman said she doesn’t see the need for cuts this year. Logan said it’s too early to think about cutting and even Kashkari says the FF rate should stay high for an extended period. (I would note that in the Greenspan years, Fed Funds stayed between 5% and 6% from the start of 1995 to the end of 1998, nearly 4 years). Last week’s SLOOS indicated generally tighter credit conditions. While many analysts are complaining that financial conditions are becoming too loose and will re-ignite inflation, I think those fears are overblown. Long-end yields are still being pressured higher by the fiscal situation. Deterioration in consumer finances will keep the Fed on track to ease short rates. The curve should become less inverted.
Along with NFIB, and the NY Fed report, PPI is released on Tuesday. Then on Wednesday, CPI and Retail Sales. CPI expected 0.4 with Core 0.3. Yoy expected 3.4 from 3.5 with Core 3.6 from 3.8.
OTHER THOUGHTS
Overall it was a quiet week. Curve became slightly more inverted. The two year rose 6.5 bps to 4.866%. Tens rose 1.5 bps to 4.644%. On the SOFR strip SFRU5 was weakest, settling -10 at 9569, while three years forward, SFRU8 was only down half a bp at 9604.5.
Somewhat interesting were large (new) out-of-the-money put buys in treasuries Friday, right around the time of futures settlements:
TYN4 105.5p 6 paid for 35k, settled 7
TYN4 104.5p 3 paid for 35k, settled 4
(TYU4 settled 108-305 ref 10y year 4.644%. One point in TY futures is 15-16 bps, so 3.5 points, the 105.5 strike, is around 50 bps away.
FVN4 104.0p 6.5 paid for 35k, settled 6.5
FVN4 103.25p 3 paid for 45k, settled 3.0
FVU4 settled 105-3025 ref 5y at 4.516%. One point in FV futures is 23-24 bps, so 2 points to the 104 strike is also around 50 bps away.
There are some short end trades going on like buys of SFRM4 9475/9500c 1×2 for 0.5 (settled 0.25, 2.25/1.0) and SFRU4 9500/9550c 1×2 (also settled 0.25, 9.25/4.5). Much better to pay up rather than have the open-ended risk to the upside.
| 5/3/2024 | 5/10/2024 | chg | ||
| UST 2Y | 480.1 | 486.6 | 6.5 | |
| UST 5Y | 447.8 | 451.6 | 3.8 | |
| UST 10Y | 448.7 | 450.2 | 1.5 | |
| UST 30Y | 465.7 | 464.4 | -1.3 | |
| GERM 2Y | 292.4 | 296.7 | 4.3 | |
| GERM 10Y | 249.5 | 251.7 | 2.2 | |
| JPN 20Y | 168.3 | 169.2 | 0.9 | |
| CHINA 10Y | 231.5 | 232.0 | 0.5 | |
| SOFR M4/M5 | -90.5 | -82.5 | 8.0 | |
| SOFR M5/M6 | -39.5 | -43.0 | -3.5 | |
| SOFR M6/M7 | -9.0 | -12.5 | -3.5 | |
| EUR | 107.64 | 107.72 | 0.08 | |
| CRUDE (CLN4) | 77.76 | 77.84 | 0.08 | |
| SPX | 5127.79 | 5222.68 | 94.89 | 1.9% |
| VIX | 13.49 | 12.55 | -0.94 | |
https://www.youtube.com/watch?v=4T2GmGSNvaM
https://blinks.bloomberg.com/news/stories/SD3ZUUCGBL6O
Power Play
May 10, 2024
***************
–Market trades as if the liquidity spigots are wide open. Buy everything.
–Druckenmiller suggested a supply shortage in copper…this morning copper futures have exploded to a new high with HGN4 4.74. Gold and silver also bid. Attached is a chart of Dow Jones Utilities, powering higher, due apparently to an insatiable demand for electricity. Utilities are correlated with bonds, and the long bond yield has dropped 20 bps since April 25, from 4.81% to 4.60%. What’s driving what? PPI and CPI next week, Tuesday and Wednesday.


–Seemed like a light volume day yesterday, but there were quite a few bullish option plays on rate futures. Five year yield fell just over 4 bps yesterday to 4.458%, leading the decline in yields. FVM was +6 to 105-267. Open interest surged 64k to 6.15 million. I think that might be a record. Again, volume was quite low.
–On May 1, TYU4 settled 108-115
TYN4 109.5c 0’39s
TYN4 107.0p 0’35s so 4 to the call
Yesterday, TYU4 was almost exactly one point higher at 109-11
shifting strikes one point higher:
TYN4 110.5c 0’30s
TYN4 108.0p 0’26s
Still 4 to the call, though lower vols.
A lot of bullish rate plays. Solid 30 yr auction.
SOFR:
SFRZ4 9468/9443ps cov 9511.5, -27k 3.0
SFRU4 9493/9512/9525/9543c cond 2.75 to 2.875 paid 25k
SFRU5 9550/9650cs 39.0 paid 10k
SFRZ4 9550/9650cs cov 9515.5, 10.75 paid 5k
Early:
TYN 11.5c and 112c 23k bot each, 13 and 9
TYM 108.75/109.75 rr cov 109-01, 59d 0 to 1 paid call 20k
FVM 106.5/107cs 4.5 to 5.25 paid 25k (6s, new)
TYN 108/09/10 c fly 12 paid 10k
Binary outcomes
May 9, 2024
*************
–Quiet session with slightly higher yields, likely due to treasury auctions. Current 10y rose 3 bps to 4.49%. Auction tailed by 1 bp (4.483%). Thirties today. Late WI was 4.637%
–SOFR strip from SFRM5 to SFRM9 down 3 to 4.5. One large option play is an add, +60k 2QM4 9656.25/9662.5cs for 0.625 (synth). SFRM6 is underlying contract, settled 9598.5. nearly 60 otm with 36 dte. Also a buyer of 10k SFRU4 9700c for 1.75, settled 1.5 vs 9488. So that’s 212 away. On the downside the 9456.25p settled 1.5, 32 away. On the upside, risks of massive military escalation, domestic terrorism, political dysfunction, bank failures, mass hysteria, cats sleeping with dogs. Biblical stuff. On the downside, Fed might hike. What’s the more comfortable short?
–Atlanta Fed’s GDP Now estimated yesterday at 4.2% for Q2. However, a lot of data is starting to cast shade on consumer strength. Perhaps next week’s NY Fed Q1 Household Debt and Credit report will help shed some light on the fundamentals.
NEW YORK—The Federal Reserve Bank of New York will release its Q1 2024 Household Debt and Credit Report on Tuesday, May 14 at 11:00 AM.
Anecdotal Evidence of Struggling Consumers
May 8, 2024
*************
–Quiet market Tuesday with a bias toward flatter (more inverted) curve. 2y yield essentially unchanged while the 30y fell 4 bps to 4.604% as the US Treasury auctions 10s today and 30s on Thursday. New recent low in SFRU4/U5 one-yr calendar at -88 (9489/9577). June/June is -89 (most inverted), Sept/Sept -88 and Dec/Dec -76.5. I.e. roughly 3 to 4 eases in a given year.
–Consumer Credit for March was much lower than expected at just $6.27B, vs $15b expected. Table below shows the dramatic plunge in revolving growth: from 9.7% in Feb to 0.1% in March.
From the report:
“Consumer credit increased at a seasonally adjusted annual rate of 3.2 percent during the first quarter. Revolving credit increased at an annual rate of 5.7 percent, while nonrevolving credit increased at an annual rate of 2.2 percent. In March, consumer credit increased at an annual rate of 1.5 percent.”
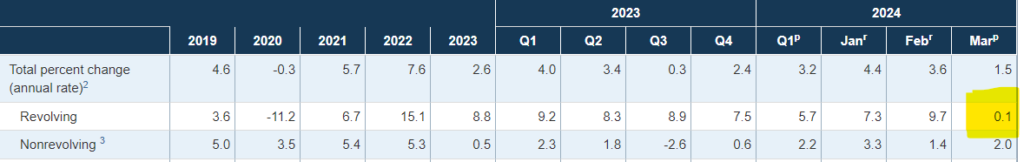
–It appears as though cracks in consumer spending are growing. As mentioned over the weekend, SBUX CEO complained about deterioration in the “occasional customer”. The stock immediately plunged 15% and edged to a new low yesterday. Disney reported yesterday. RTRS cited a drop in traditional TV and weaker box office. BBG cited “tepid outlook for growth in streaming”. Stock closed -9.5%. Does a tapped out middle-to-low end consumer represent a threat to stocks in general? Perhaps just anecdotal evidence…for now. But there’s also a chance that the administration’s “buy [votes] now, pay later” strategy peaked early.
–This is sort of a long article, but interesting with respect to Blackstone’s real estate funds (BREIT). Private fund with investors reliant on the company’s own pronouncements of NAV and investment flows.
Even as commercial real estate has been battered in the wake of the pandemic, BREIT has somehow managed to defy gravity, outperforming comparable funds by seemingly fantastic margins. In the fall of 2022, after the Fed’s interest-rate increases began to shake the commercial real-estate market, investors began asking for their money back — more than $15 billion to date…. Last year, BREIT failed to generate enough cash to cover its annual dividend.
https://www.msn.com/en-us/money/savingandinvesting/ar-BB1lXcUf
Tight now, easy later
May 7, 2024
*************
–Yields were nearly unchanged Monday, although near SOFR contracts were under slight pressure in front of today’s 3-year auction. Tens down 0.6 bp to 4.489%.
–May midcurve straddles expire Friday. On Thursday (pre-NFP) the atm short May straddle (9550) was 19.0. On Friday the atm 9562.5^ settled 14.0 vs 9562 and yesterday it settled 10.5.
–No surprises in SLOOS yesterday:
Over the first quarter, significant net shares of banks reported tightening standards for all types of CRE loans.
Over the first quarter, banks reported having tightened lending standards for some RRE loan categories.
Over the first quarter, banks reported tightening lending standards and most terms, on net, for all consumer loan categories.
Stocks took it as a positive sign. Obviously.
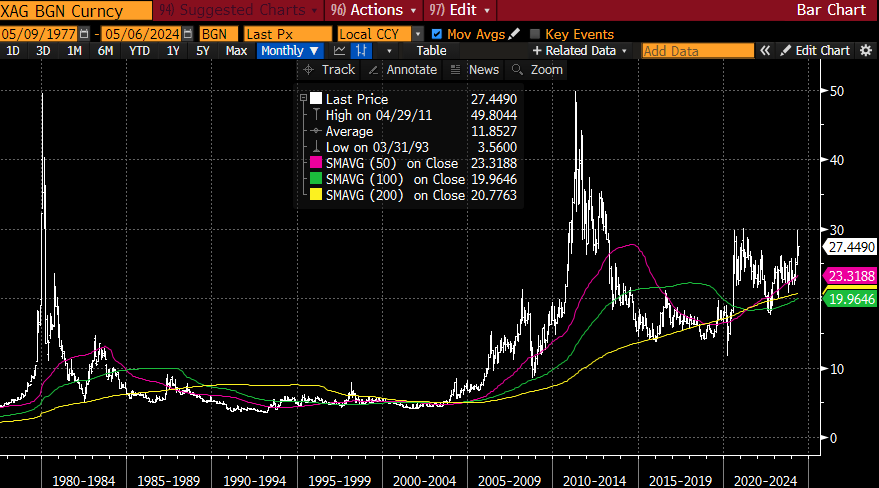
–Silver had a nice pop yesterday, up 92 cents to 27.615.
–Not quite sure how I missed the news that Herbert Hunt died on April 9. He and his brothers Bunker and Lamar tried to corner the silver market in late 1979 to 1980. According to the high price on BBG, at the end of March 1980 the price hit 49.45. It finally re-visited that level in June 2011 as it reached 49.80. Now it’s 27.44 (spot). An article in Time magazine highlighting the episode has some parallels to today: “Inflation had destroyed their faith in the dollar, so they began putting their wealth into a ‘harder’ currency: silver.”
https://content.time.com/time/subscriber/article/0,33009,920875-1,00.html
We can all relate to this:
As the brothers told the tale, they were just worrying, like most Americans, about the worsening economy. As Bunker Hunt has reportedly said, “A billion dollars is not what it used to be.” Inflation had destroyed their faith in the dollar, so early in 1979 they began putting even more of their wealth into a “harder” currency: silver. By late March they allegedly controlled almost two-thirds of the world’s privately held supply of the shiny metal, but “artificial factors,” like higher margin requirements and limits on the amount of silver futures contracts they could hold, spoiled all the fun.
https://www.federalreserve.gov/data/sloos/sloos-202404.htm
Yields and Vol down
May 6, 2024
*************
–Weaker than expected employment report at 175k sparked a rally in rate futures. SFRM5 and U5 were strongest on the strip at +12 (9562 and 9579). Current EFFR is 5.33% and SFRM5 is 4.38%, still nearly 100 lower. Ten year yield fell 7.2 bps to 4.495% in front of treasury auctions starting tomorrow, 3s, 10s, 30s. ISM Services also weak at 49.4.
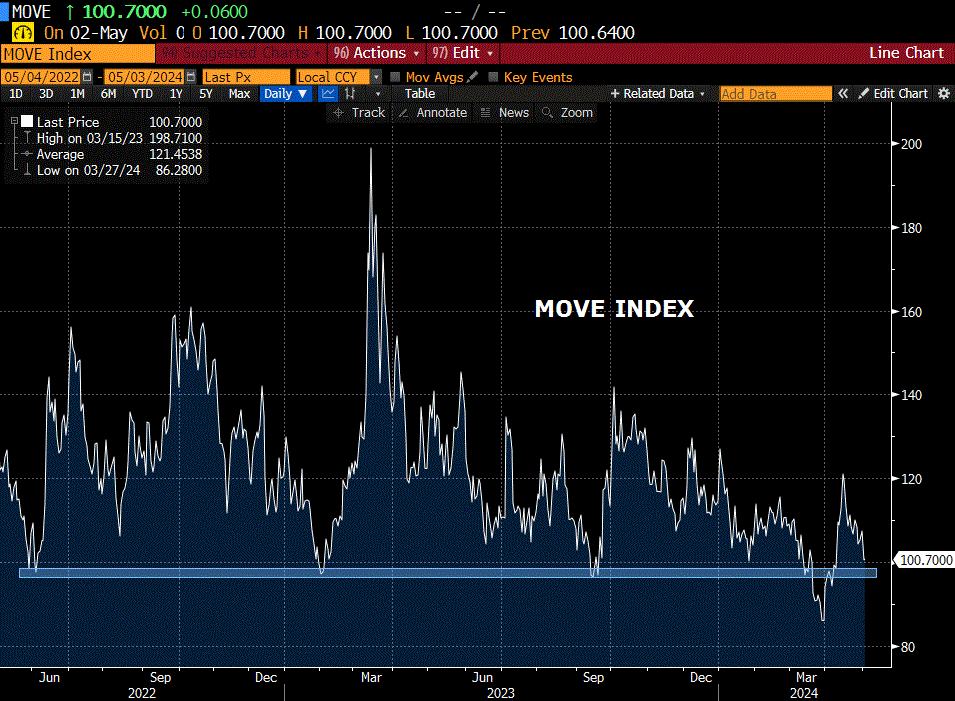
–With the fall in yields came a fall in implied vol. As the attached MOVE chart shows, we’re now approaching an area of hiking-cycle support. Today Barkin and Williams speak. SLOOS (Sr Loan Officer Opinion Survey) is this afternoon. Could be important as Powell had specifically cited it one year ago at the May 2023 FOMC.
–With May SOFR midcurves expiring Friday, 0QK4 9562.5 straddle settled 14 vs 9562.0. On Thursday the pre-NFP atm straddle was 19. Not a lot of economic data this week; 14 still likely a bit on the high side.
The Occasional Customer
May 5, 2024 – Weekly Comment
**********************************
SBUX – a canary?
SLOOS – Will be released on Monday. Gained prominence one year ago as Powell mentioned at May 3, 2023 press conference
Large decline oil – CLM4 down 5.74 on the week to 78.11
Treasury Auctions of 3s, 10s, 30s
Gov’t tax revenues – when yoy pct change is where it is now, we’re in recession
A couple of bullet points this weekend.
First, the change in trend, or in narrative, tends to happen at the margin. Then it either fizzles or gains traction, culminating in the tipping point. The 2006/07 subprime mortgage crisis was that way; in the beginning it was dismissively referred to as “…a mile wide and an inch deep”. Obviously that one snowballed.
On Thursday May 2, Starbucks CEO Laxman Narasimhan was interviewed by Jim Cramer. The stock was crushed during the interview as Cramer hammered away on lack of strategy. On a macro level, the most interesting excuse for unsatisfactory results was “…unexpected pressures on our occasional customers – more intense than we expected.” Cramer pounded away, saying he had checked with other public and private companies in similar businesses and none of them experienced negative same store sales, capping with this zinger, “Is it possible that your coffee is just too darn expensive?” LN response, “… if I look at the US occasional customer, they have clearly cut back on visits to us.” SBUX is a global company, but it seems to be a US problem.
Company specific, or beginning to permeate the economy? That’s the question. The ‘occasional customer’ is the marginal consumer. Last week’s consumer confidence at 97.0 was the lowest since covid, save for one print in 2022 at 95.3. ISM Mfg printed back below 50 at 49.2, but prices paid hit 60.9, highest in nearly two years. Payrolls and ISM Services both lower than expected. Obviously, the CORE US consumer is doing well, according to the numbers. Savers are getting great rates, and Household’s percent of equity in residential real estate, though off last year’s high, is currently 70.9%, which is above every level since 1960. Stocks are bid. Yay boomers. The MARGINAL consumer is getting hammered.
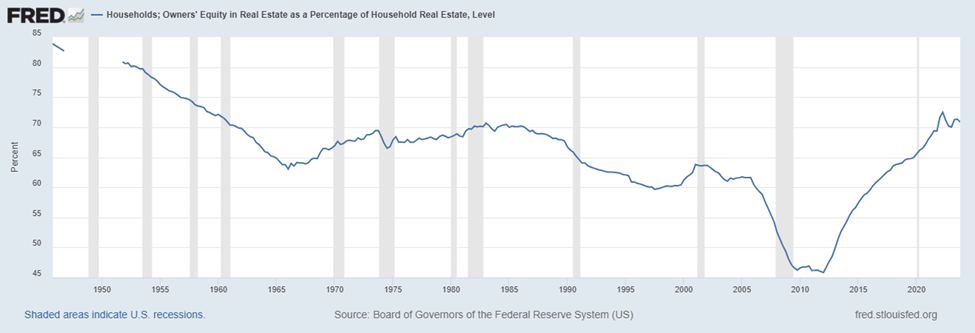
HH Owners Equity as Pct of HH Real Estate
SLOOS on Monday
SLOOS is the Senior Loan Officer Survey which gives an indication of credit tightness. One year ago Powell mentioned SLOOS at the May 3, 2023 press conference, as credit conditions were becoming more stringent (actual report was May 8). I believe SLOOS is released at 2 pm EST on Monday.
A BBG article over the weekend cites CRED iQ noting “Distress in CRE CLO loans jumps back up to record 8.6% in April.” Link at bottom.
CLM4 down $5.74 on the week
CLM4 ended the week at 78.11, right around the midpoint of the past three qtrs (active contract).
FEDL GOV’T TAX RECEIPTS, PCT CHANGE FROM YEAR AGO
This is an ominous chart. Any time it’s at this level, -7.5% in Q4 2023, we’re in recession. Treasury’s recent borrowing estimates indicated a shortfall in tax revenues. In Q1 2008 as this data slipped into negative territory, SPX was down about 38% three quarters later. In Q1 2001, SPX was about even three quarters later, but the trend was down.

Treasury auctions $58b 3s on Tuesday, $42b 10s on Wednesday and $25b 30s on Thursday.
Last week I noted “Demand for insurance continues to be weighted toward lower rates ensuing from an economic or financial ‘accident’.” The relief rally following FOMC and weak payrolls saw SFRU5 as the star contract, up 28.5 bps to 9579.0 or 4.21%. In treasuries 5s were the star, down 21.3 bps to 4.478%. Thirties fell just 12.2 bps to 4.66%. Implied vol was significantly lower to end the week (in front of limited economic data this week).
| 4/26/2024 | 5/3/2024 | chg | ||
| UST 2Y | 499.8 | 480.1 | -19.7 | |
| UST 5Y | 469.1 | 447.8 | -21.3 | |
| UST 10Y | 466.9 | 449.5 | -17.4 | wi 448.7 |
| UST 30Y | 478.1 | 465.9 | -12.2 | wi 465.7 |
| GERM 2Y | 298.8 | 292.4 | -6.4 | |
| GERM 10Y | 257.5 | 249.5 | -8.0 | |
| JPN 20Y | 165.0 | 168.3 | 3.3 | |
| CHINA 10Y | 230.6 | 231.5 | 0.9 | |
| SOFR M4/M5 | -64.0 | -90.5 | -26.5 | |
| SOFR M5/M6 | -41.5 | -39.5 | 2.0 | |
| SOFR M6/M7 | -12.5 | -9.0 | 3.5 | |
| EUR | 106.93 | 107.64 | 0.71 | |
| CRUDE (CLM4) | 83.85 | 78.11 | -5.74 | |
| SPX | 5099.96 | 5127.79 | 27.83 | 0.5% |
| VIX | 15.03 | 13.49 | -1.54 | |
https://twitter.com/JaguarAnalytics/status/1785905153054224854
https://blinks.bloomberg.com/news/stories/SCUYN7T1UM0W
Employment
May 3, 2024
*************
–Payrolls today expected 240k with Unemployment rate of 3.8%. Yields eased yesterday apart from the 30y bond. Twos -6.2 bps to 4.875%, tens -2.4 bps to 4.567% and bonds up just slightly at 4.717%. AAPL had a nice pop post earnings, apparently on buy back plans.
–Open interest in treasury futures up 1% or more as yields pulled back yesterday. An all clear to be long? Maybe, but if ‘term premium’ fears re-emerge there’s going to be that much more to puke. FV open int +69k to 6.085m, TY +58k to 4.457m, UXY +39k to 2.117m. US +13k to 1.588m. A lower than expected payroll number will likely bull steepen the curve, and positioning appears biased for that outcome.
–New buyer of 50k SFRH5 9625/9725cs for 5.5 to 6.0, settled 6.0 vs 9530. They’ve loaded up long SFRZ4 9600/9700 call spreads and are now pushing a bit further out the curve.
–August FF (FFQ4) settled 9476 or 5.24% against current EFFR or 5.33%. About 35% chance of a 25 bp ease at either the June 12 or July 31 FOMCs.
–No missive this weekend.
Relief that Powell wasn’t more hawkish
May 2, 2024
*************
–Yields fell as Powell’s press conference progressed. The FOMC statement cited a “lack of further progress toward the Committee’s 2 pct inflation objective.” However, balance sheet run-off was trimmed from $60b per month of treasuries to $25b, more than expected, while MBS remains at $35b. Powell sought to characterize the QT slowdown as a step to prevent repo rates from experiencing a surge, but the market apparently took it as a step toward ease. On the SOFR curve, SFRU4 +4, U5 +13.5, U6 +11.5 and U7 +10.0 (9483.5, 9558, 9589.5, 9598.5, with U7 being the peak price on the strip). In treasuries, 2’s rejected the pop over 5%, falling 10.4 bps to 4.937% while tens fell 9.1 to 4.591%.
–Powell described current policy as restrictive / weighing on demand. Rate futures slightly lower this morning.
–Buyer yesterday (adding) 50k SFRZ5 9475/9425/9375p fly for 5.0. Only -0.02 delta. Same in U5 settled 4.5 (was 4.5/5.0). Same in M5 and H5 settled 5.0. No benefit from roll. Also a short cover of SFRU4 9462.5p, paying 4.75 to 5.0 before the Fed. Open int fell 38k, settled 4.0.
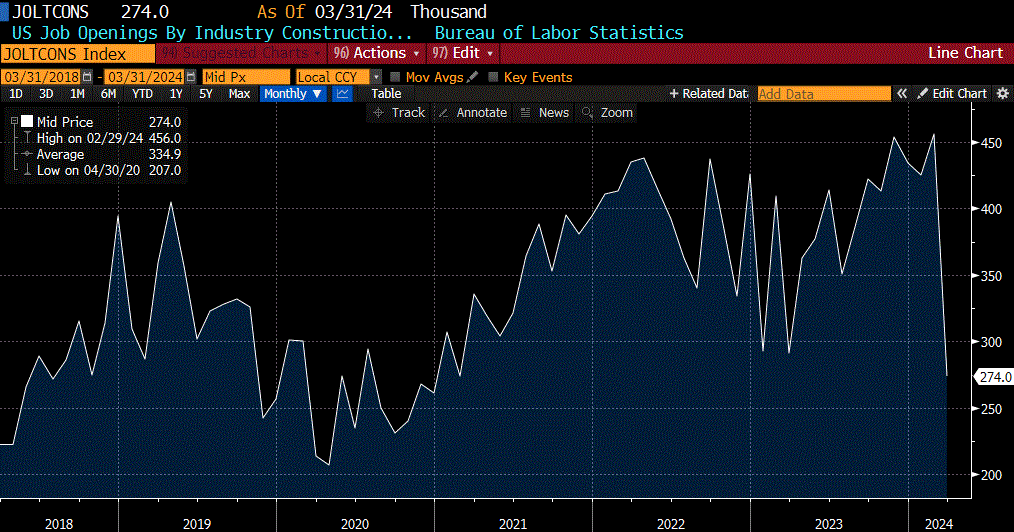
–ADP yesterday was slightly higher than expected at 192k. JOLTs only 8488 vs expected 8680 (chart of Construction Job Openings attached). ISM Mfg 49.2 while prices paid soared to 60.9 from 55.4 expected. New Orders 49.1 vs 51 exp. The other chart is pct change from year ago Federal Tax Receipts. When this goes negative, as it is now, we’re in recession. Treasury’s refunding announcement revealed more than expected issuance of about $40b on the quarter due to less than expected taxes. So the Fed is shaving supply by $35 billion a month while treasury adds about $13b per month ($13b more than expected).
–Japan intervened, likely adding some weight on treasuries. Today’s news includes Jobless Claims and Factory Orders. NFP tomorrow expected 243k. AAPL reports today; the stock has been in a steady slide since February.
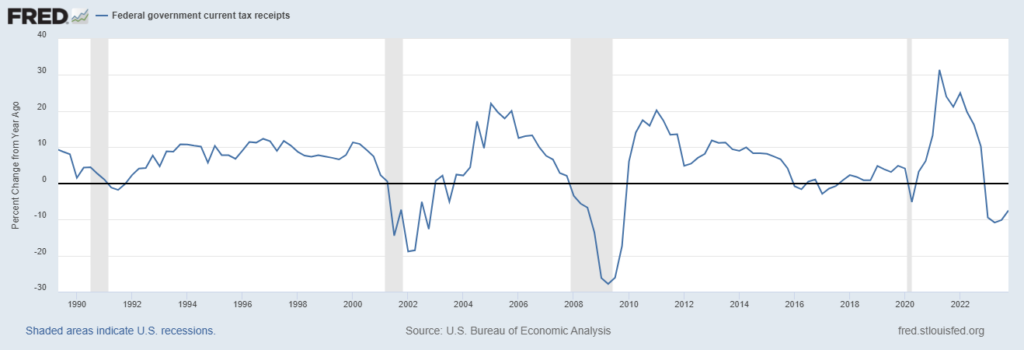
% chg year over year tax receipts above
CONSTRUCTION JOB OPENINGS below
Lighten up on risk
May 1, 2024
*************
–Full day. Treasury announces debt issuance composition at 8:30 EST. (Recall that Nov 1 was a surprise shift favoring t-bills, which helped long coupons rally in price). ADP, and JOLTs give clues on the labor market. ISM Mfg expected 50.1 from 50.3. Then the FOMC/ press conference.
–Yesterday the market reacted to a surprise ECI of 1.2% (expected 1.0). Yields higher, with 2’s at a new high for the year 5.041% (+4.1 bps) and everything else pressing against recent highs. Tens ended up 7 bps at 4.682%. Other data indicating economic malaise didn’t help to support fixed income. Consumer Confidence tanked to 97, lowest since covid, expected 104. Chgo PMI just 37.9 vs expected 45.0.
–In 1987 bond yields kept climbing while stocks blithely danced to new highs. Then came Black Monday with a single day drop of 22% in the Dow. Couldn’t happen now. It’s not Monday.
–On the SOFR strip slight new lows in reds to deferred, however, 2/10 at -36 and 5/30 at +7 bps are both holding sideways ranges. Concern about Powell leaning hawkish, but we already know that. SFRZ4 settled 9494 or 5.06%, down 7.5 bps on the day. That’s just 27 bps lower than the current EFFR of 5.33%, so the market is pricing only about one ease going into year end. Of course, the other policy tweak to consider is the slowdown in QT with expectations that MBS will still be reduced $35b per month, but treasuries shaved to $30b from $60b.
–USD continues to strengthen which creates tight GLOBAL financial conditions. DXY is near the high of the year. (Anti-dollar) bitcoin is free-falling to 57k this morning from 75k in mid-March.

